Illustration of a glowing light bulb with a stylized capital “A” filament centered inside, symbolizing ideas, innovation, and insight against a green circular background.

The Daily Spark

Stay ahead of the markets with The Daily Spark at Apollo. Get exclusive, daily data-driven analysis on the US economy, inflation, and capital markets from Apollo Chief Economist Torsten Slok.
Subscribe About the Author

Not subscribed yet? Get the Daily Spark delivered to your inbox.

Subscribe
Filters
Topics
1-10 of 631 Results
Financial Markets & Risk Dynamics

September 25, 2026

Higher for Longer Hits the Lowest Rated

Share

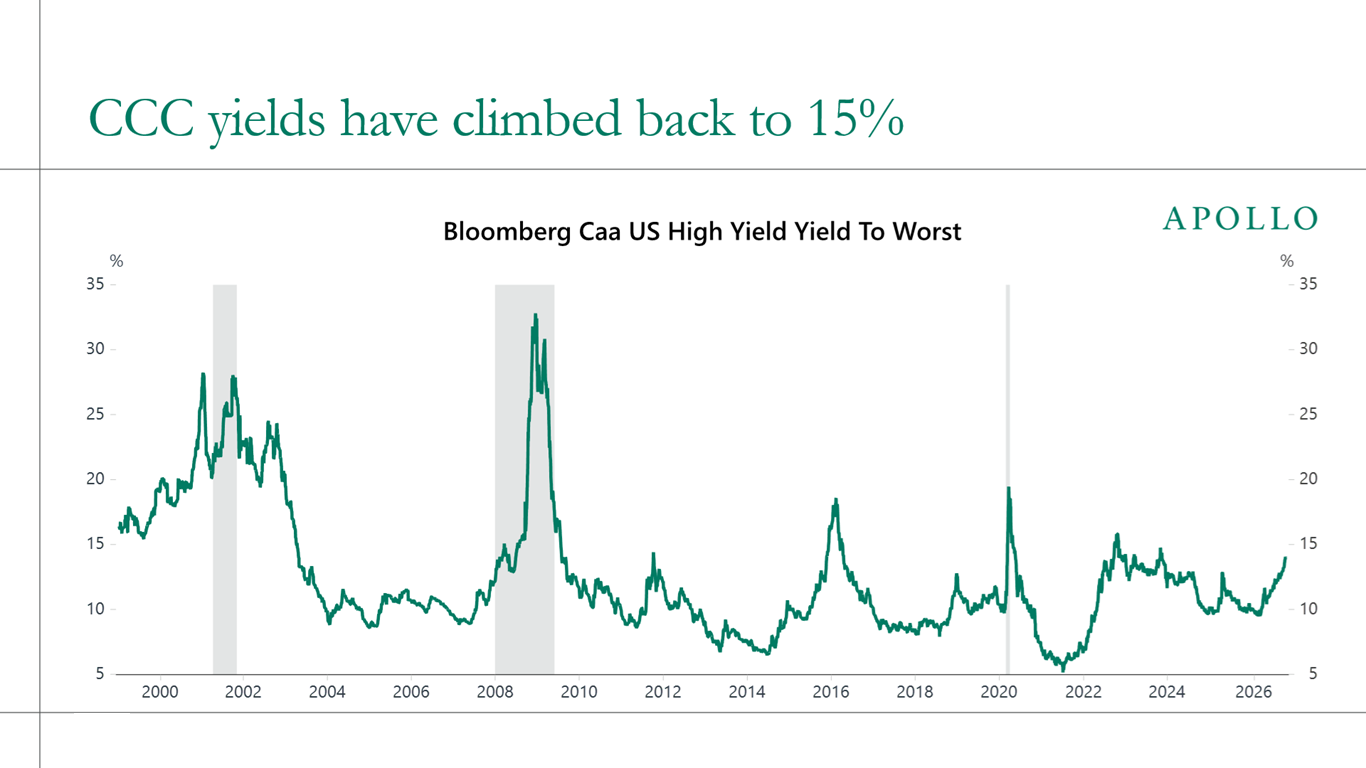
Higher for longer is a slow squeeze for low-quality credit. Every month rates stay elevated, more CCC borrowers from the 2021–22 vintages hit the refinancing wall with less cash to service their debt, and with CCC yields around 15% while the broader credit market stays calm, the bill from the cheap-money era is landing on the weakest balance sheets first.

The pain is sharpest in heavily levered, PE-backed technology, healthcare and consumer discretionary names, where floating-rate debt, thin margins and AI disruption risk leave little room to absorb years of elevated borrowing costs.

The bottom line is that monetary policy is working with a lag and working unevenly. Strong balance sheets locked in cheap fixed-rate debt and have barely felt the Fed's tightening, while the most leveraged borrowers feel it in full as floating-rate costs and maturities reset, so the transmission mechanism is running mainly through the bottom of the credit stack.

For investors, the message is to move up in quality, because high-quality credit still offers attractive all-in yields without the default, restructuring and liability-management risk that is now concentrated in lower-rated credits.

In short, it is a good idea to invest in companies with earnings because they can pay their higher debt-servicing costs.

Download high-res chart

See important disclaimers at the bottom of the page.

Macroeconomic Indicators & Trends

September 24, 2026

AI Adoption Is Spreading. AI Spending Is Concentrating

Share

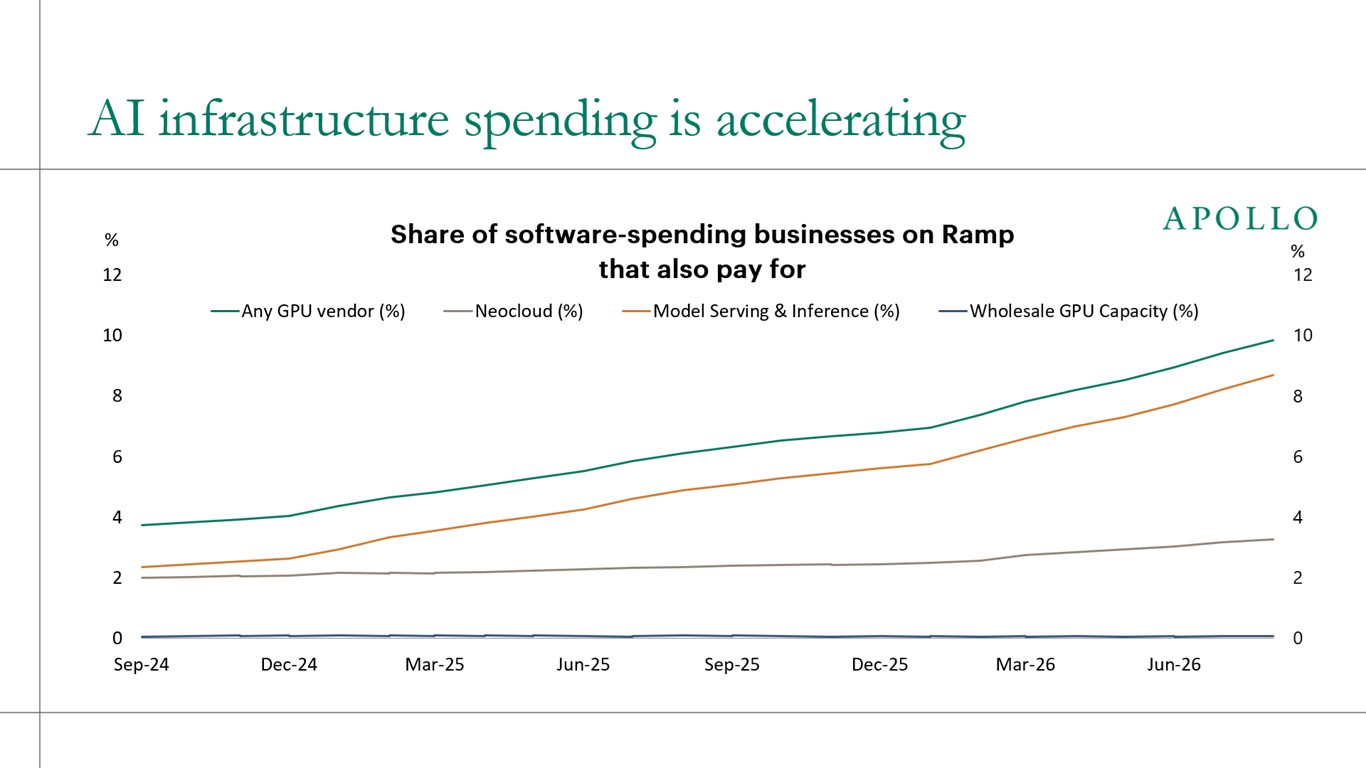
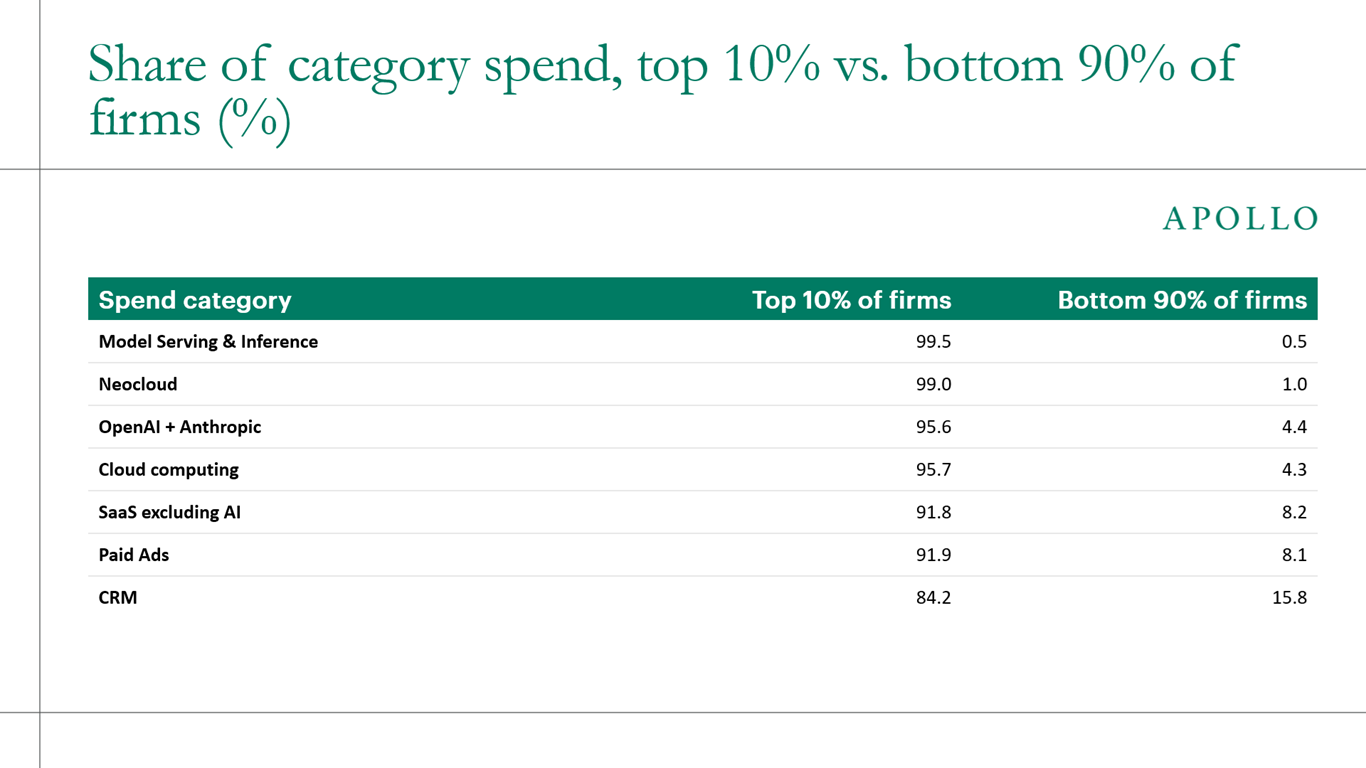
Roughly 10% of software-spending businesses on Ramp now pay a GPU vendor, up from under 4% two years ago, see chart below. Nearly all of that came from model serving and inference, which went from 2.4% to 8.7% of firms, while neoclouds crept from 2.0% to 3.3%, and wholesale GPU capacity never left the floor at 0.1%.

That gap describes what most companies are actually doing with AI. Businesses are adding a model to an existing product or workflow, paying per call, and treating it as another software subscription they can cancel next month. Very few are building anything that requires owning or reserving the hardware underneath.

The table below shows how unevenly the dollars land. The top 10% of customers account for 99.5% of model-serving spend and 99% of neocloud spend, leaving the bottom 90% of firms with 0.5% and 1%.

For comparison, non-AI SaaS is at 91.8% and CRM at 84.2%, where the long tail still contributes a real 15.8%, because a small company buying a CRM buys something close to what a large one buys. AI spending tracks how much you run, not how many people you have, which is why a small number of firms in production dwarf everyone else.

The bottom line is that adoption is broadening while the spending base is not, and AI infrastructure will keep depending on a small set of heavy spenders until the tail scales up.

Download high-res charts

See important disclaimers at the bottom of the page.

Macroeconomic Indicators & Trends

September 23, 2026

The Diesel Shock Is a Core Inflation Shock

Share

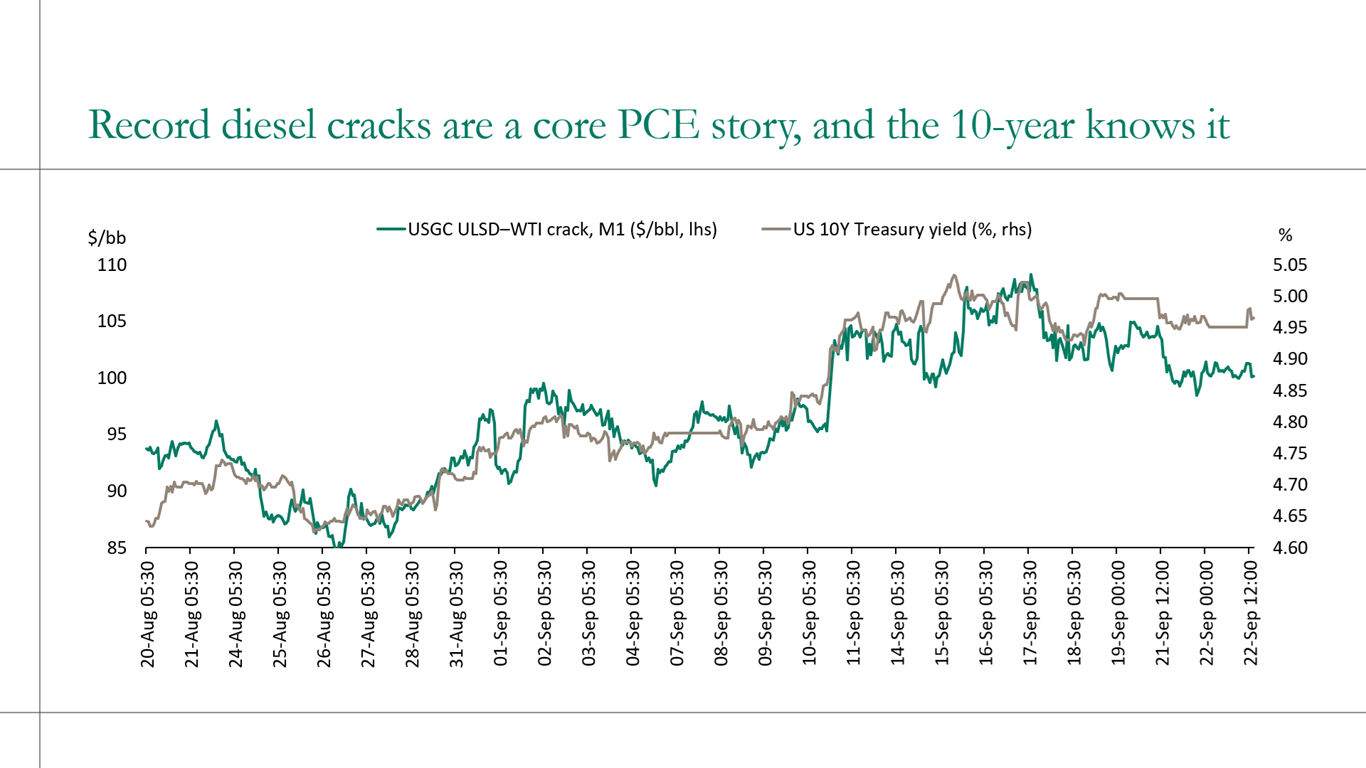
The US Gulf Coast diesel crack spread cleared $100/bbl for the first time on record in August against a normal range of $15 to $30. Unlike a gasoline spike, which lands on consumers as a one-time tax on discretionary spending, diesel is an intermediate input embedded in the delivered cost of nearly every physical good, from freight and rail to agriculture and construction.

That means the rise in diesel prices does not stay in the energy line of the CPI but migrates with a lag into core goods and services, which is exactly the kind of pass-through the Fed cannot dismiss as transitory.

The bottom line is that diesel margins are now setting the long end of the curve because diesel crack spreads are an important driver of future core inflation.

Download high-res chart

See important disclaimers at the bottom of the page.

Financial Markets & Risk Dynamics

September 22, 2026

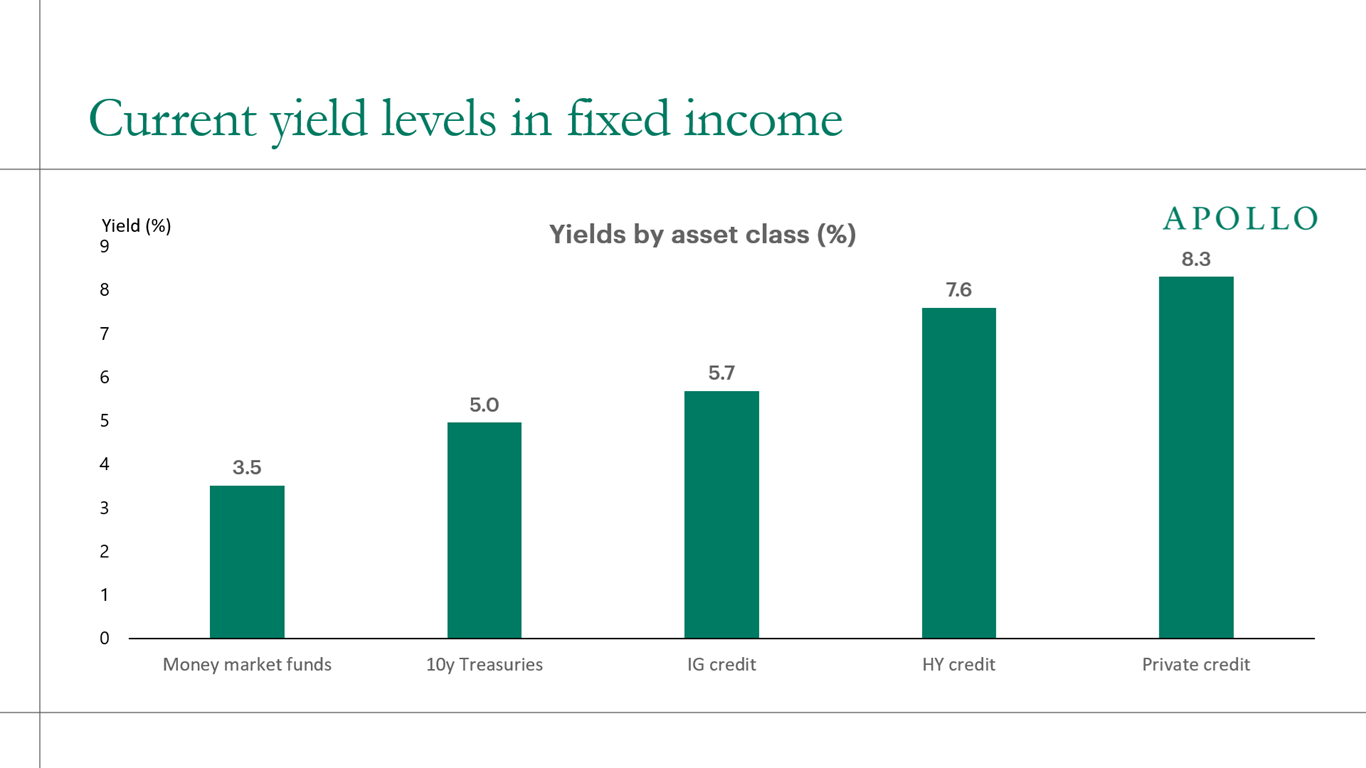
Yield Levels Starting To Look Juicy

Share

After a decade of reaching for yield in a zero-rate world, investors no longer have to take outsized risk to generate income. Even if yields rise further from here, current levels in high-quality fixed income are already attractive, both for households and for investors with long-duration liabilities.

Download high-res chart

See important disclaimers at the bottom of the page.

Financial Markets & Risk Dynamics

September 21, 2026

Hyperscaler Credit Rests on One Consensus Assumption

Share

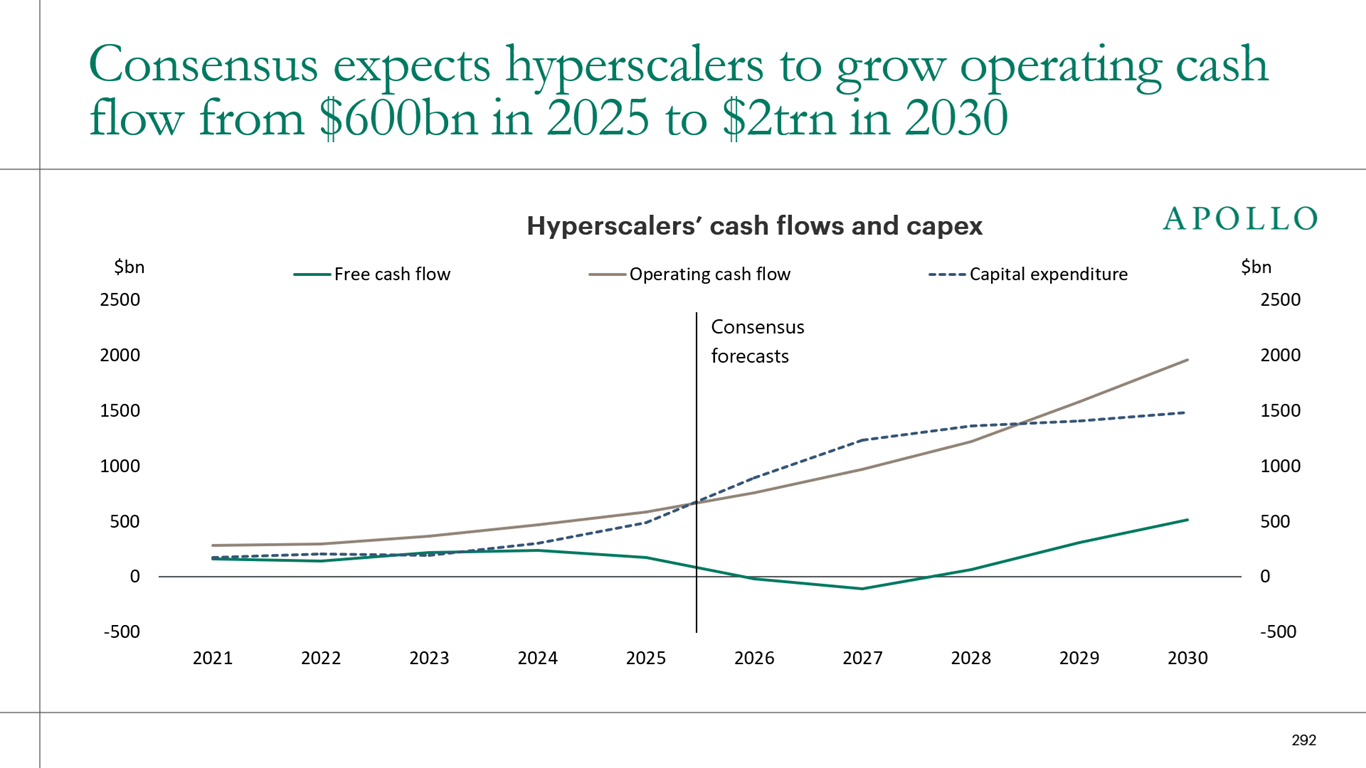
The credit story in hyperscalers rests on a single consensus assumption, that operating cash flow triples from $600 billion to $2 trillion, see chart below.

If this doesn't happen, then the risk is that the AI trade weakens, with credit spreads widening, capex plans getting cut and ultimately US GDP growth slowing.

Download high-res chart

See important disclaimers at the bottom of the page.

Macroeconomic Indicators & Trends

September 20, 2026

AI Needs Copper Now, New Mines Arrive in the 2040s

Share

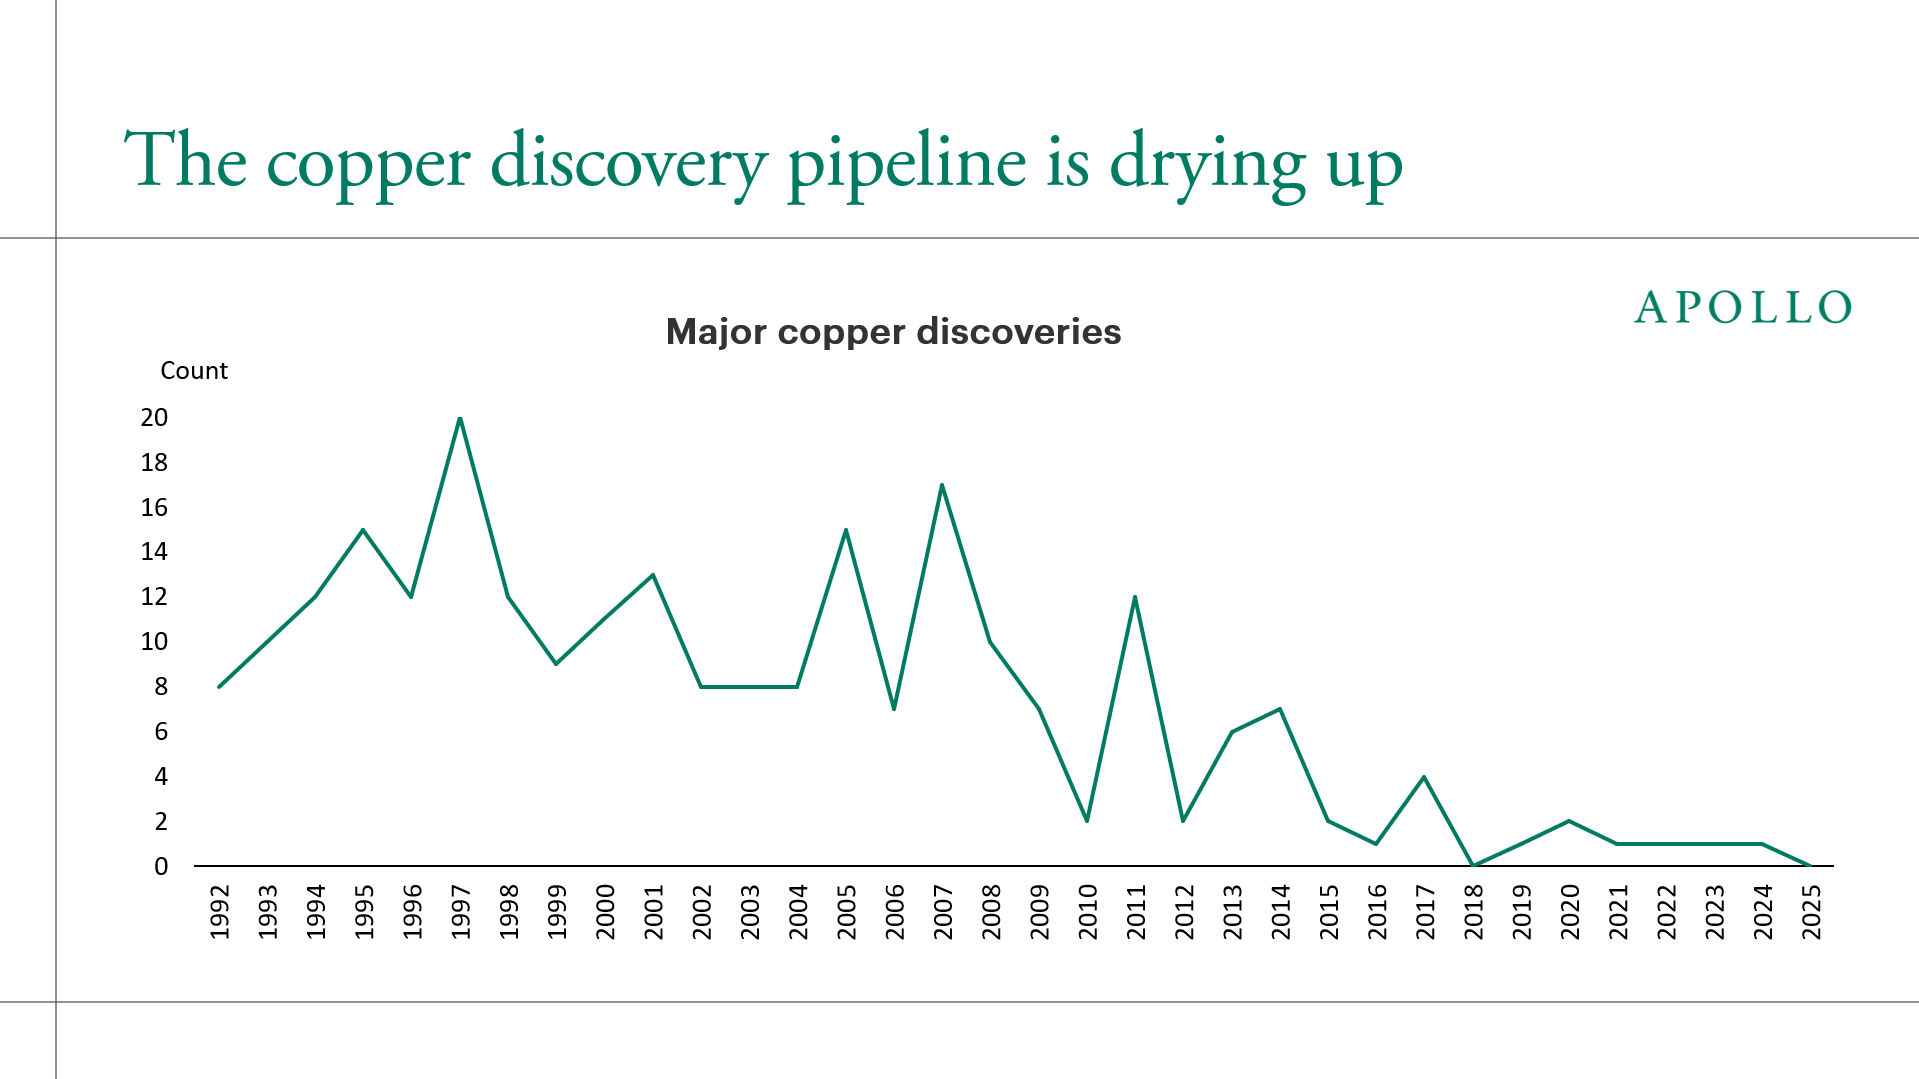
Major copper discoveries, meaning deposits with at least 500,000 tonnes of contained copper, have fallen from double digits annually in the 1990s and 2000s to one or two in recent years, with none in 2025. Because a new deposit takes roughly 18 years to reach production, the chart below describes supply in the 2040s.

Meanwhile, the AI data center buildout is adding copper-intensive load on a two- to three-year cycle, pointing to a structurally tighter market and upward pressure on prices.

Download high-res chart

See important disclaimers at the bottom of the page.

Macroeconomic Indicators & Trends

September 19, 2026

Not Tech, Not Wall Street

Share

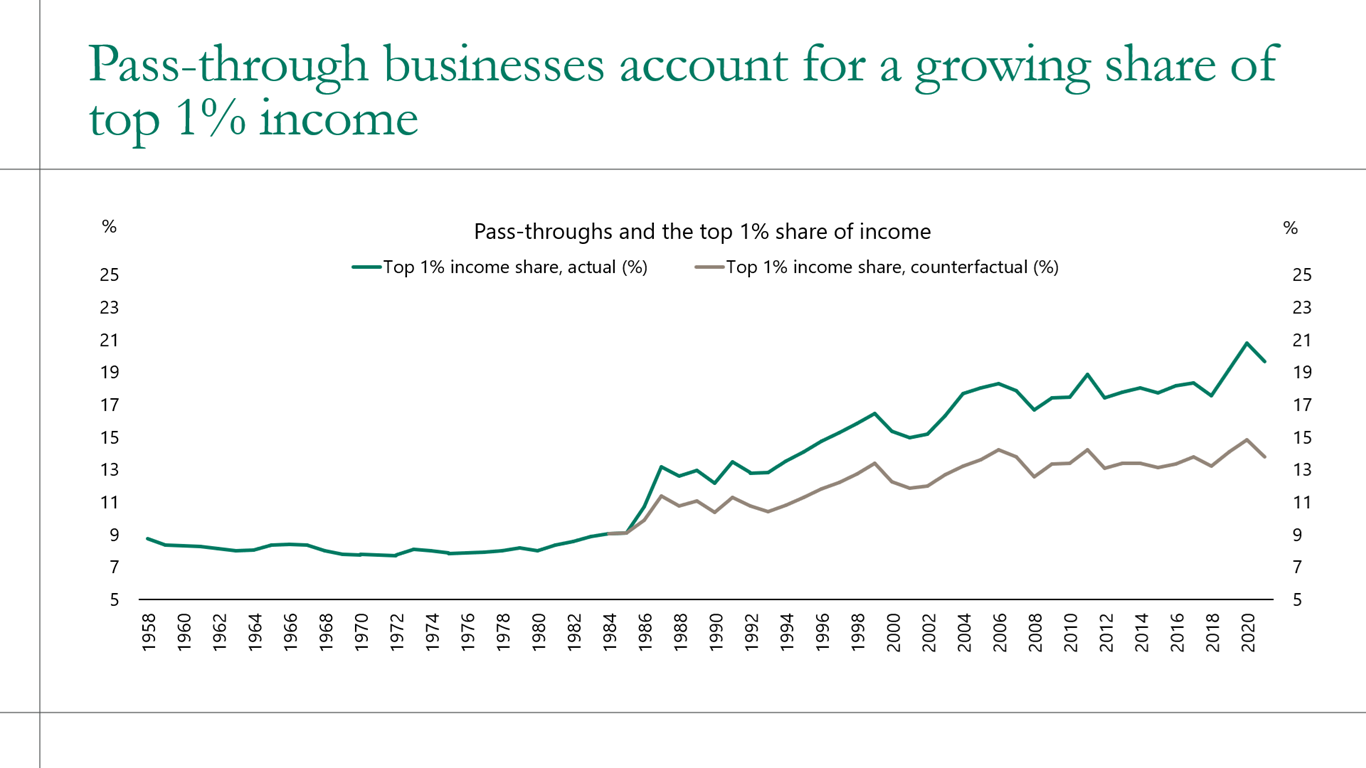
The income that lifted America's top 1% did not come mainly from tech or Wall Street, according to The Everywhere Millionaire. More than half of the rise in the top 1% income share since 1985, 5.8 of 10.5 percentage points, flowed through pass-through businesses, see chart below.

The authors, Owen Zidar and Eric Zwick, counted roughly 3 million wealthy private business owners, with average net worth near $25 million, running law firms, car dealerships, medical practices, commercial contractors and regional restaurant chains, the kind of businesses that make their owners wealthy and well known in their own communities without ever making them nationally famous.

Download high-res chart

See important disclaimers at the bottom of the page.

Monetary & Fiscal Policy

September 18, 2026

Warsh Starting to Look Like Volcker

Share

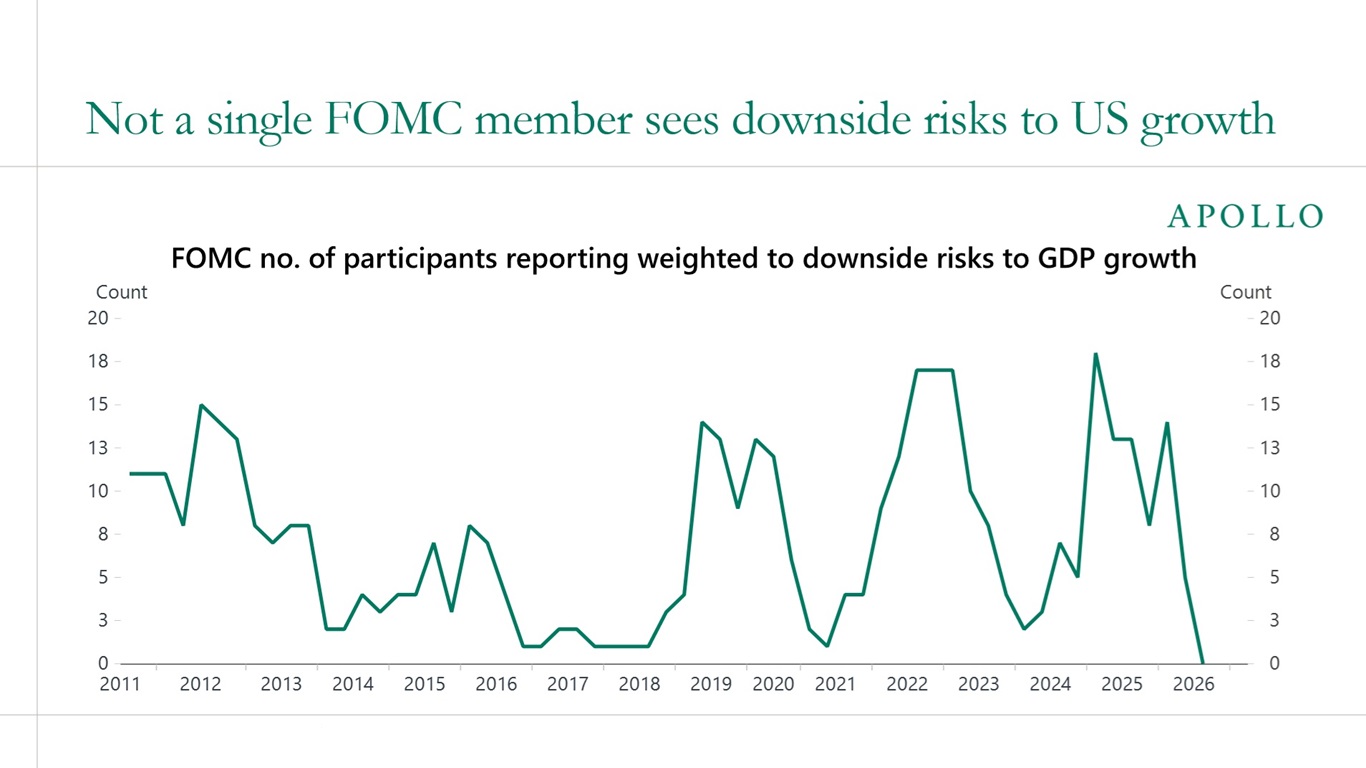
Fed Chair Kevin Warsh has been remarkably consistent. He has repeatedly said the Fed will deliver price stability. Wednesday’s rate hike shows that he means it.

There is another important parallel with former Fed Chair Paul Volcker: no forward guidance. Volcker did not tell markets what the Fed would do at the next meeting. Warsh takes the same approach.

The bottom line is that Warsh is following the number one principle for successful central bankers: say what you do, and do what you say.

Download high-res chart

See important disclaimers at the bottom of the page.

Global & Geopolitical Developments

September 17, 2026

Europe’s AI Buildout Is Missing a Financing Market

Share

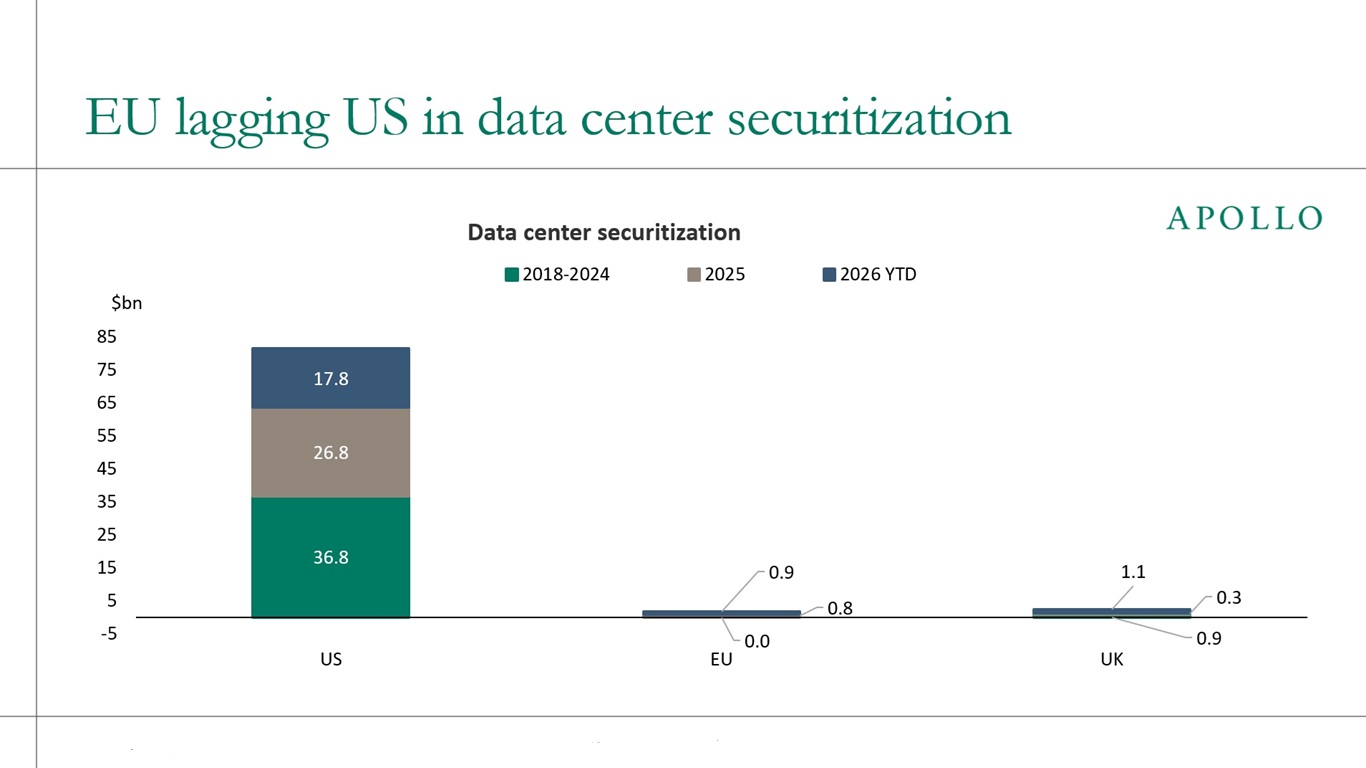
Securitization of US data center debt has totaled $81.4 billion since 2018, of which $18 billion was in 1H 2026 alone, see the first chart below. The EU has seen just $1.7 billion, of which $0.9 billion was in 1H 2026. The UK is little better, with $2.3 billion since 2018, of which $1.1 billion was in the first half of the year.

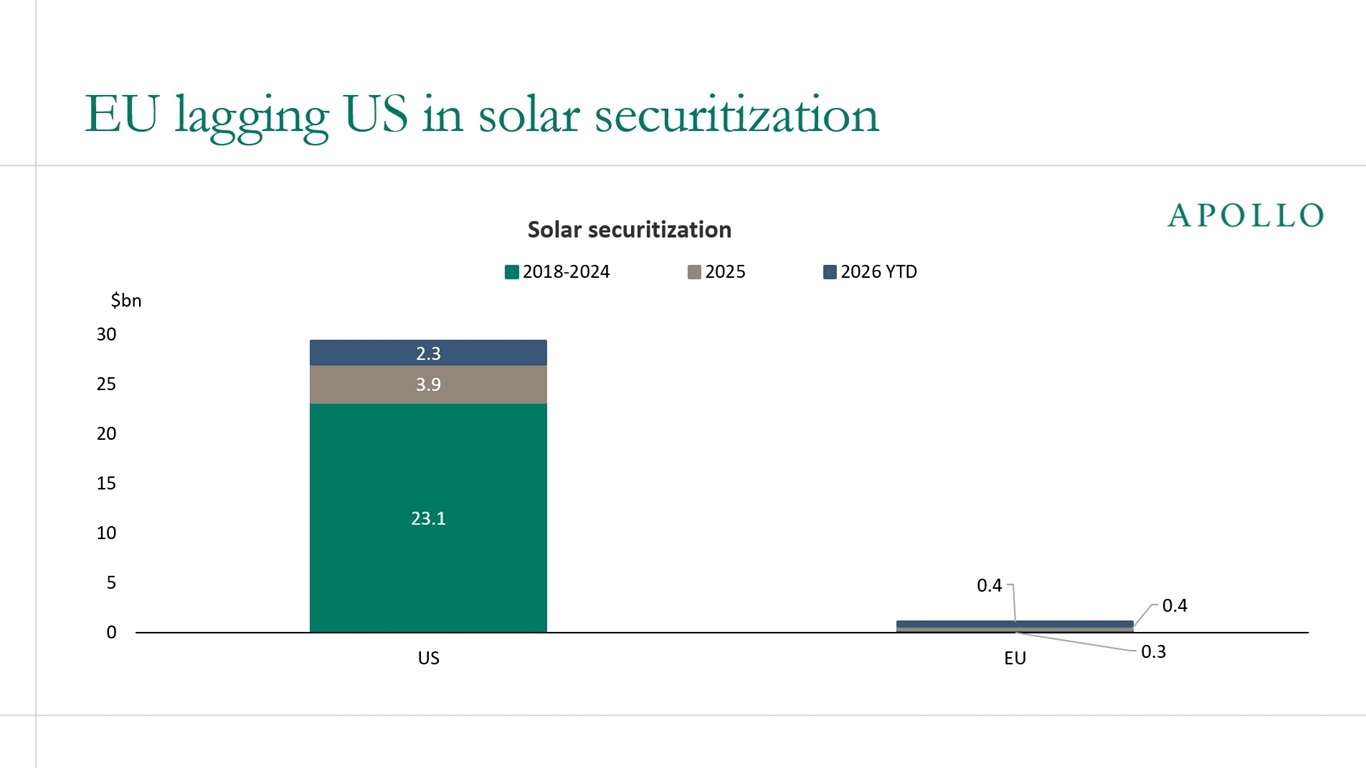
The gap extends beyond just data centers to other strategic assets. US solar securitizations have raised $29.3 billion since 2018, compared with just $1.1 billion in the EU, see the second chart below.

Part of the problem has been overly burdensome securitization rules compounded by insurance regulations that have discouraged European life insurers. EU life insurers hold just 0.33% of their investment assets in securitizations, compared with roughly 17% for US life insurers, despite the two industries being similar in size. The EU has proposed tweaks to its securitization rules, but the changes are modest relative to the scale of the financing challenge.

If Europe wants to narrow the AI investment gap with the US, it will be harder if one of the markets helping finance the US data center buildout remains largely closed in Europe.

Written by Huw van Steenis, London

Download high-res charts

See important disclaimers at the bottom of the page.

Financial Markets & Risk Dynamics

September 16, 2026

Hyperscaler CDS Widening Is Not a Dealer Inventory Story

Share

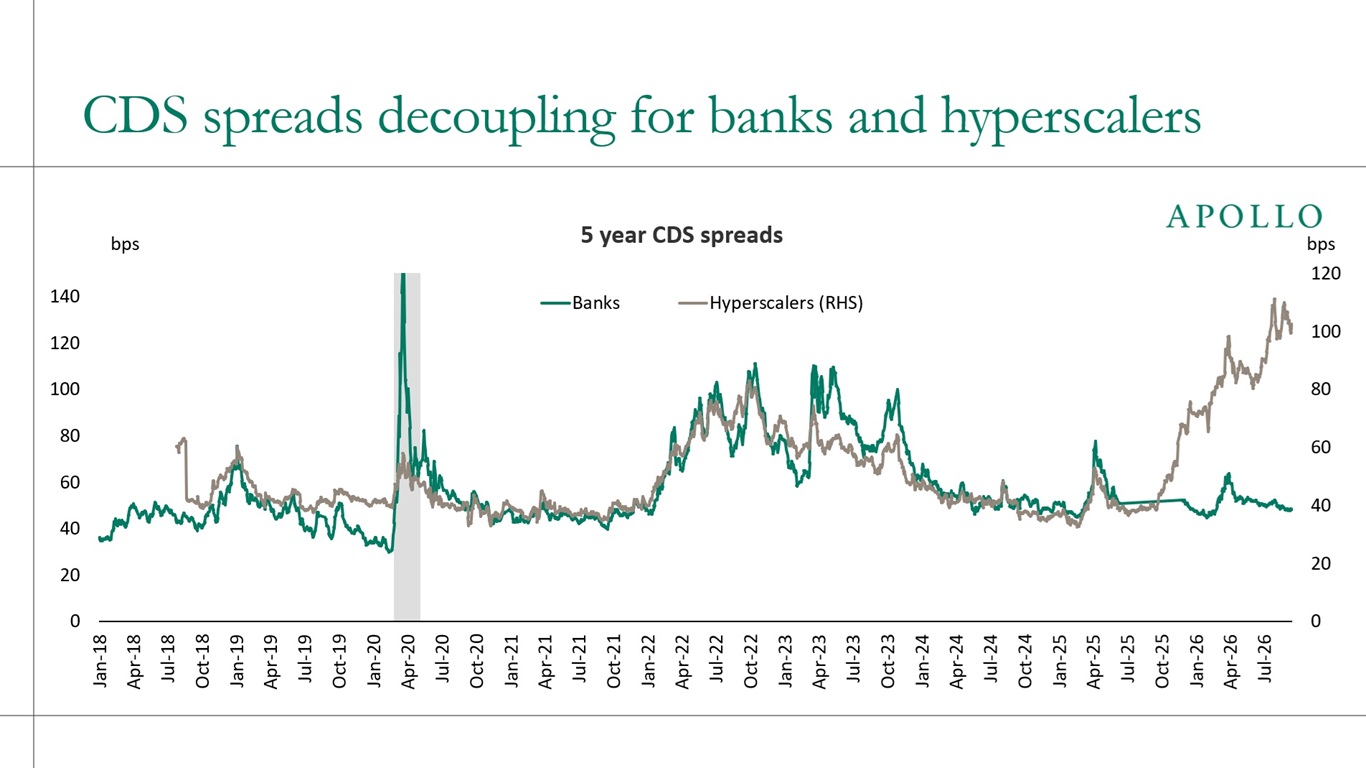
The widening in hyperscaler CDS is not driven by dealer hedging of new issuance. If it were, bank CDS would be widening too, given that banks remain the single largest source of IG supply, and instead bank spreads have sat flat near 40 bps. What the market is repricing is hyperscaler credit fundamentals, namely a debt-financed AI capex cycle with rising leverage, negative free cash flow and uncertain payback on depreciating assets.

Download high-res chart

See important disclaimers at the bottom of the page.

This presentation may not be distributed, transmitted or otherwise communicated to others in whole or in part without the express consent of Apollo Global Management, Inc. (together with its subsidiaries, “Apollo”).

Apollo makes no representation or warranty, expressed or implied, with respect to the accuracy, reasonableness, or completeness of any of the statements made during this presentation, including, but not limited to, statements obtained from third parties. Opinions, estimates and projections constitute the current judgment of the speaker as of the date indicated. They do not necessarily reflect the views and opinions of Apollo and are subject to change at any time without notice. Apollo does not have any responsibility to update this presentation to account for such changes. There can be no assurance that any trends discussed during this presentation will continue.

Statements made throughout this presentation are not intended to provide, and should not be relied upon for, accounting, legal or tax advice and do not constitute an investment recommendation or investment advice. Investors should make an independent investigation of the information discussed during this presentation, including consulting their tax, legal, accounting or other advisors about such information. Apollo does not act for you and is not responsible for providing you with the protections afforded to its clients. This presentation does not constitute an offer to sell, or the solicitation of an offer to buy, any security, product or service, including interest in any investment product or fund or account managed or advised by Apollo.

Certain statements made throughout this presentation may be “forward-looking” in nature. Due to various risks and uncertainties, actual events or results may differ materially from those reflected or contemplated in such forward-looking information. As such, undue reliance should not be placed on such statements. Forward-looking statements may be identified by the use of terminology including, but not limited to, “may”, “will”, “should”, “expect”, “anticipate”, “target”, “project”, “estimate”, “intend”, “continue” or “believe” or the negatives thereof or other variations thereon or comparable terminology.