Illustration of a glowing light bulb with a stylized capital “A” filament centered inside, symbolizing ideas, innovation, and insight against a green circular background.

The Daily Spark

Stay ahead of the markets with The Daily Spark at Apollo. Get exclusive, daily data-driven analysis on the US economy, inflation, and capital markets from Apollo Chief Economist Torsten Slok.
Subscribe About the Author

Not subscribed yet? Get the Daily Spark delivered to your inbox.

Subscribe
Filters
Topics
1-10 of 646 Results
Global & Geopolitical Developments

October 10, 2026

New Academic Papers

Share

Here are five new interesting papers that are relevant for the ongoing conversation in markets.

  1. Decoupling Direct Investment: American Firms' Retreat from China
    • The author documents evidence that US-China linkages are declining across channels. New project announcements and US acquisitions of Chinese companies are down, and American multinationals are shrinking their existing operations. Official statistics understate the extent of the retreat because of how much US investment is routed through Hong Kong.
  2. The Early Impacts of AI on Employment among Recent College Graduates
    • Using CPS microdata, the authors analyze the effects of AI on recent college graduate unemployment through August 2026 to argue that AI is still not having a material impact on the US labor market. They find that summer 2026 unemployment trends for recent college graduates follow typical seasonal patterns, and no evidence of any significant displacement of recent college graduates. The authors do find some limited evidence of higher unemployment in telework-focused roles.
  3. The Macroeconomic Effect of AI: Sizing the Software Engineering Channel
    • The authors use stock market returns and Revelio Labs data to estimate a market-implied expectation for AI productivity. Between November 2022 and December 2025, market expectations implied the equivalent of a permanent 32.6% increase in software engineering productivity, worth 3.6% of GDP. By mid-2026, amid rapid improvement in AI coding agents, the estimated effect had more than doubled. I am slightly skeptical how well this is capturing productivity versus some other kind of AI market factor, but I thought this was quite an interesting approach regardless.
  4. Will AI Help or Hurt Work and the Economy? What People Around the World Expect
    • This paper summarizes the findings of a survey of more than 64,000 adults in 32 countries taken in April and May 2026. The surveys finds that workers are considerably more likely to expect AI to help their jobs than to threaten them, in contrast to the narrative in the US about AI-driven job displacement. Survey respondents who expect AI to help anticipate stronger growth and employment, while those who see it as a threat expect weaker employment and higher inflation.
  5. Ratings, Debt, and Deficits: An Exploration
    • The authors compare a simple model of debt sustainability with actual sovereign credit ratings. They find that ratings agencies give far more weight to debt levels than projected fiscal balances, and they rely heavily on country-specific factors. As a result, countries with the same debt and fiscal outlook can receive very different ratings.

Written by Allison Boxer

See important disclaimers at the bottom of the page.

Monetary & Fiscal Policy

October 09, 2026

AI’s Insensitivity to Interest Rates Is a Problem for the Fed

Share

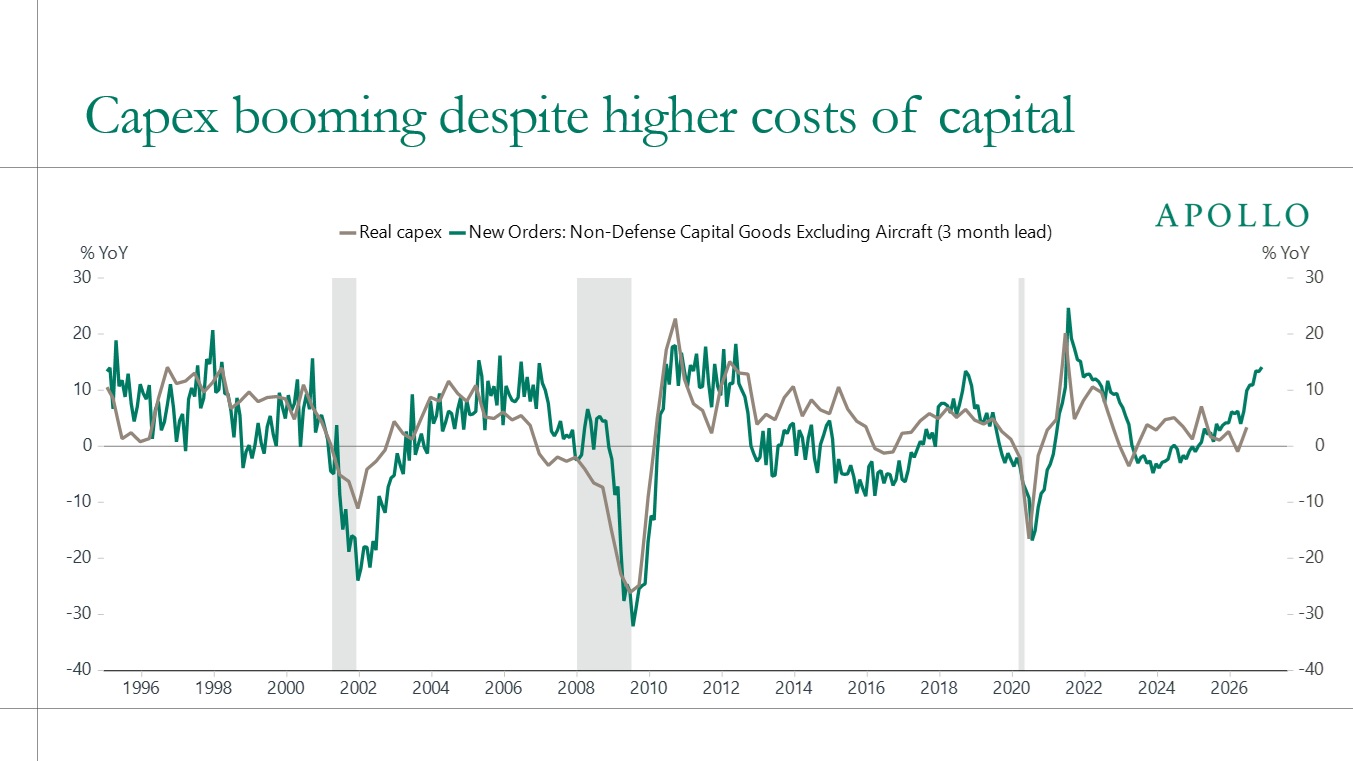
AI's rate-insensitive boom is triggering "Dutch disease" in the US economy by draining capital, power and labor from vulnerable sectors like housing and autos.

Trapped between inflation driven by the AI boom and weakness in rate-sensitive industries, the Fed will have to keep interest rates higher for longer, see chart below.

Because monetary policy cannot resolve this sectoral imbalance, the only durable fix is expanding the supply of power, chips and infrastructure.

For more discussion, see also here.

Download high-res chart

See important disclaimers at the bottom of the page.

Financial Markets & Risk Dynamics

October 08, 2026

Outlook for French Spreads

Share

We've put together a chart book on France and the ECB, it is available here.

It shows French spreads over Germany at their widest since the 2011 euro crisis, with fiscal pressures building ahead of the October 13 budget debate.

At the same time, the macro backdrop remains solid, European banks are in their best health in decades and the ECB has several options available should financial stability be threatened.

Download chart book

See important disclaimers at the bottom of the page.

Financial Markets & Risk Dynamics

October 07, 2026

Europe Is Financing the US AI Buildout

Share

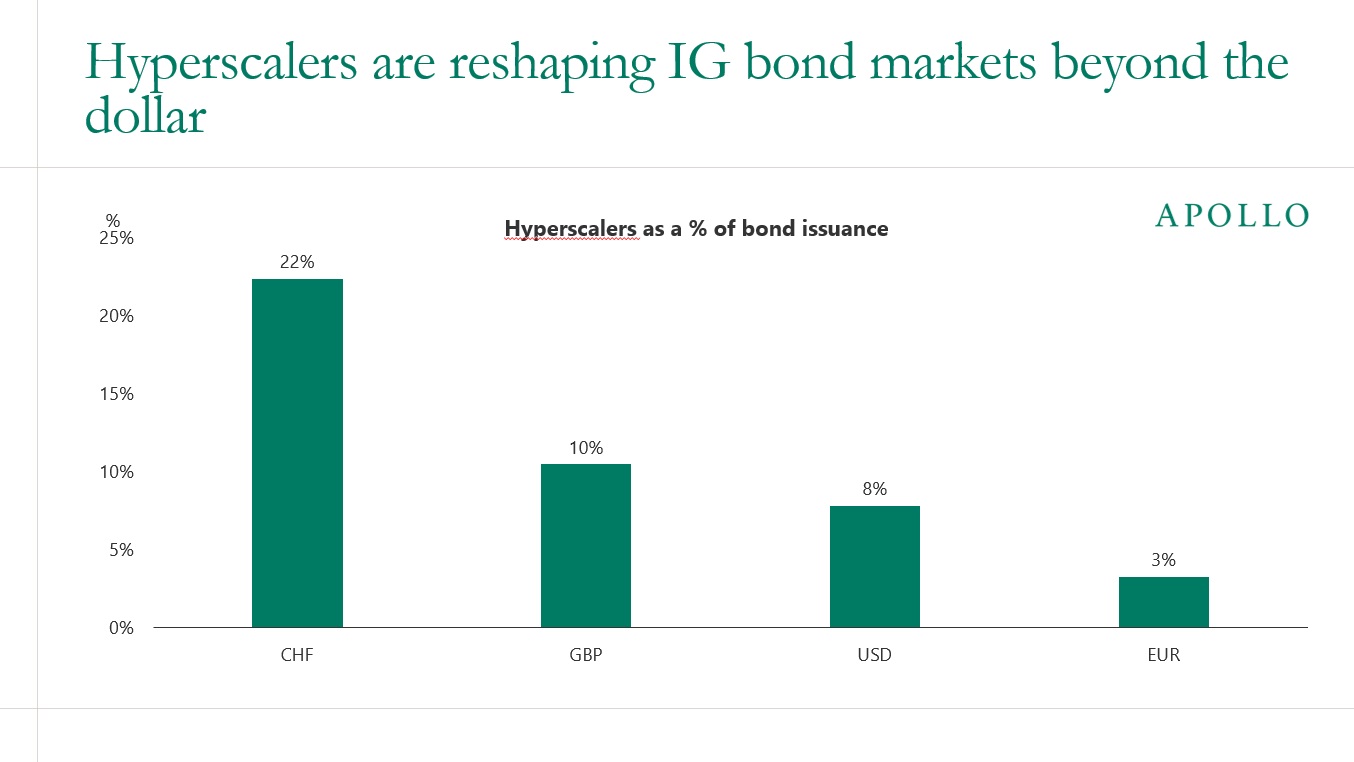
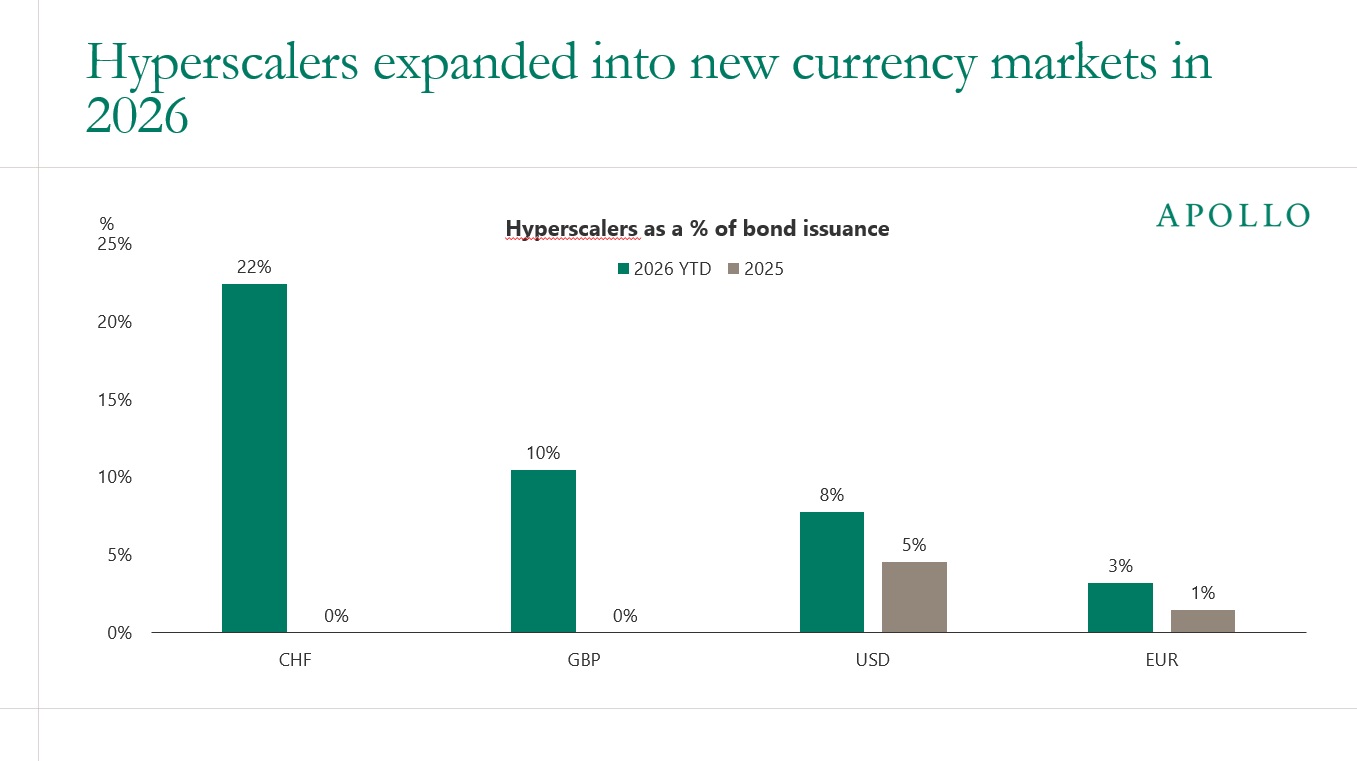
Hyperscalers have raised $48 billion in bonds in European currencies this year, which is already more than triple the entire amount of 2025. This is spread across €27 billion, £13 billion and CHF7.5 billion.

Hyperscalers now account for 3% of euro IG issuance, 10% of sterling IG issuance and 22% of Swiss franc IG issuance this year, compared with 8% of US IG corporate issuance, see the first chart below.

There are few signs of crowding out, yet. Non-hyperscaler IG issuance remains strong and is little changed YoY, and corporate spreads remain tight. Rather, hyperscaler issuance is adding highly rated US borrowers (AA- or higher) to European credit indices that have traditionally had more A to BBB exposure.

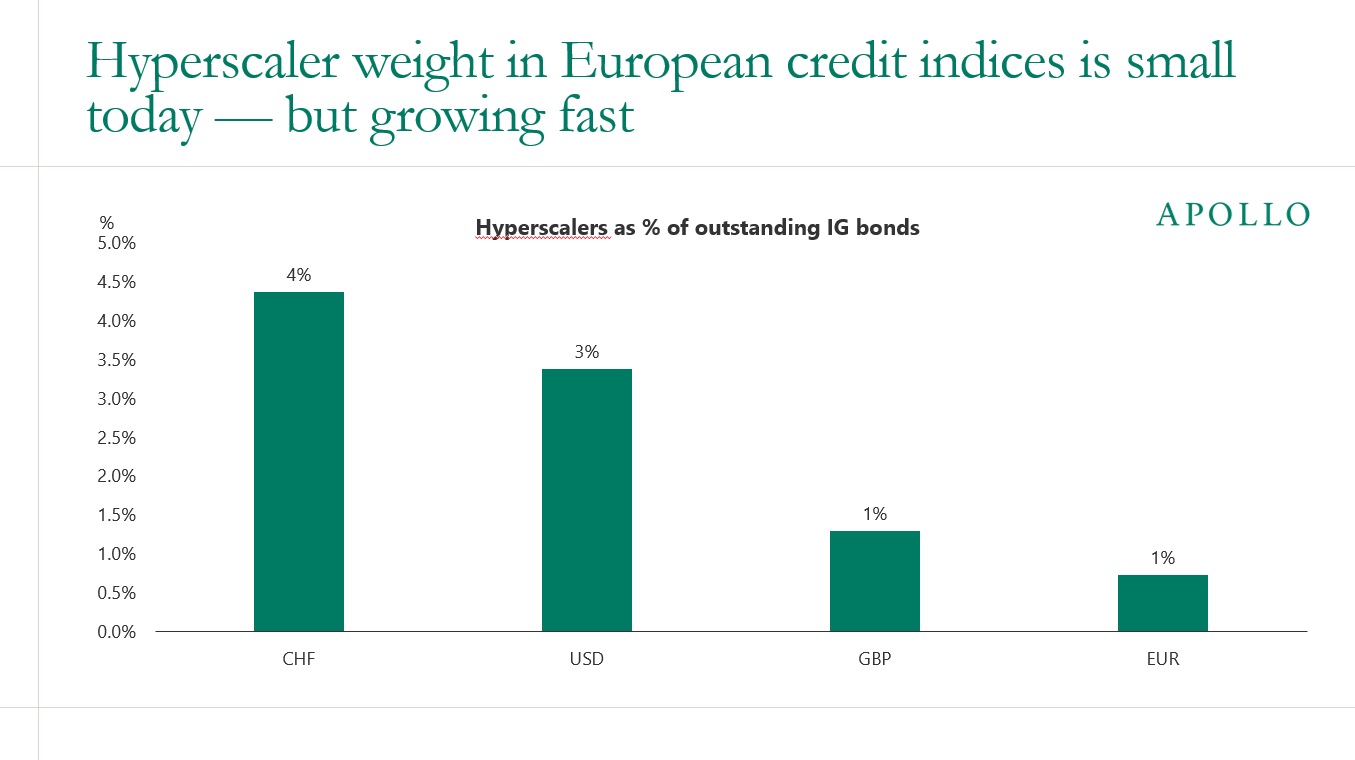
Hyperscalers account for 7% of euro issuance with maturities of 10 years or more, compared with 3% across all maturities. They also account for 3% of the 10-year-plus euro IG index, compared with 1% of the overall index. This is adding some additional depth for longer-dated maturities, which has been thin outside of sovereign issuance, and what’s more, some governments (like the UK) have been shortening duration of bond issuance, see the second and third charts below.

The bottom line is that the scale of hyperscaler financing, which is forecast to rise a further 25% in 2027, will have an even bigger impact on European bond markets, with hyperscalers becoming a larger part of European credit indices. The scale also calls for tapping all markets, public and private.

Written by Huw van Steenis

Download high-res charts

See important disclaimers at the bottom of the page.

Financial Markets & Risk Dynamics

October 06, 2026

Are Rates Peaking Within the Next Month?

Share

Several forces suggest rates may peak within the next month:

  1. Approaching midterm elections raise the odds of a Middle East deal that would lower oil prices.
  2. Governments in the US and Europe are adding oil supply to bring prices down before voters go to the polls.
  3. Higher rates are biting harder and harder on the interest-rate-sensitive parts of the economy, in particular housing and autos.
  4. More questions are being raised about the AI buildout, as seen in the ongoing widening of CDS spreads for AI-related companies.

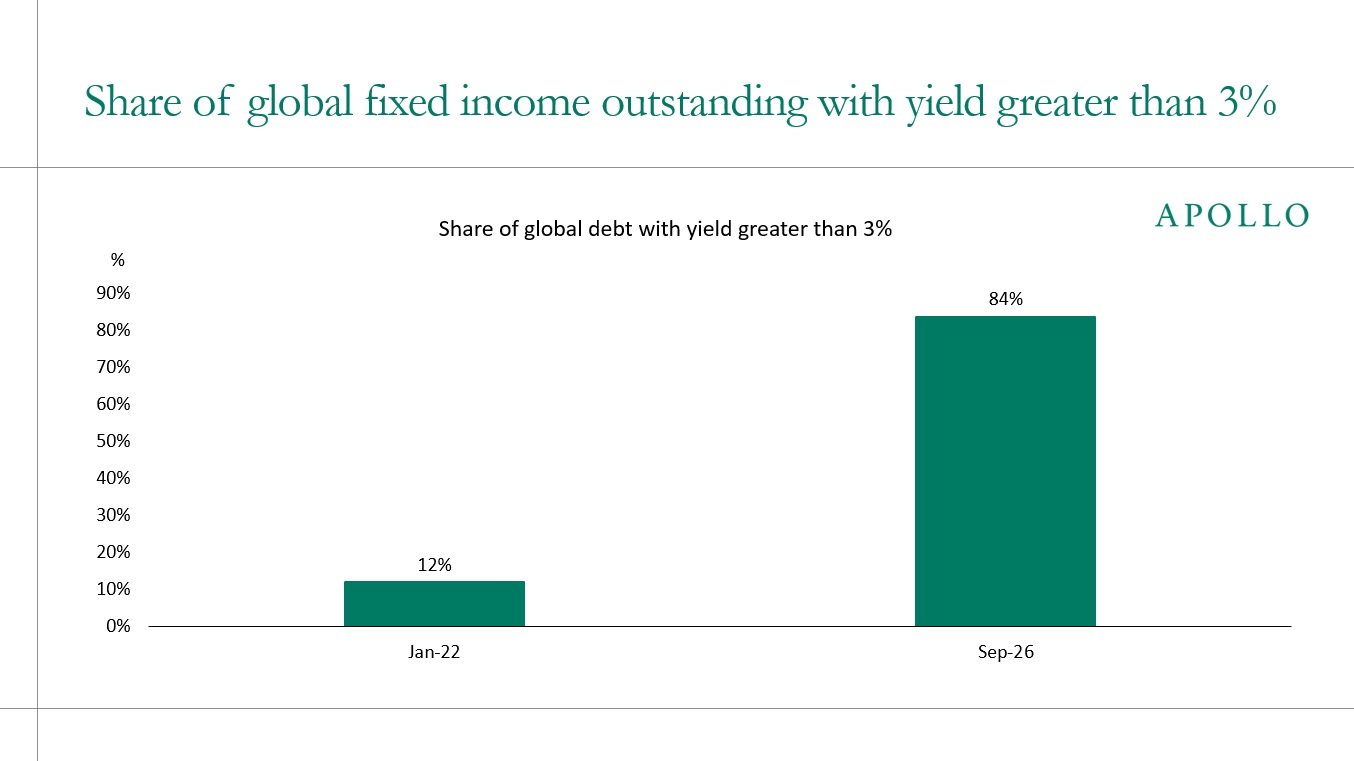
With 84% of global fixed income now yielding more than 3%, up from just 12% in January 2022, a deal or government action that lowers oil prices would ease the upward pressure on interest rates at a time when yields are already elevated across nearly the entire global bond market.

Download high-res chart

See important disclaimers at the bottom of the page.

Macroeconomic Indicators & Trends

October 05, 2026

No Signs of AI in the Productivity Data

Share

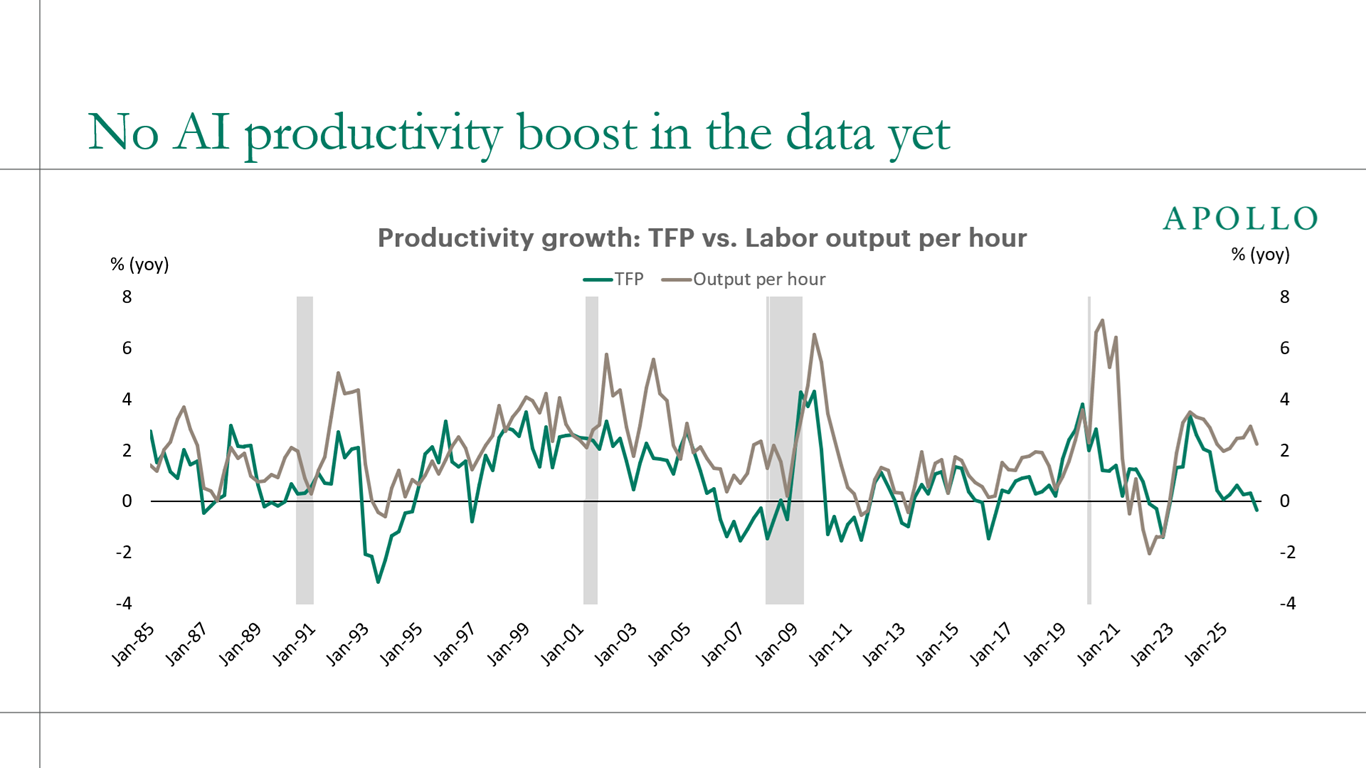
Total factor productivity (TFP) measures how much output the economy produces from a given quantity of labor and capital. It is what remains of growth after accounting for more hours worked and more machines installed. When firms produce more without adding inputs, TFP rises. For that reason it is the closest available proxy for technological progress and for genuine improvements in how inputs are combined.

Labor productivity, or output per hour, is a different concept. It can rise for three reasons: workers are given more or better equipment (capital deepening), the composition of the workforce shifts toward higher-skilled labor or TFP improves. Only the third reflects true innovation. Giving every employee a second monitor lifts output per hour without making the firm any smarter about how it operates.

That distinction is central to the AI debate. Hundreds of billions of dollars are flowing into data centers, chips and model training, and that capital deepening should mechanically lift output per hour. The harder question is whether AI is also raising TFP, meaning whether it is making the economy fundamentally more efficient.

So far, the data says no. The chart below shows utilization-adjusted TFP from the San Francisco Fed, and it is currently sitting slightly below zero with no sign of acceleration since the AI capex cycle began. Output per hour, by contrast, is running near 2.5%, comfortably above its post-2005 average, and that strength is exactly what gets cited as evidence that AI is already working. But strong output per hour alongside flat TFP is the signature of capital deepening, not of a technology shock.

TFP has swung between roughly -3% and +4% over the past 40 years with no discernible trend, so the current sub-zero reading is not in itself unusual. Electricity and IT both took a decade or more to show up in aggregate numbers.

The bottom line is that the AI boom is clearly visible in investment data and in equity valuations, but it is not yet visible in the productivity statistics, which means the productivity payoff from AI remains a forecast rather than an observation.

Download high-res chart

See important disclaimers at the bottom of the page.

Macroeconomic Indicators & Trends

October 04, 2026

The "Higher Rates, Higher Rent Doom Loop" Is a Big Problem for the Fed

Share

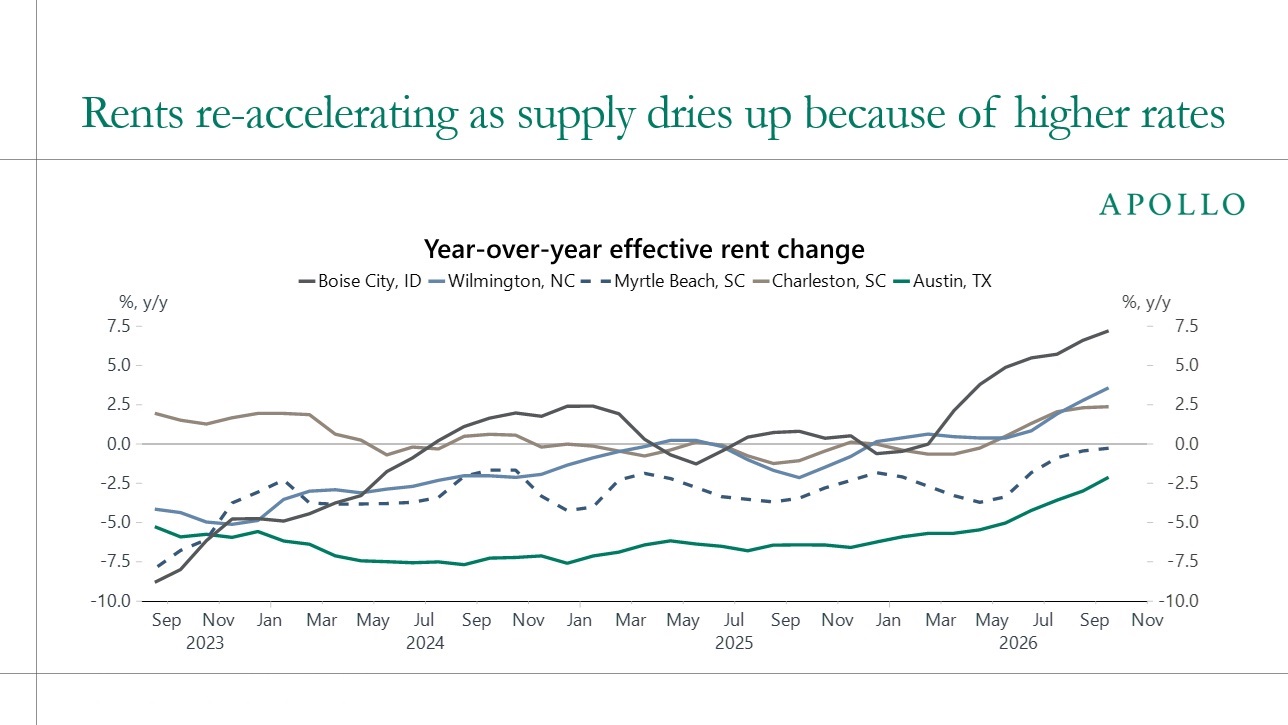
When rates are high, builders build less, and when fewer homes and apartments get built, rents go up, which pushes inflation higher and keeps rates high.

Call this the "higher rates, higher rent doom loop."

With owners' equivalent rent alone making up roughly a quarter of the CPI basket, this re-acceleration in rents is a problem for the Fed because it puts upward pressure on inflation driven by higher rates.

Download high-res chart

See important disclaimers at the bottom of the page.

Macroeconomic Indicators & Trends

October 03, 2026

Robots Are Not Coming for Your Job

Share

This new paper from Anthropic finds that robots will only be able to replace 300,000 jobs in the US economy. For comparison, total employment in the US economy is 160 million. Even under aggressive projections, widespread displacement of physical labor will take decades, and historical cost decline rates suggest it would take 40 years to reach cost parity for even 10% of jobs.

Consider nursing and general repair, where present-day robots can do almost none of the work, or the electrician threading cable through a finished wall and the home health aide lifting a frail patient, tasks that look routine to an outsider and remain close to untouchable in practice.

In fact, much of the automation that will arrive this decade has nothing to do with large language models. Car washes that scan vehicles to aim their sprayers, warehouse sortation lines and autonomous vehicles all descend from sensing and control work that was well underway before large language models arrived and would almost certainly have happened anyway.

The bottom line is that the hardest physical work is harder to automate than the consensus assumes, and the automation we do get will owe more to decades of mechanical engineering than to the current moment in AI. Almost all jobs are bundles of simple and complicated tasks, so robots that can handle the simple part still cannot do the job, which is why, for the vast majority of workers, the mess is the moat.

For investors, the conclusion is that job losses in the economy will be modest, held back by cost, by the fine manipulation robots cannot manage, by regulation and by a simple human preference for human hands.

Displacement of workers is also only one side of the ledger. US business formation stands at the highest level in the nation's history, new firms are where new jobs come from and the net effect on employment is likely to be positive by a wide margin.

The conclusion is that robots are not coming for your job, because very few jobs are a single automatable task. In other words, your job is a mess.

See important disclaimers at the bottom of the page.

Macroeconomic Indicators & Trends

October 02, 2026

Why Weak Payrolls Are No Longer Weak

Share

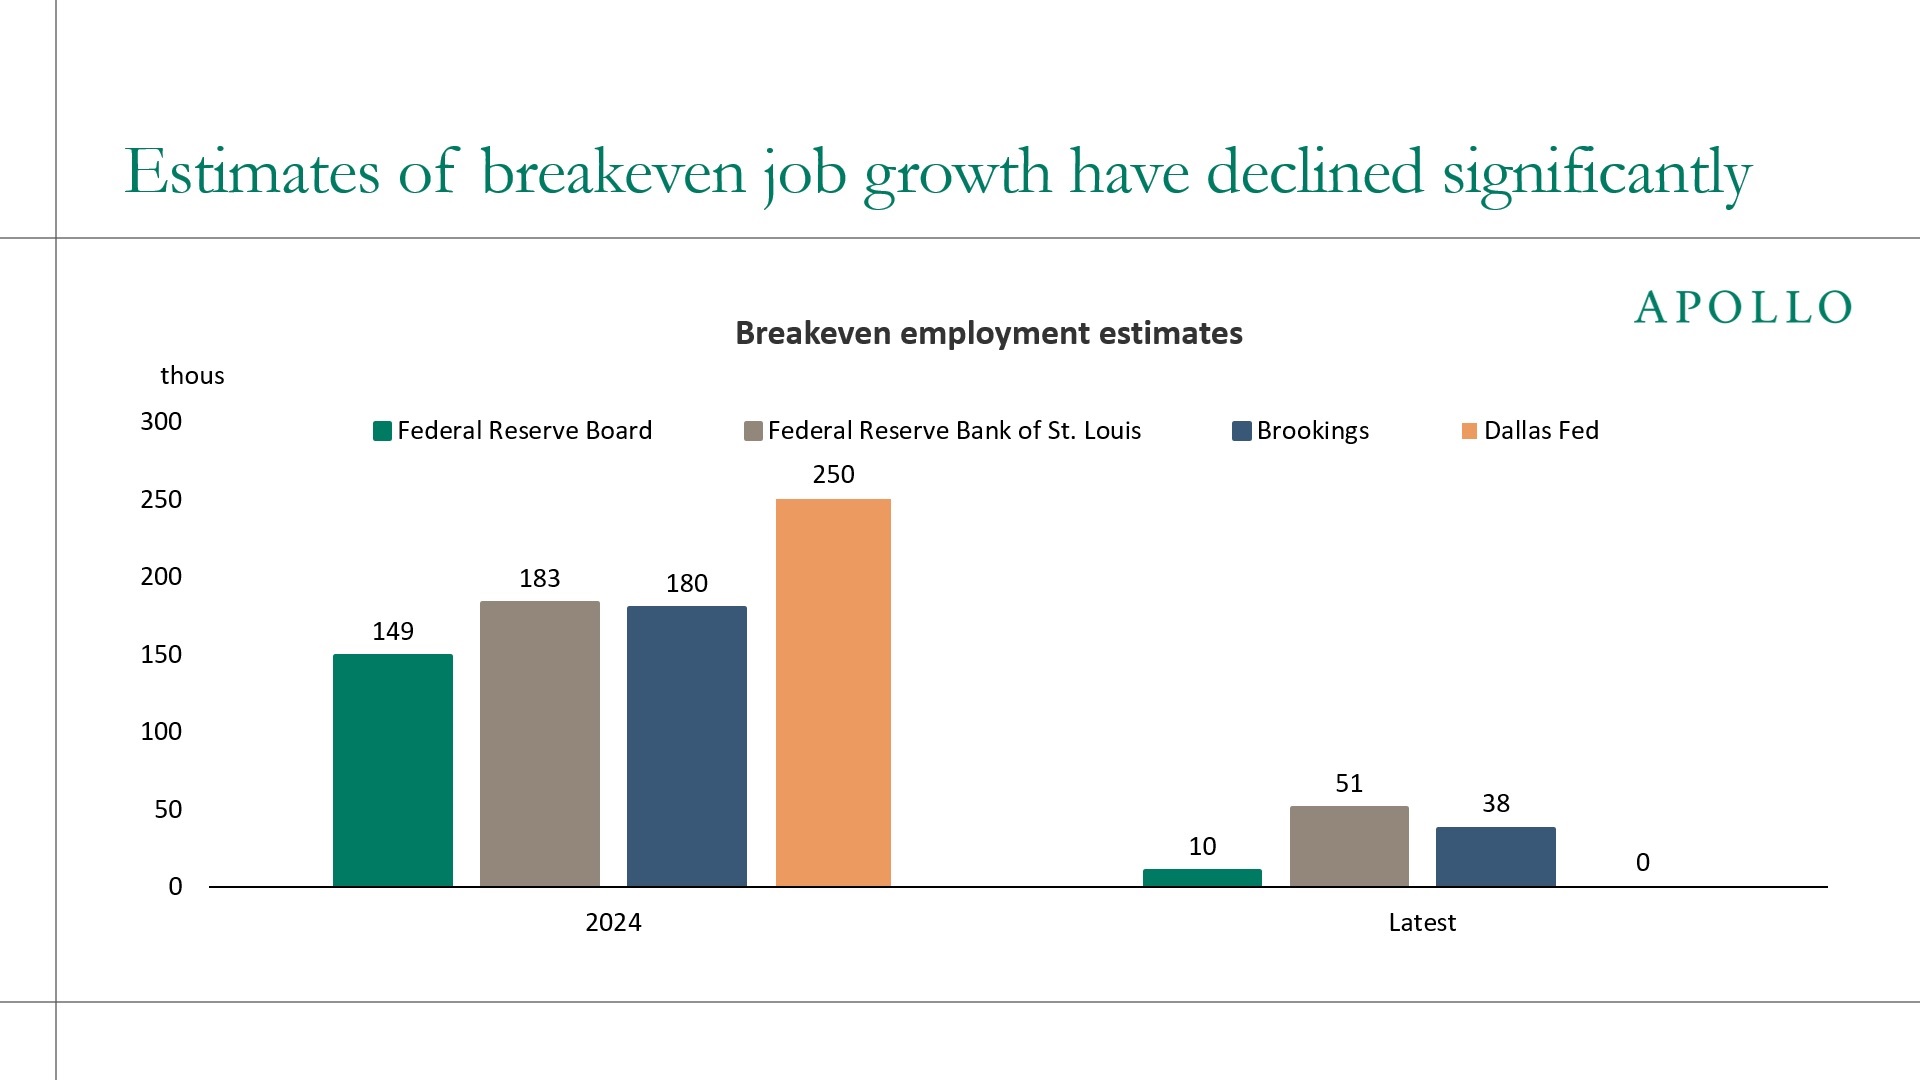
Breakeven job growth has collapsed from 200,000 per month to close to zero today, driven by a sharp drop in immigration shrinking labor force growth and continued baby boomer retirements pulling down participation. That means the consensus expectation of 90,000 jobs created in September is not a soft print but a solid one, comfortably above breakeven and consistent with a strong economy and a falling unemployment rate.

The bottom line is that with a strong labor market and inflation still significantly above the Fed's 2% target, rates will continue to stay higher for longer.

Download high-res chart

See important disclaimers at the bottom of the page.

Macroeconomic Indicators & Trends

October 01, 2026

Everyone Is Talking About AI

Share

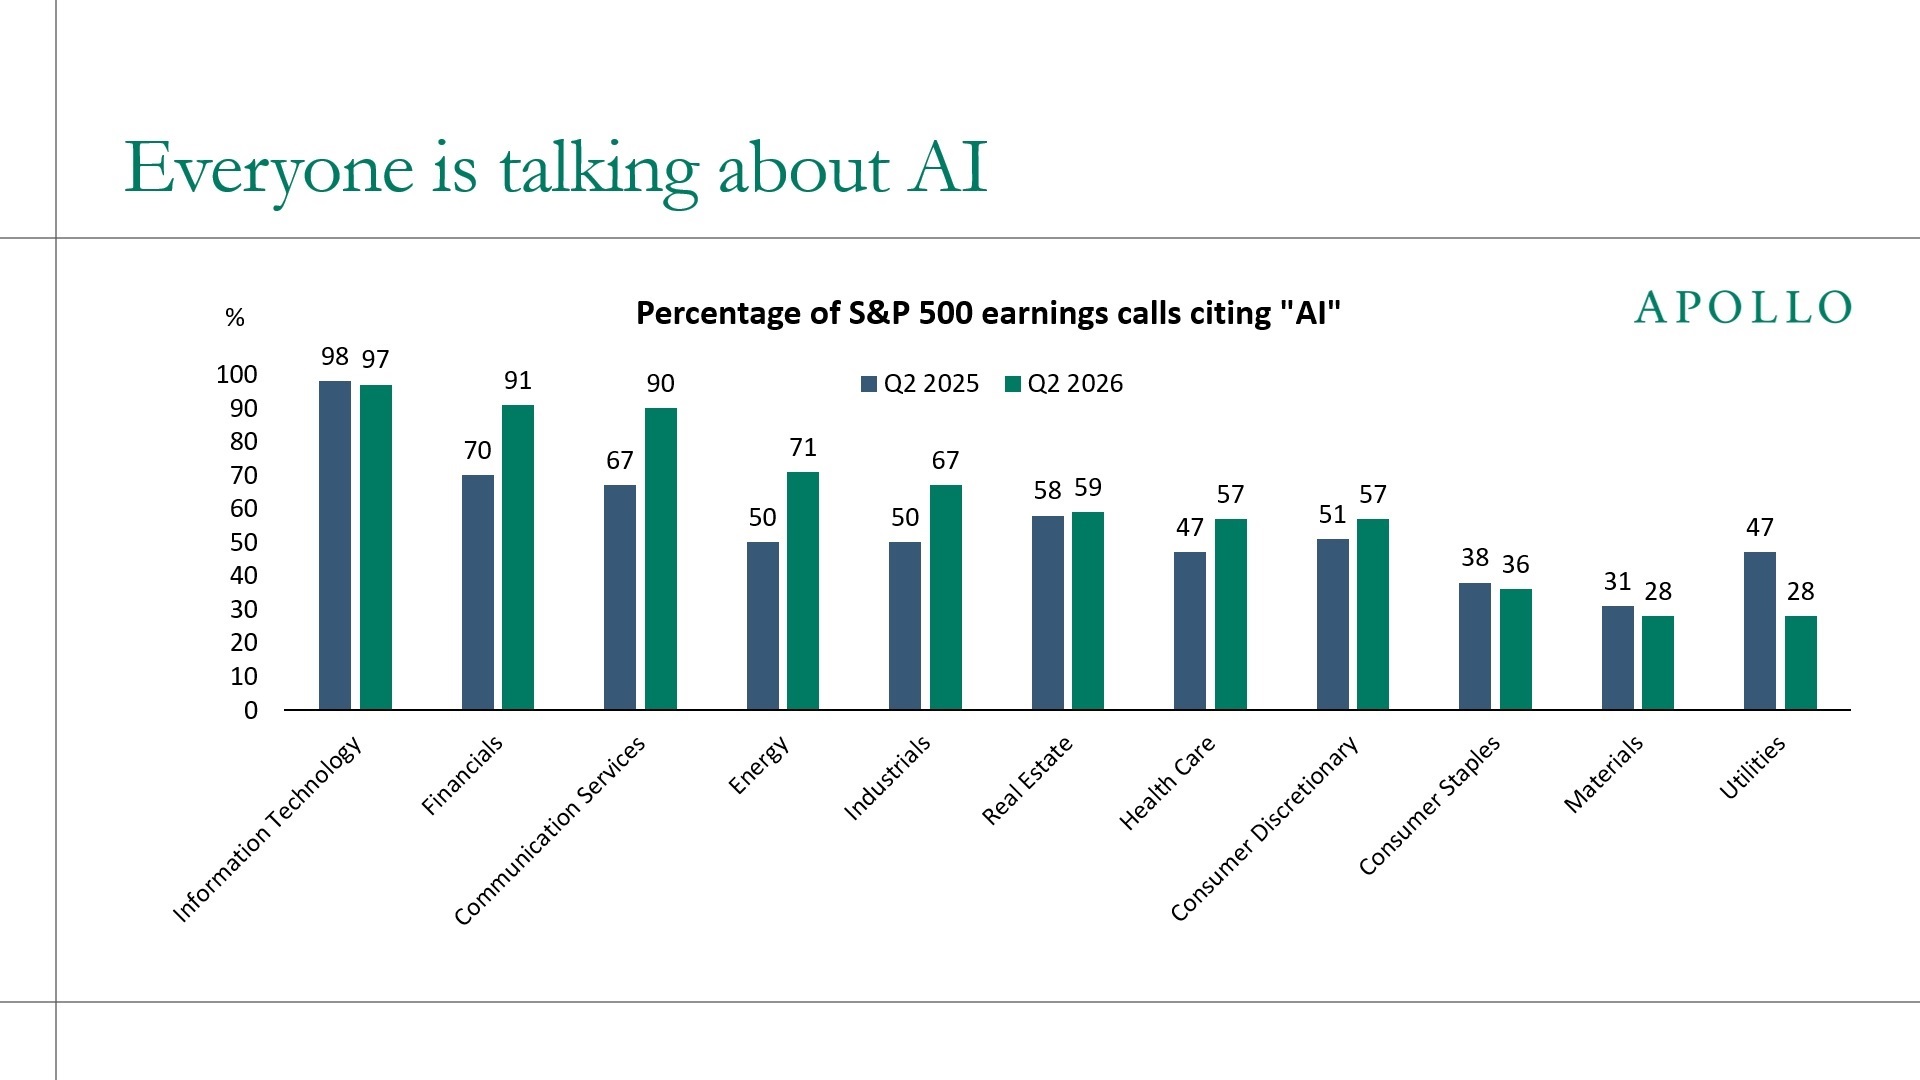
Everyone is talking about AI on earnings calls, see chart below.

That could mean companies are truly adopting it, are hyping it for investors or are planning to use it to cut costs and jobs.

The key question is whether all this talk about AI turns into real spending and measurable productivity gains.

The bottom line is that universal buzz around AI may be a sign that the hype has moved faster than the payoff.

Download high-res chart

See important disclaimers at the bottom of the page.

This presentation may not be distributed, transmitted or otherwise communicated to others in whole or in part without the express consent of Apollo Global Management, Inc. (together with its subsidiaries, “Apollo”).

Apollo makes no representation or warranty, expressed or implied, with respect to the accuracy, reasonableness, or completeness of any of the statements made during this presentation, including, but not limited to, statements obtained from third parties. Opinions, estimates and projections constitute the current judgment of the speaker as of the date indicated. They do not necessarily reflect the views and opinions of Apollo and are subject to change at any time without notice. Apollo does not have any responsibility to update this presentation to account for such changes. There can be no assurance that any trends discussed during this presentation will continue.

Statements made throughout this presentation are not intended to provide, and should not be relied upon for, accounting, legal or tax advice and do not constitute an investment recommendation or investment advice. Investors should make an independent investigation of the information discussed during this presentation, including consulting their tax, legal, accounting or other advisors about such information. Apollo does not act for you and is not responsible for providing you with the protections afforded to its clients. This presentation does not constitute an offer to sell, or the solicitation of an offer to buy, any security, product or service, including interest in any investment product or fund or account managed or advised by Apollo.

Certain statements made throughout this presentation may be “forward-looking” in nature. Due to various risks and uncertainties, actual events or results may differ materially from those reflected or contemplated in such forward-looking information. As such, undue reliance should not be placed on such statements. Forward-looking statements may be identified by the use of terminology including, but not limited to, “may”, “will”, “should”, “expect”, “anticipate”, “target”, “project”, “estimate”, “intend”, “continue” or “believe” or the negatives thereof or other variations thereon or comparable terminology.