Marc Rowan on how Apollo’s differentiated strategy was built for this moment.
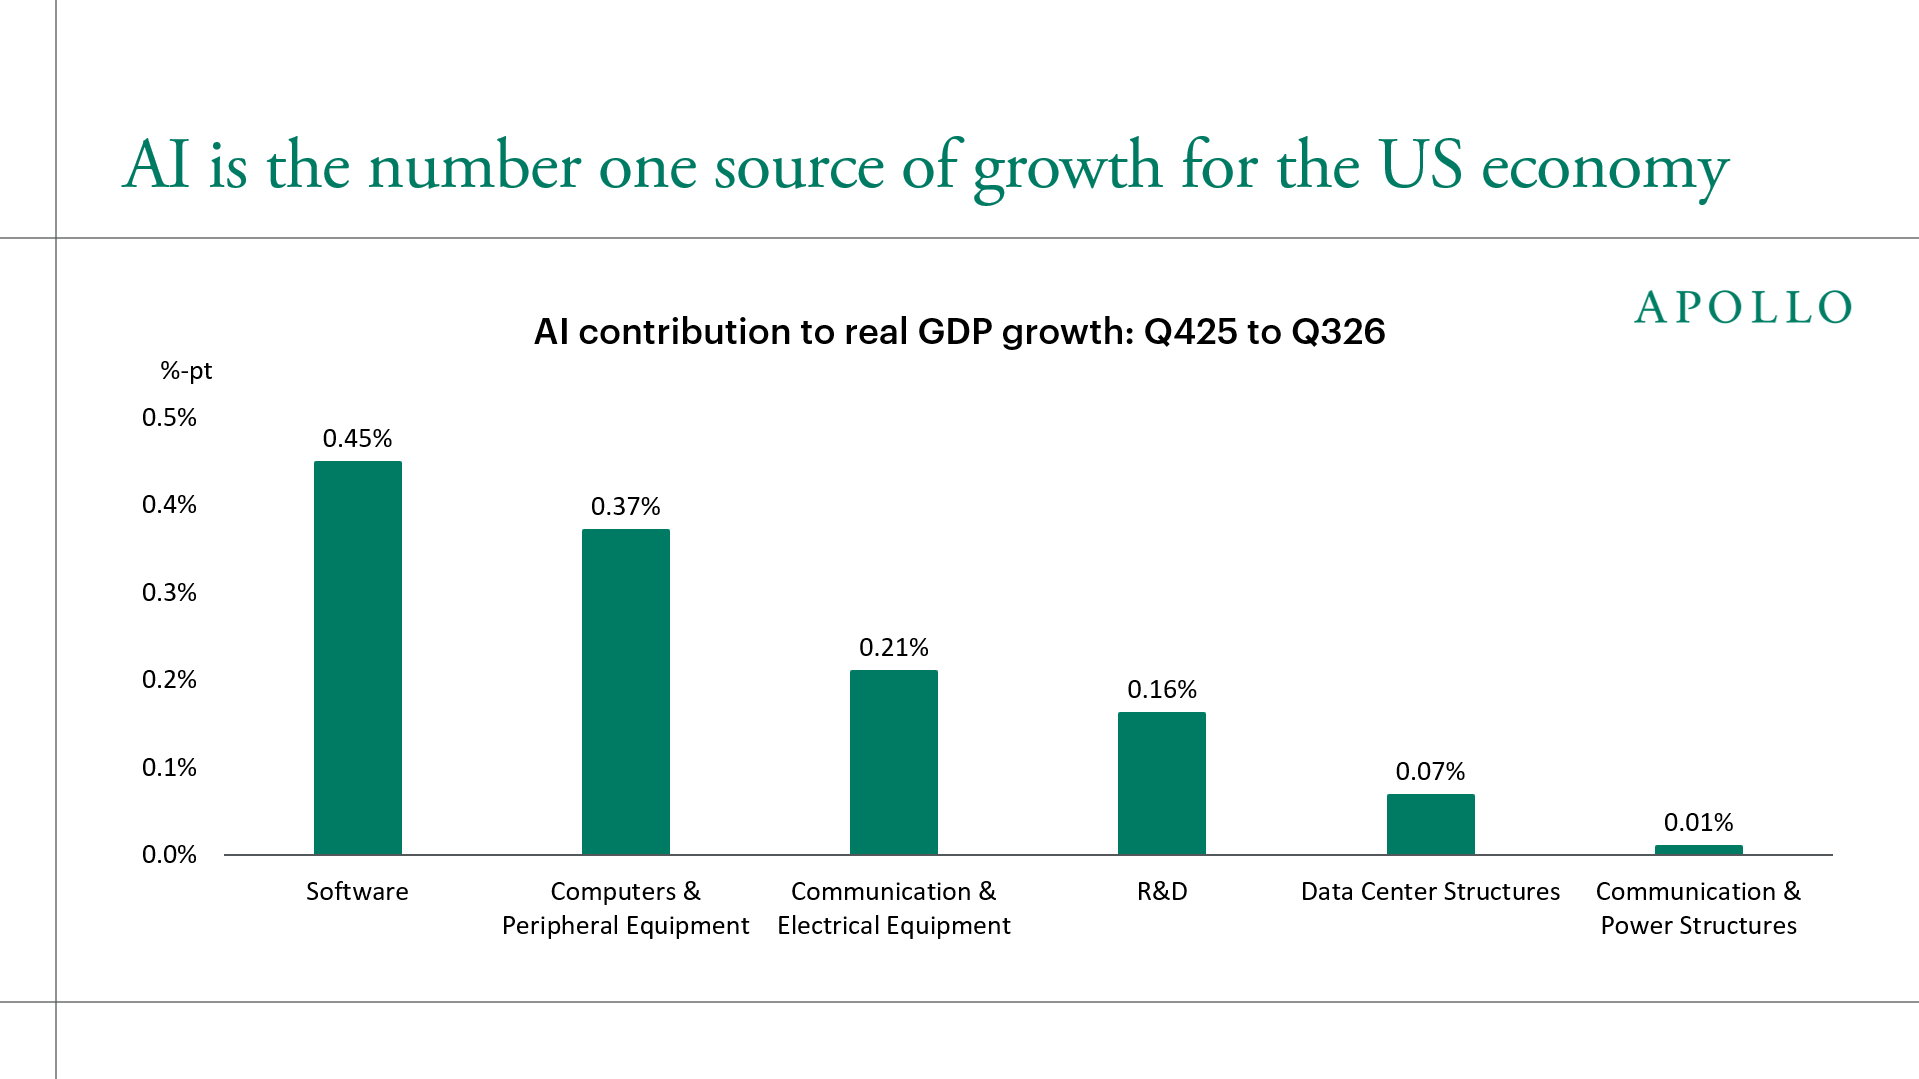
AI investment added roughly 1.3 percentage points to real GDP growth over the last three quarters, or about 65% of the roughly 2% cumulative growth, led by software and computers, see chart below. These are gross figures that do not net out imports, so the net boost in the national accounts is likely somewhat smaller.
The bottom line is that AI is the number one source of growth for the US economy, and anyone making statements about the 2027 outlook for equity and credit markets is implicitly making assumptions about the pace and magnitude of the AI data center buildout.
Sources: Haver Analytics, BEA, Apollo Chief Economist
See important disclaimers at the bottom of the page.
November 18, 2026
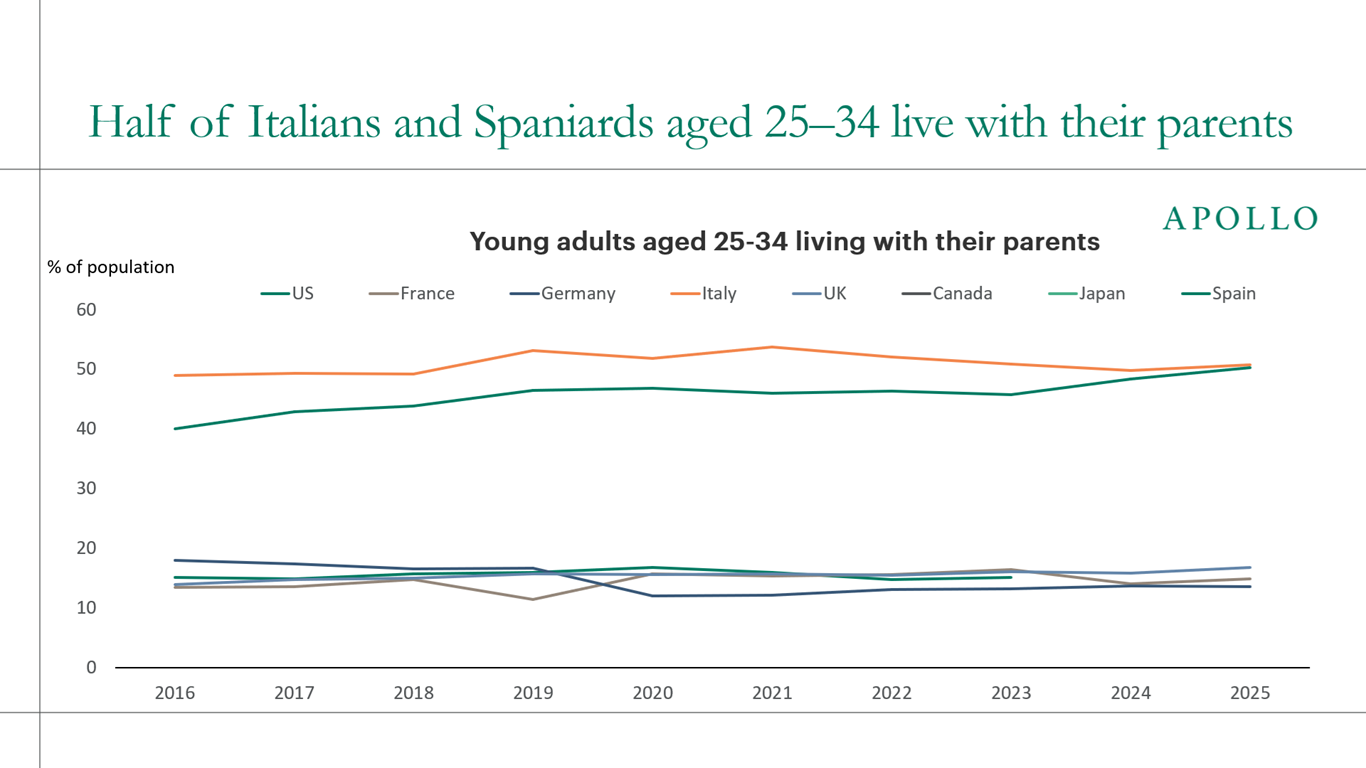
In Italy and Spain, half of 25-34-year-olds live with their parents. In the US, it’s about one in six, see chart below.
Note: Ages 25-34. Latest year 2025, except US (2023). Japan is census data. Definitions vary by country. Sources: Eurostat, US Census Bureau, ONS, Statistics Bureau of Japan, Macrobond, Apollo Chief Economist
See important disclaimers at the bottom of the page.
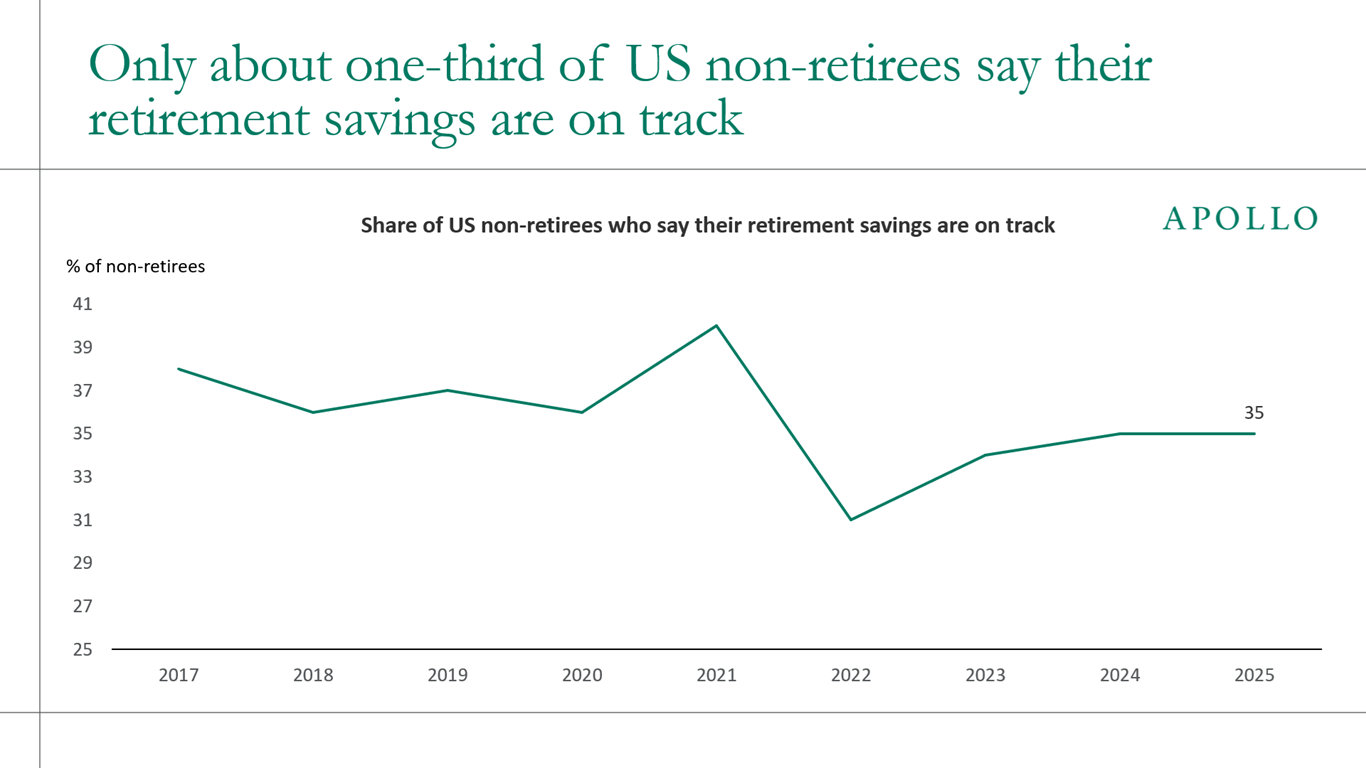
Nearly two-thirds of Americans aren’t confident their retirement savings are on track, see chart below. The bottom line is that more retirement savings are needed.
Note: Respondents self-assess whether their plan is “on track.” Sources: Federal Reserve Board, SHED, Apollo Chief Economist
See important disclaimers at the bottom of the page.
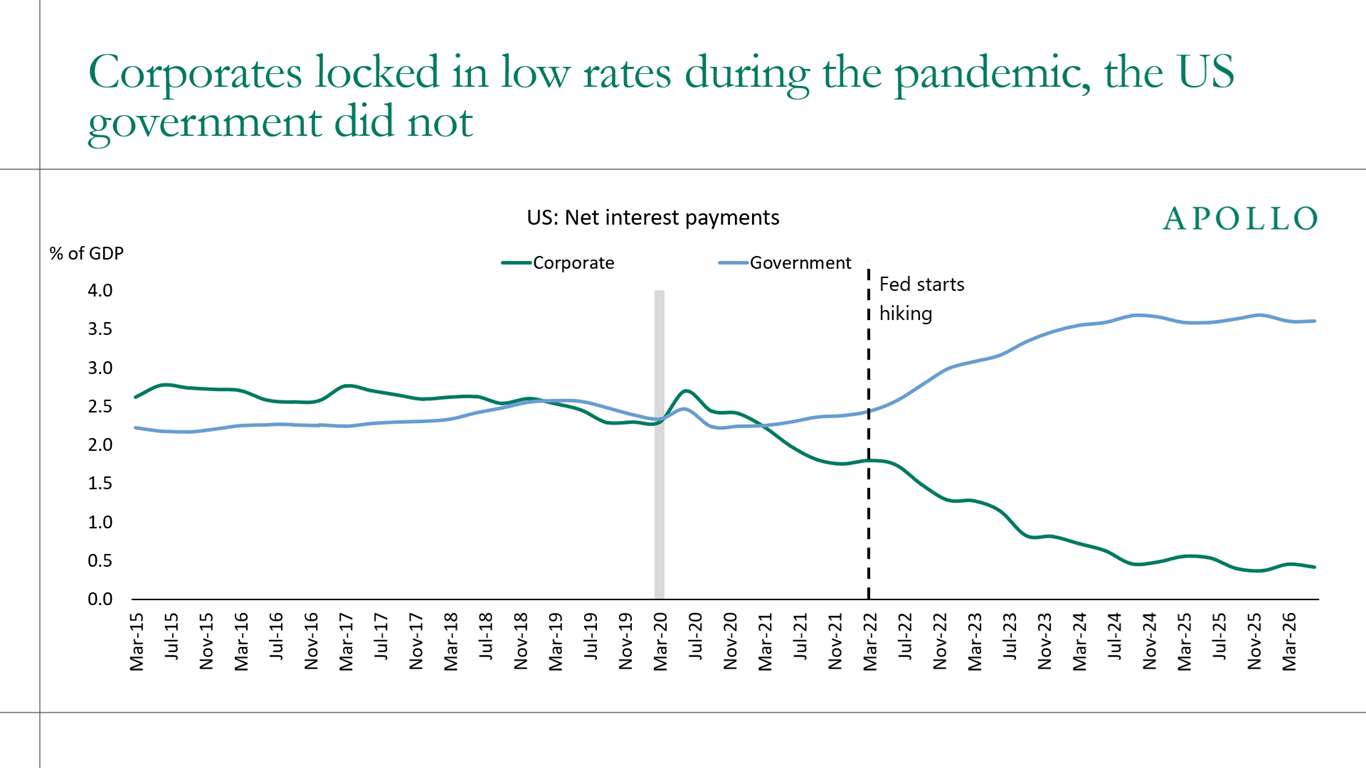
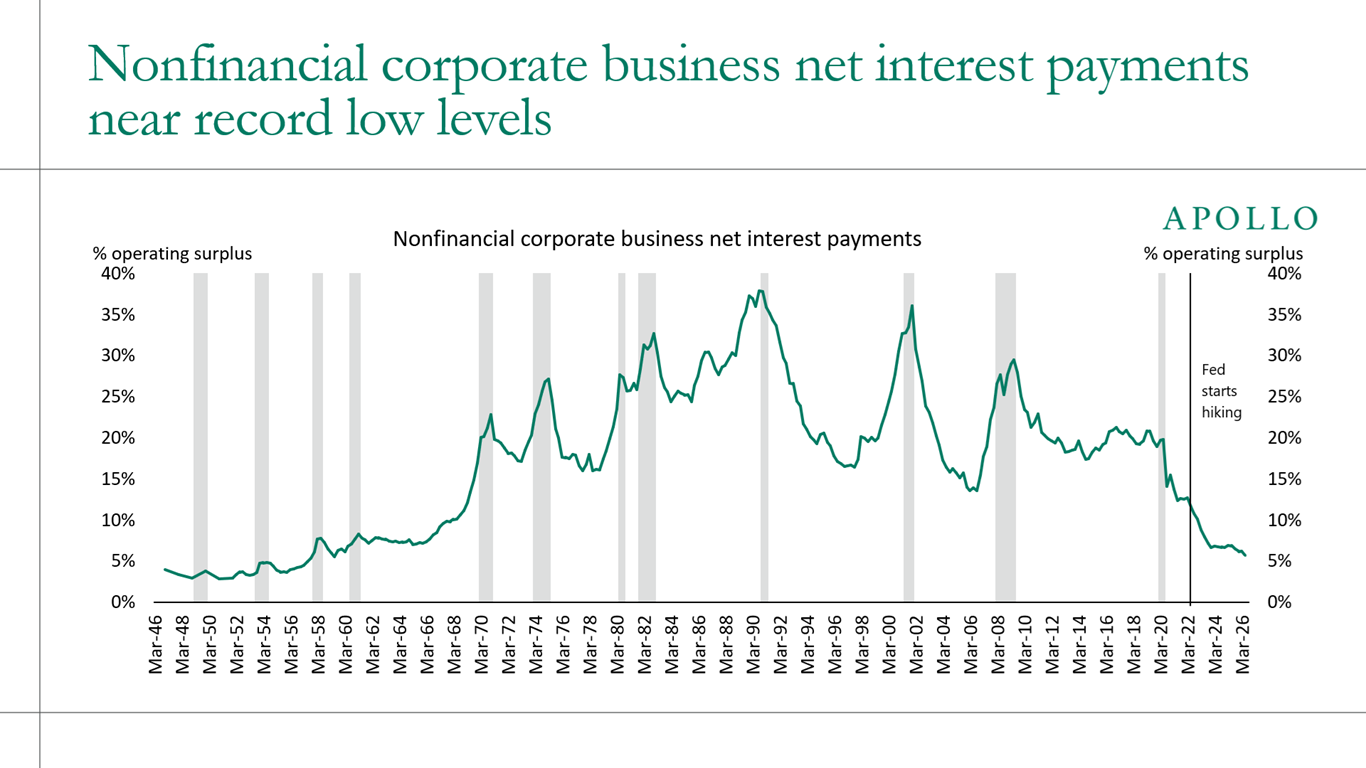
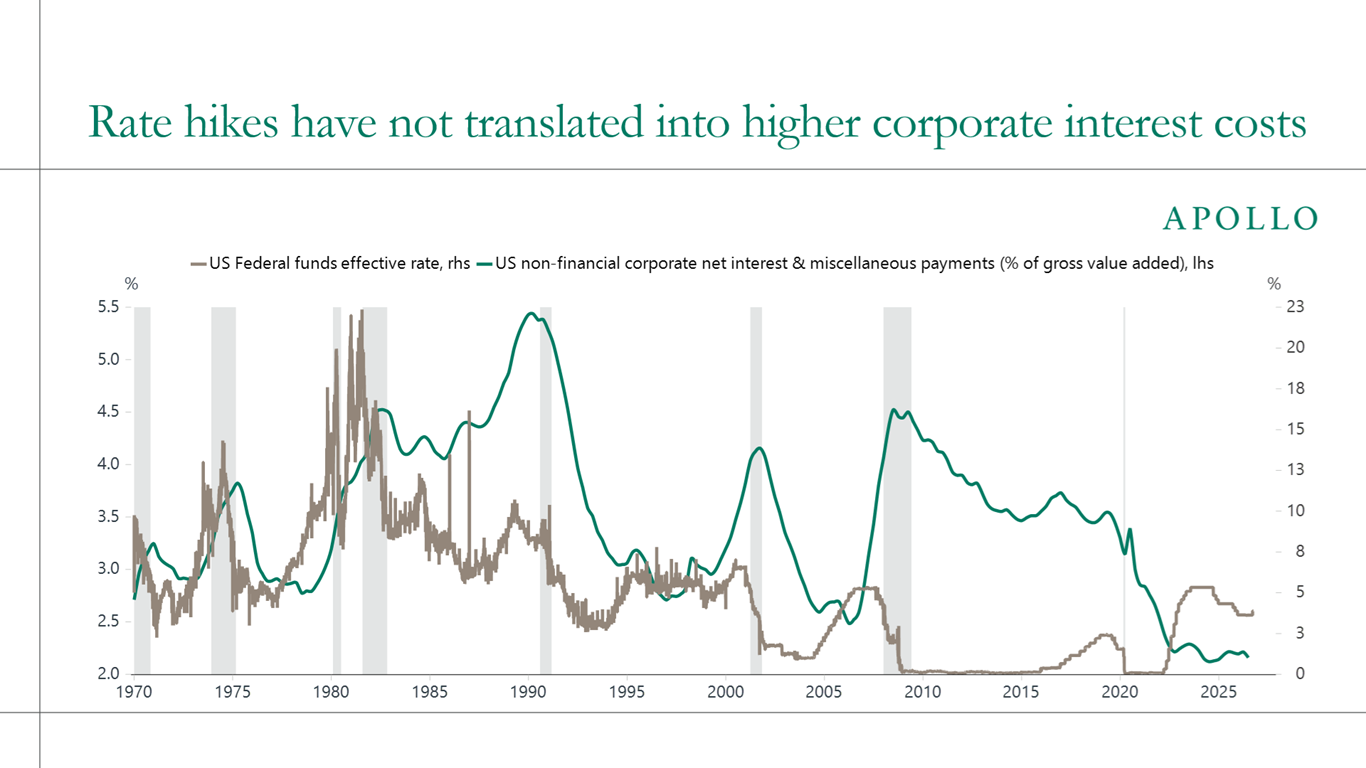
Corporate America and households both locked in low rates during the pandemic, with firms refinancing their debt and homeowners securing record-low mortgages.
Washington didn’t, and its interest bill has more than doubled from about $500 billion in summer 2020 to about $1.25 trillion today, so the economy is now far more sensitive to rates through the government than through the private sector, see charts below.
The bottom line is that the cost of higher rates has landed on the fiscal side rather than on companies and consumers, which is why the tightening cycle has done so little to slow the private economy.
Sources: BEA, Apollo Chief Economist
Sources: FRB, Haver Analytics, Apollo Chief Economist
Sources: Bloomberg, Macrobond, Apollo Chief Economist
See important disclaimers at the bottom of the page.
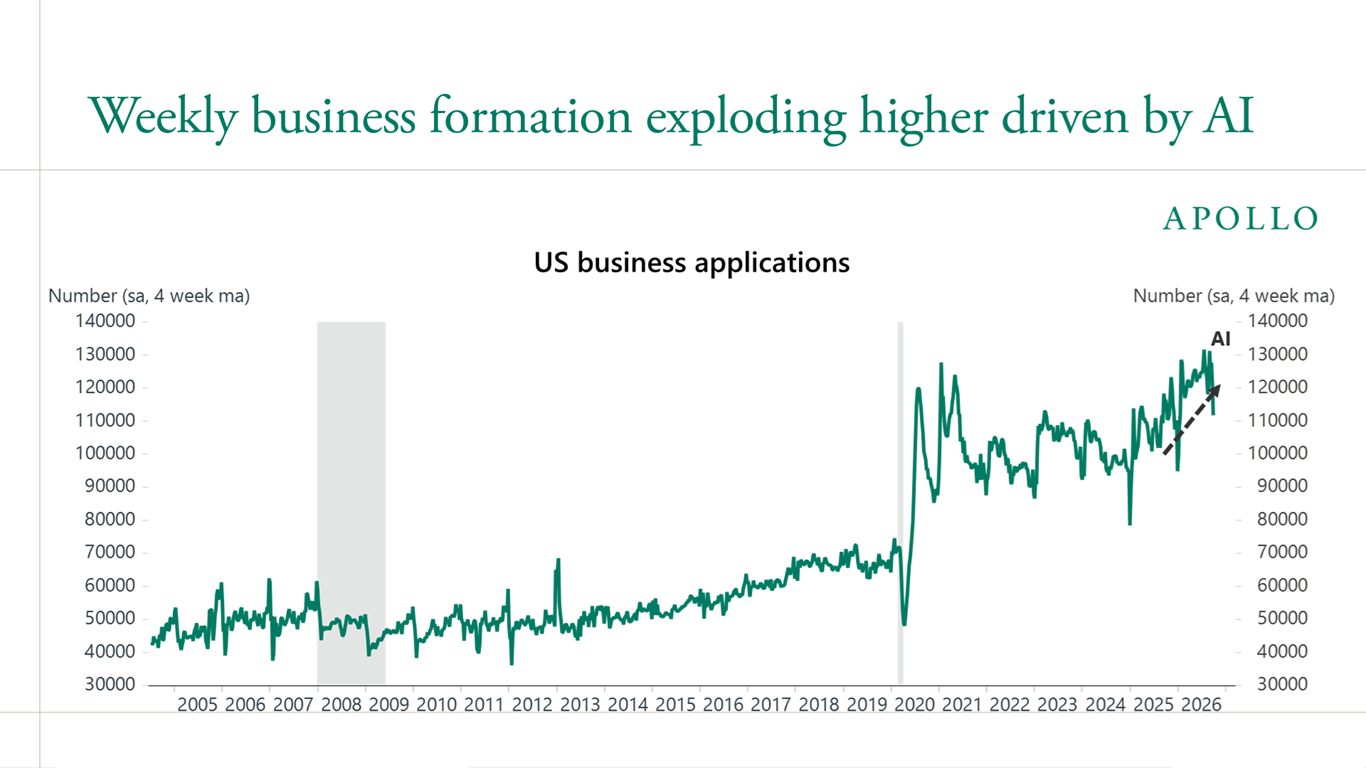
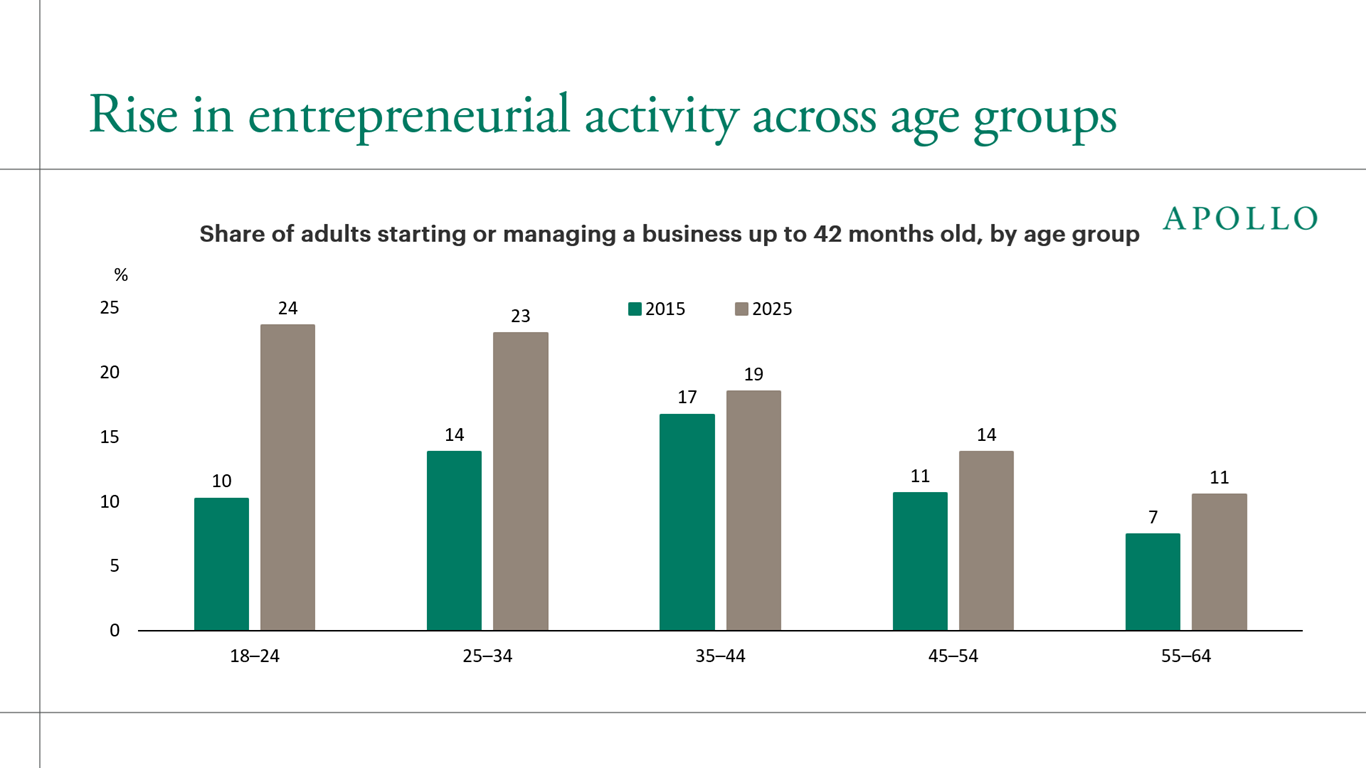
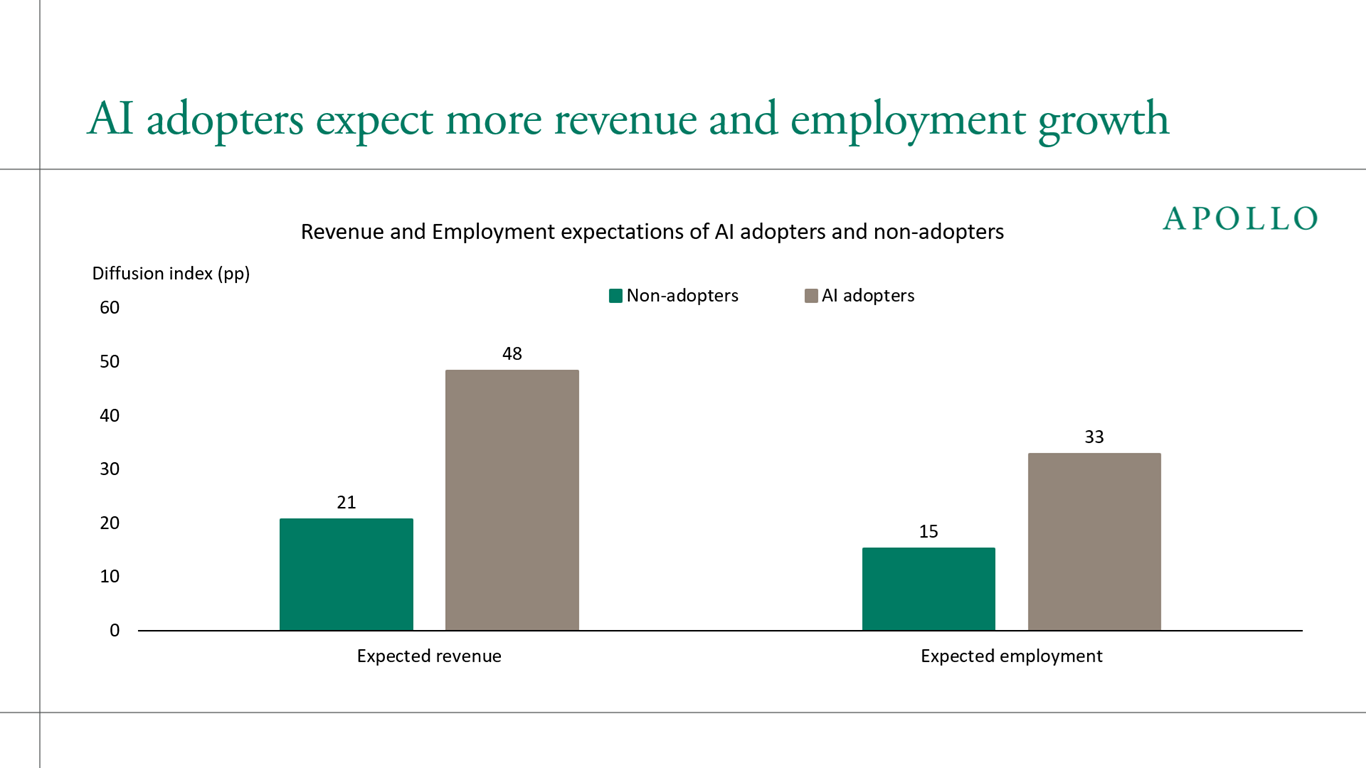
AI is making it much easier to start a business. Entrepreneurial activity continues to rise across all age groups, and AI adopters expect to see faster employment growth than non-adopters, see charts below.
The bottom line is that AI is making the economy more dynamic, and the job-creating effect of AI is far bigger than the labor displacement effect.
For more discussion of the net positive effect of AI on employment, see our previous Sparks:
Sources: US Census Bureau, Macrobond, Apollo Chief Economist
Sources: GEM Global Entrepreneurship Monitor, Apollo Chief Economist
Note: Diffusion Index = percent of firms expecting an increase minus percent expecting a decrease over the next 12 months. Sources: Federal Reserve Bank of New York, Apollo Chief Economist
See important disclaimers at the bottom of the page.
October nonfarm payrolls and CPI were strong, the AI spending boom continues and the Atlanta Fed estimates fourth-quarter GDP growth at 3.5%, significantly above the 2% potential growth rate.
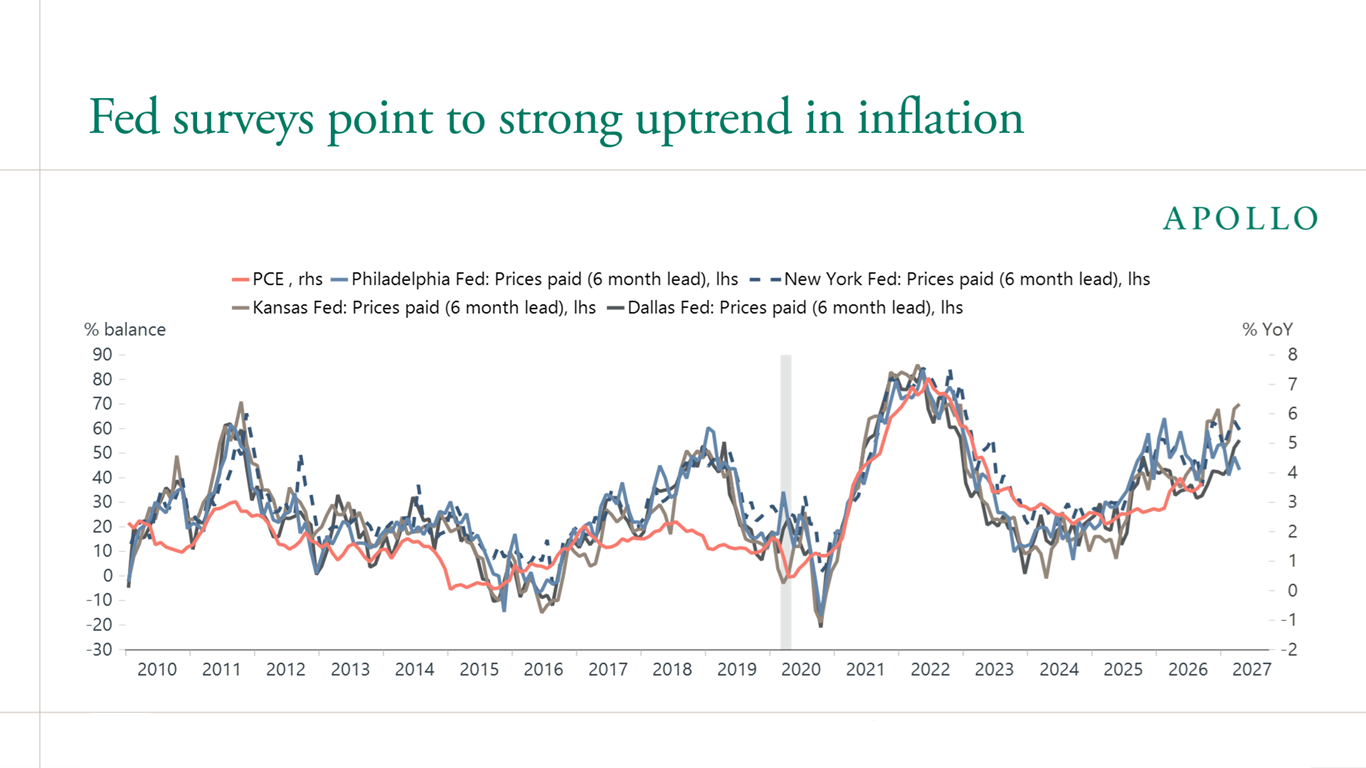
At the same time, regional Fed surveys of prices paid, shifted six months forward, point to a continued strong uptrend in inflation, with PCE inflation moving towards 6%, see chart below.
The bottom line is that strong demand, combined with ongoing supply shocks to imports, labor and energy, raises the risk that the Fed is falling behind the curve and will have to raise rates much more than markets currently expect.
For more discussion, see also our recent Spark here.
Sources: Federal Reserve Bank of Dallas, Federal Reserve Bank of Kansas City, Federal Reserve Bank of New York, Federal Reserve Bank of Philadelphia, US Bureau of Economic Analysis (BEA), Macrobond, Apollo Chief Economist
See important disclaimers at the bottom of the page.
November 13, 2026
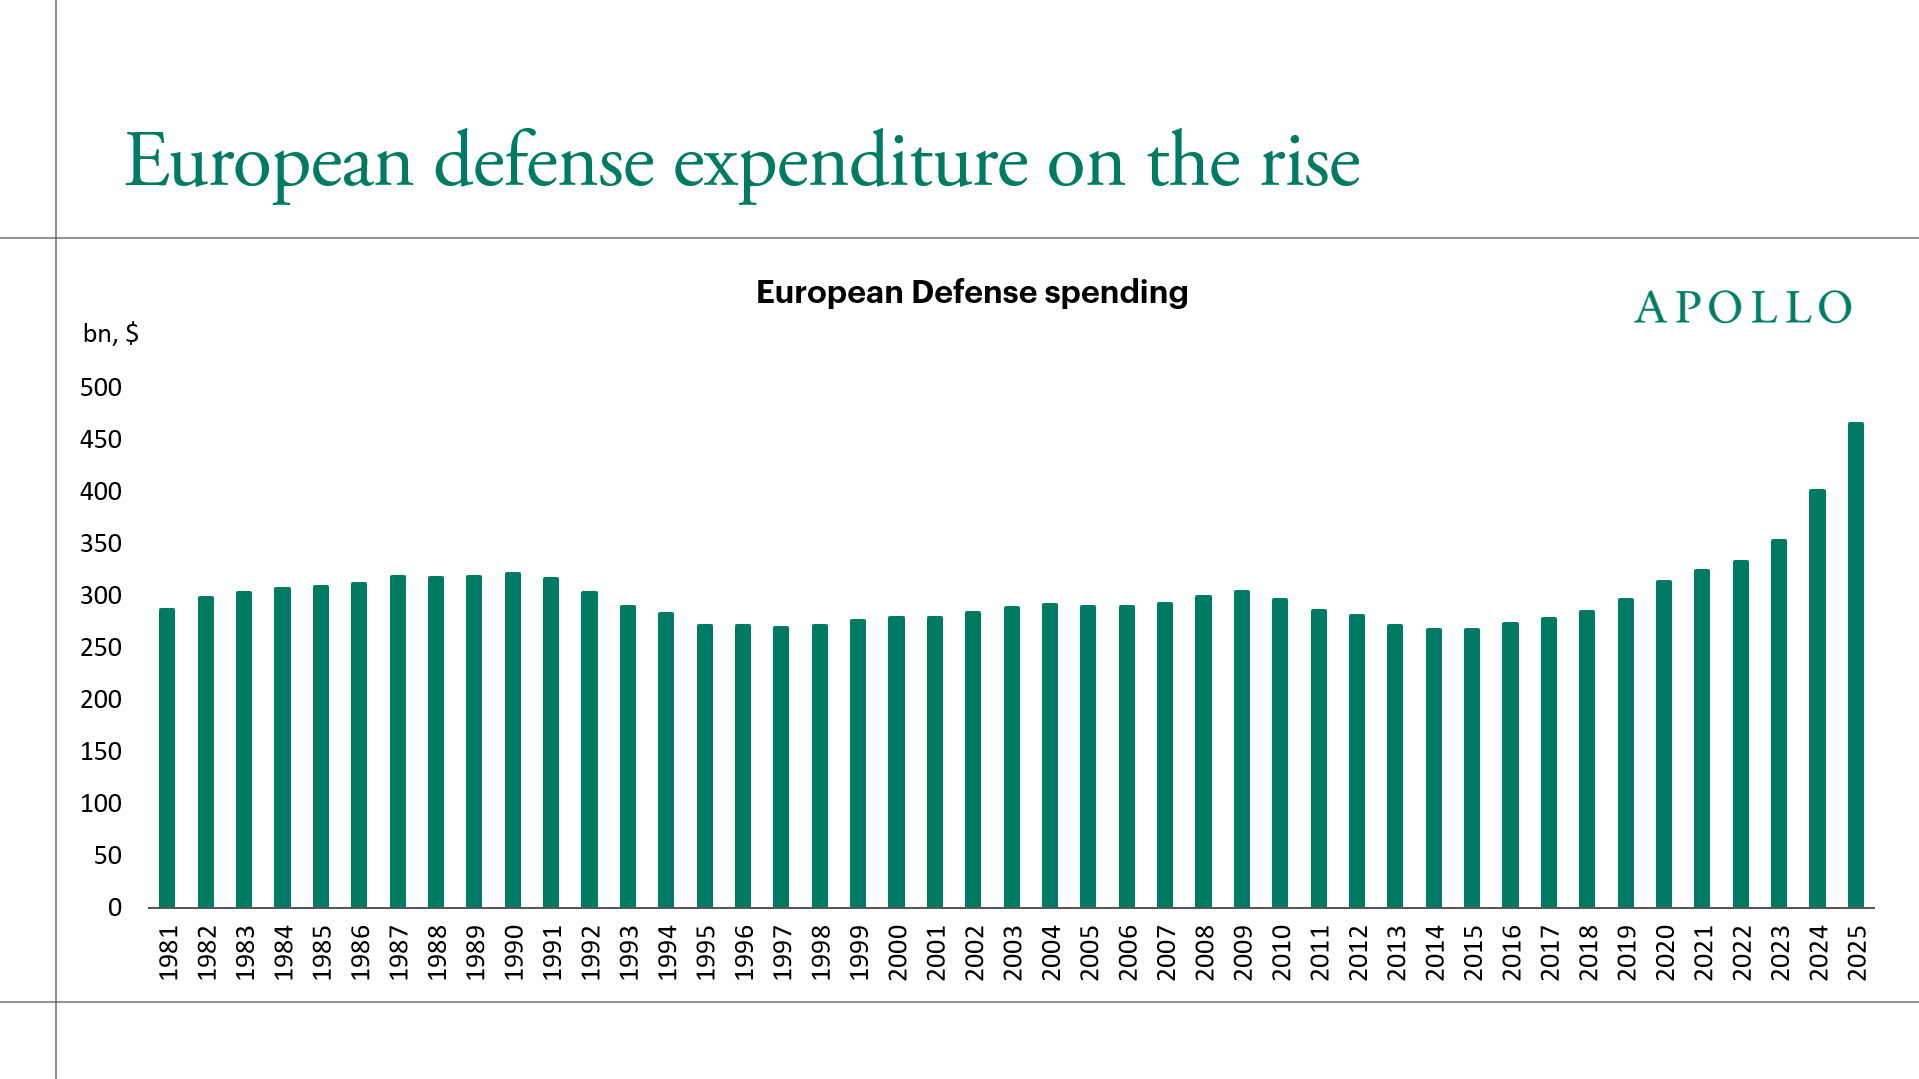
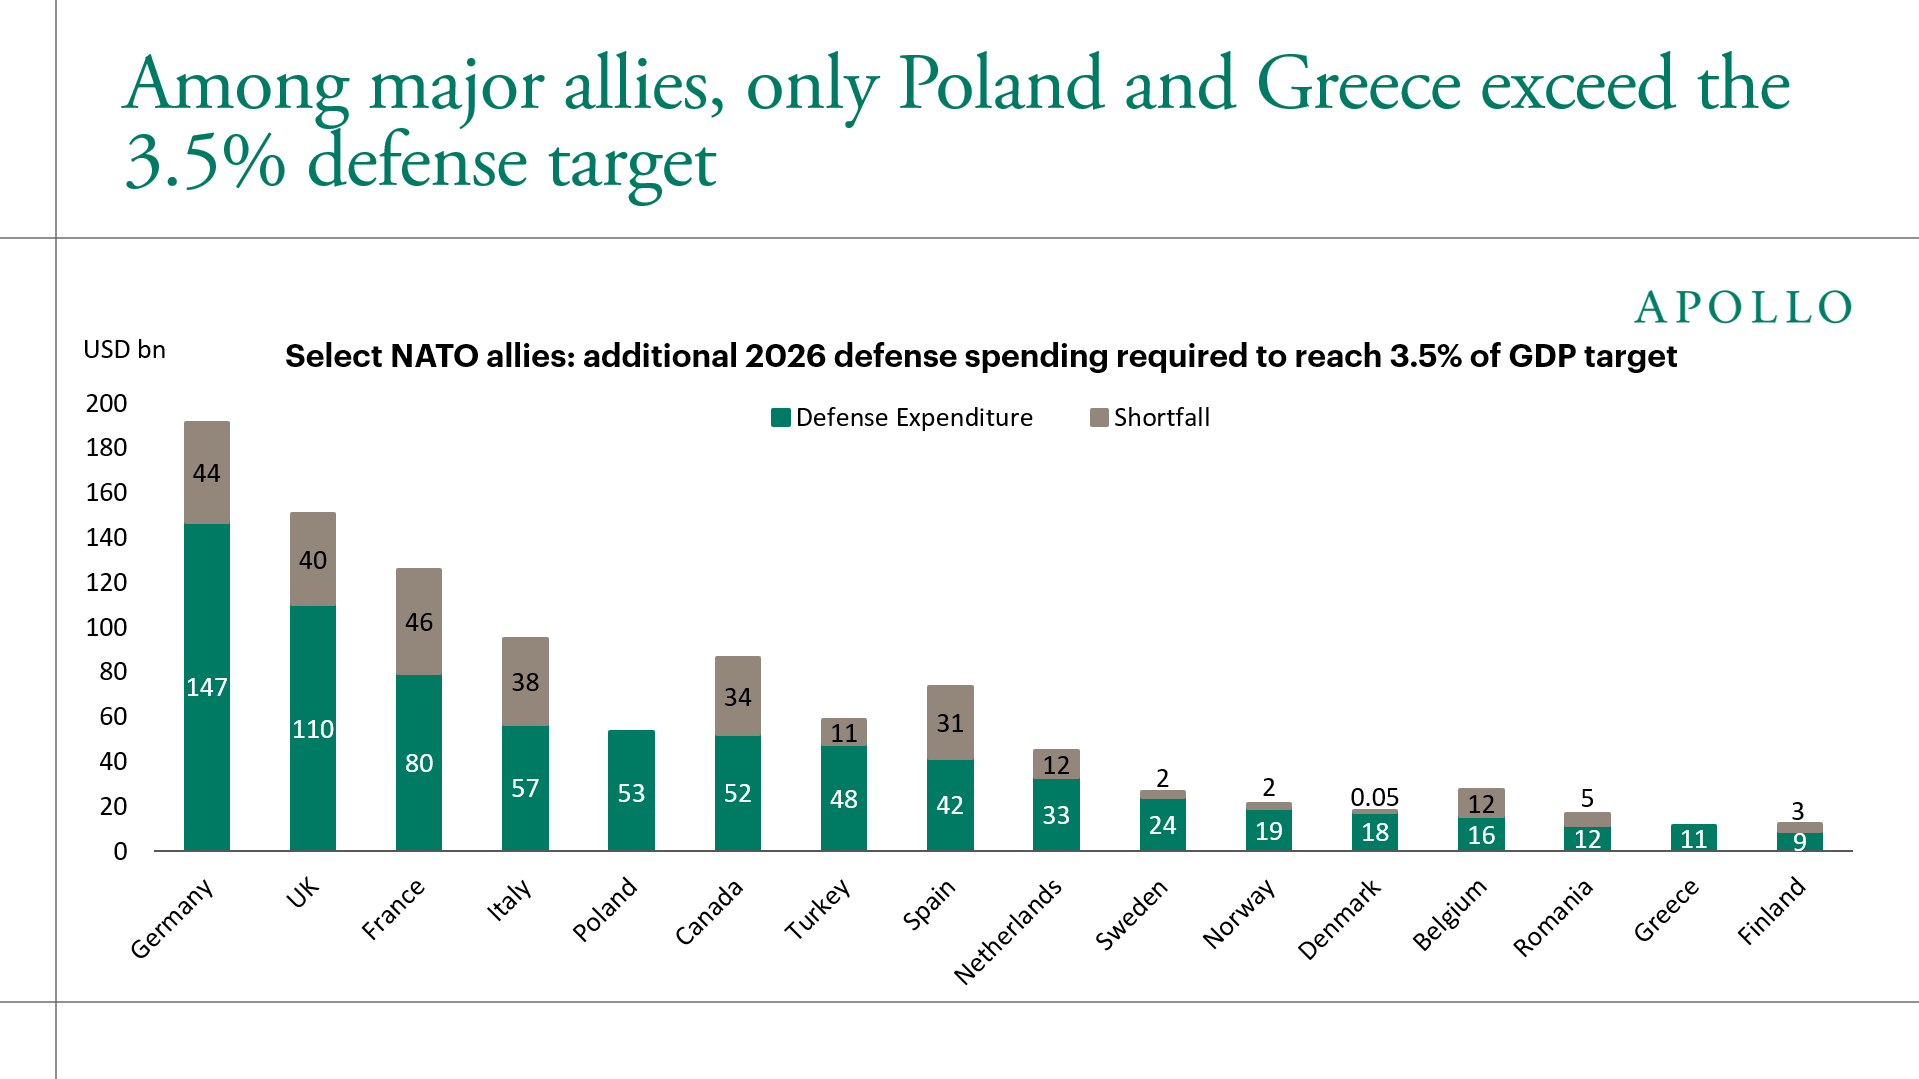
European defense spending grew 16% last year and is expected to grow at double-digit rates for the next three years, see chart below.
NATO members have committed to spend 3.5% of GDP on core defense and another 1.5% on broader security, although fiscal constraints will influence how quickly countries get there.
Recent disruptions, from attacks on subsea cables to drones near airports, to supermarket fridges and outages affecting critical infrastructure, may bring forward the need for that broader 1.5% security spending.
But where this spending goes is also broadening beyond traditional weapons and defense technology. Spending increasingly includes cybersecurity, critical infrastructure, maritime and pipeline sensors, resilient energy systems, as well as the local industrial capacity needed to manufacture and secure resilient supply chains. Many of these businesses serve both commercial and national-security markets.
The bottom line is that some of the next beneficiaries of Europe's defense buildout may sit in infrastructure, energy and industrial technology rather than in the defense sector itself.
Written by Huw van Steenis
Note: Western Europe aggregate. Sources: SIPRI Military Expenditure database, Apollo European Economic and Policy Strategist
Note: 2026 figures are estimates. Sources: NATO, Defence Expenditure of NATO Countries, Apollo European Economic and Policy Strategist
See important disclaimers at the bottom of the page.
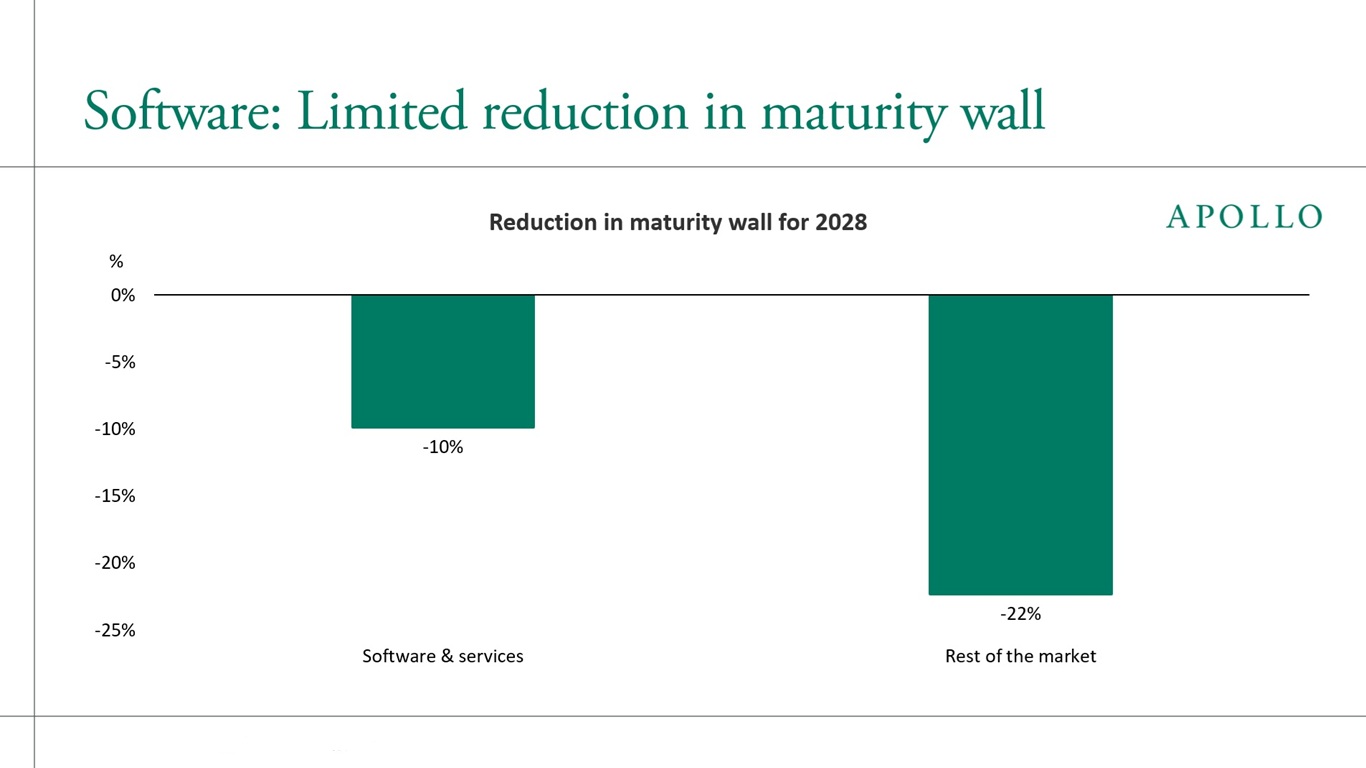
Software companies are struggling to refinance in a higher-for-longer rate environment, with the 2028 maturity wall shrinking by just 10% versus 22% for the rest of the market, see chart below.
Sources: Bloomberg SRCH, Apollo Chief Economist
See important disclaimers at the bottom of the page.
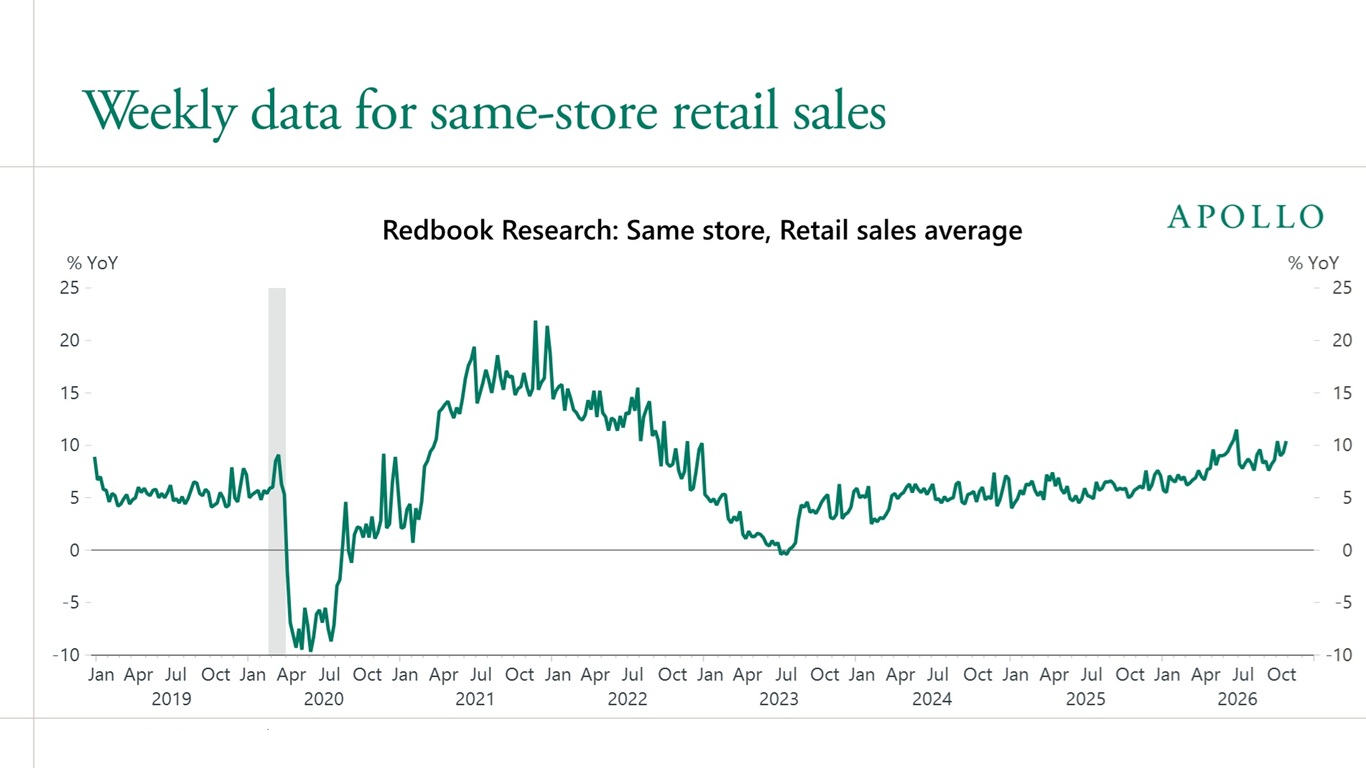
Weekly data for consumer spending continues to show strength driven by job growth for lower-income families, high asset prices and strong cash flows from fixed income for middle-income and high-income households, see the first chart below.
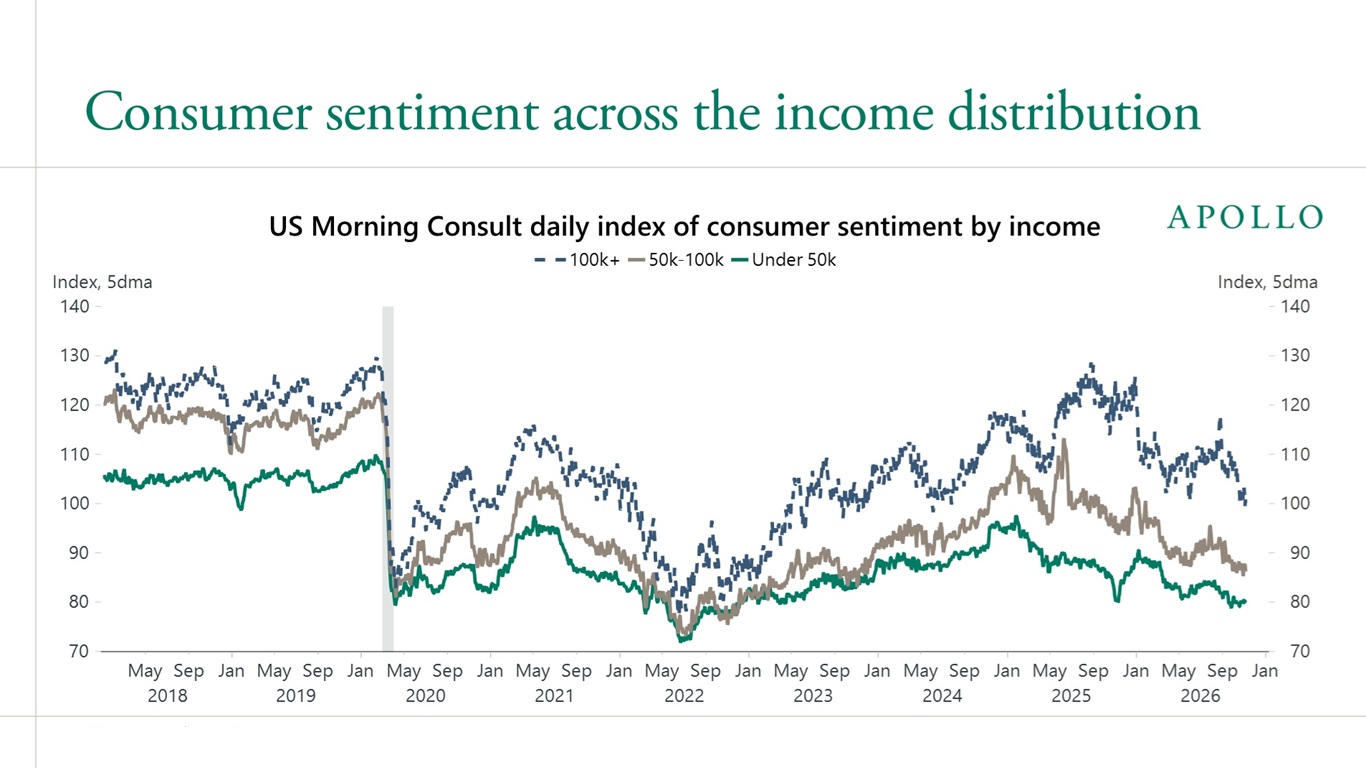
This broad-based strength in consumer spending is in sharp contrast to the ongoing decline in consumer confidence across the income distribution, see the second chart.
The bottom line is that there is a significant difference between what consumers are saying and what they are actually doing.
Sources: Redbook Research Inc., Macrobond, Apollo Chief Economist
Sources: Bloomberg, Macrobond, Apollo Chief Economist
See important disclaimers at the bottom of the page.
November 10, 2026
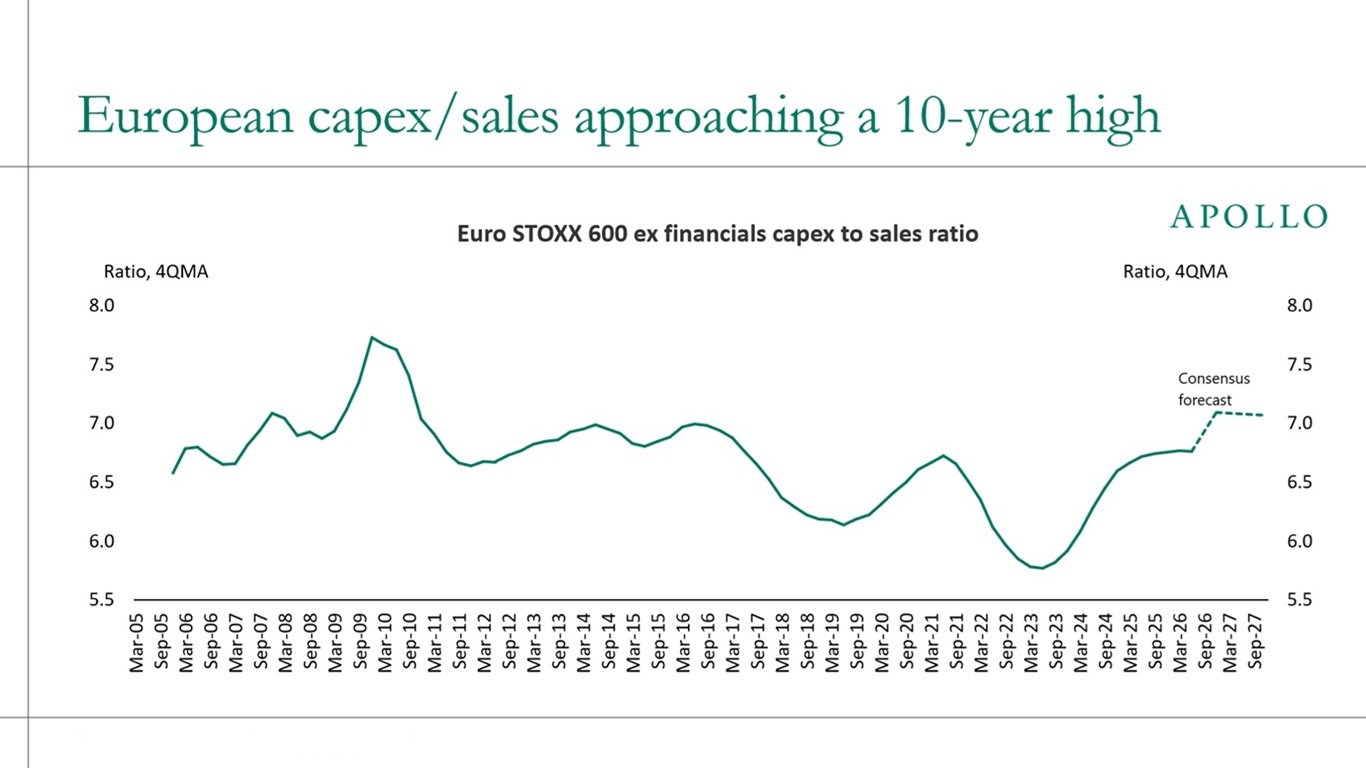
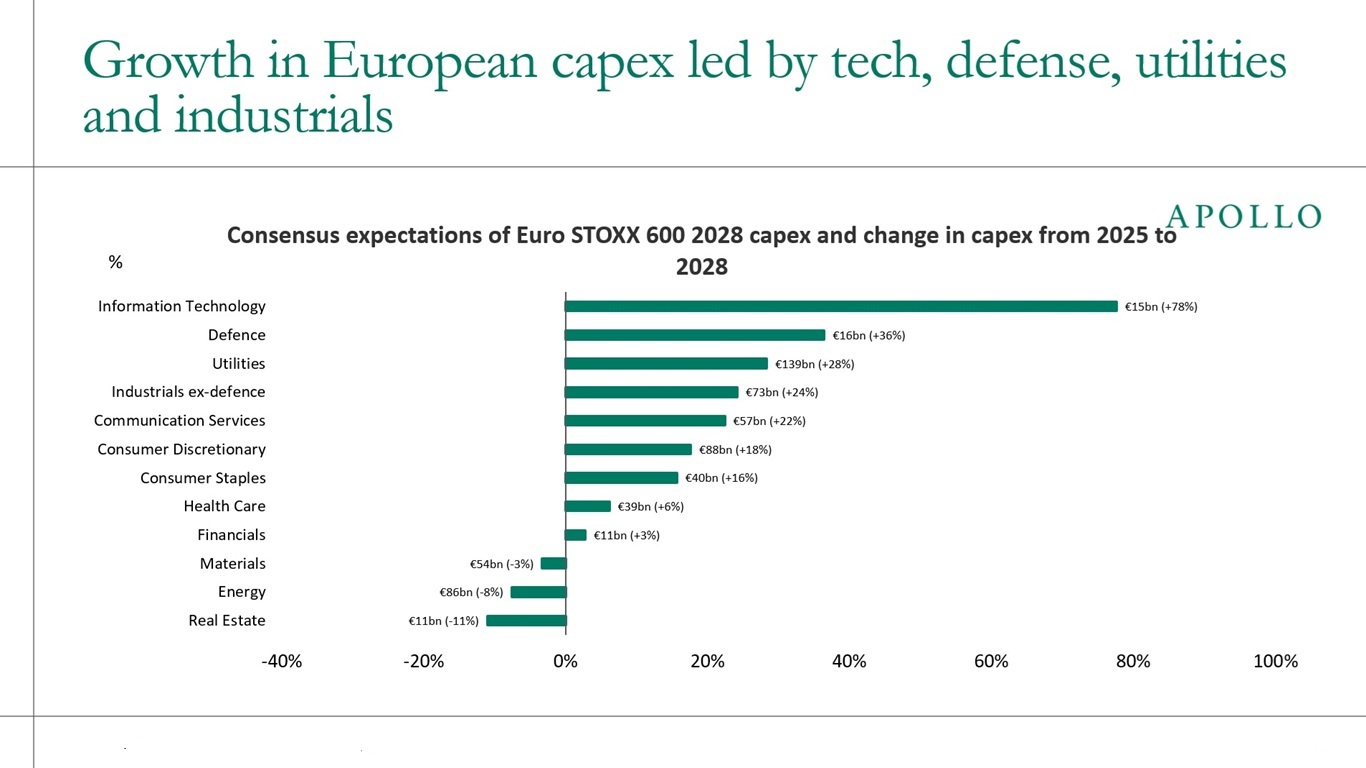
European companies are investing again. The capex-to-sales ratio is approaching a 10-year high, and European listed companies are expected to spend €77 billion more on capex in 2028 than in 2025, see charts below.
Utilities alone account for €31 billion, or around 40%, of the increase. Defense capex is expected to rise 36%, industrials excluding defense 24% and information technology 78%.
This comes after a long period of underinvestment. Across Europe, higher spending on energy, grids, defense, reshoring, infrastructure and digitalization is now lifting capital intensity.
The US capex cycle is dominated by AI. Europe's has a different mix: more of the increase is being driven by infrastructure, defense and power.
The bottom line is that capex is rebounding across Europe, and the industrial renaissance has gone global.
Written by Huw van Steenis
Sources: Bloomberg, European Economic & Policy Strategist
See important disclaimers at the bottom of the page.