Marc Rowan on how Apollo’s differentiated strategy was built for this moment.
October 04, 2026
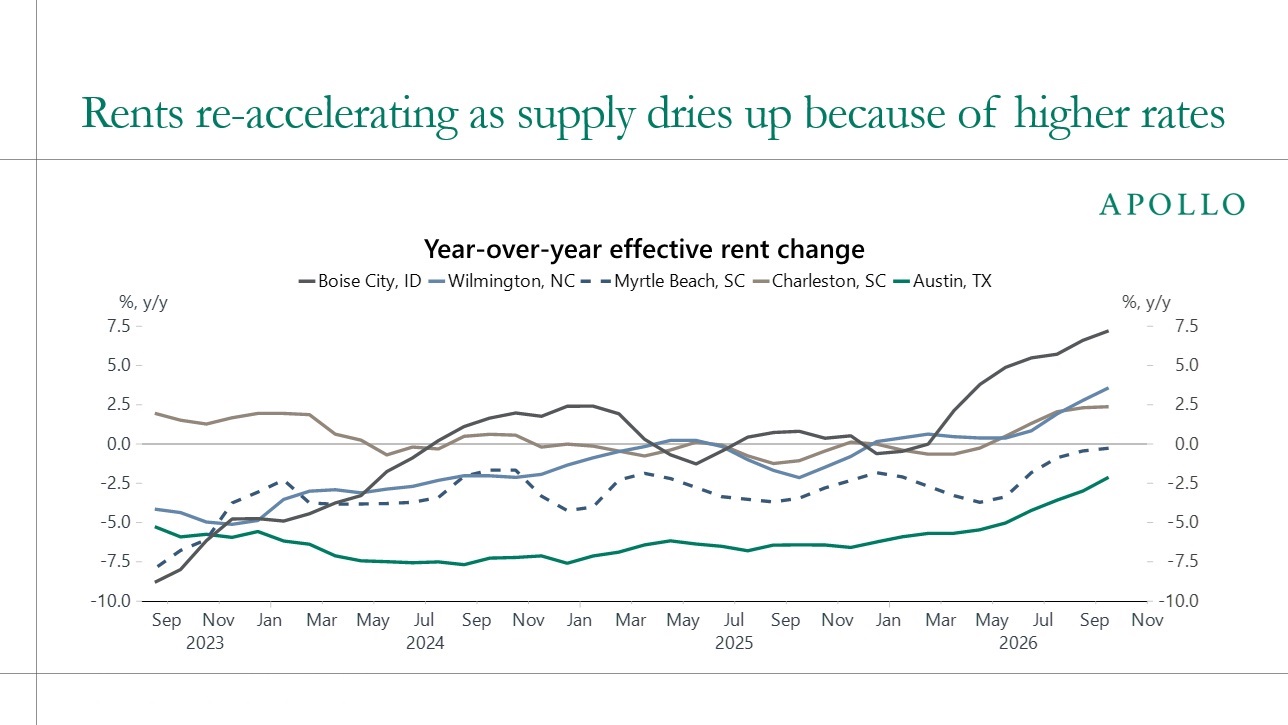
When rates are high, builders build less, and when fewer homes and apartments get built, rents go up, which pushes inflation higher and keeps rates high.
Call this the "higher rates, higher rent doom loop."
With owners' equivalent rent alone making up roughly a quarter of the CPI basket, this re-acceleration in rents is a problem for the Fed because it puts upward pressure on inflation driven by higher rates.
Sources: Apartment List, Macrobond, Apollo Chief Economist
See important disclaimers at the bottom of the page.
This new paper from Anthropic finds that robots will only be able to replace 300,000 jobs in the US economy. For comparison, total employment in the US economy is 160 million. Even under aggressive projections, widespread displacement of physical labor will take decades, and historical cost decline rates suggest it would take 40 years to reach cost parity for even 10% of jobs.
Consider nursing and general repair, where present-day robots can do almost none of the work, or the electrician threading cable through a finished wall and the home health aide lifting a frail patient, tasks that look routine to an outsider and remain close to untouchable in practice.
In fact, much of the automation that will arrive this decade has nothing to do with large language models. Car washes that scan vehicles to aim their sprayers, warehouse sortation lines and autonomous vehicles all descend from sensing and control work that was well underway before large language models arrived and would almost certainly have happened anyway.
The bottom line is that the hardest physical work is harder to automate than the consensus assumes, and the automation we do get will owe more to decades of mechanical engineering than to the current moment in AI. Almost all jobs are bundles of simple and complicated tasks, so robots that can handle the simple part still cannot do the job, which is why, for the vast majority of workers, the mess is the moat.
For investors, the conclusion is that job losses in the economy will be modest, held back by cost, by the fine manipulation robots cannot manage, by regulation and by a simple human preference for human hands.
Displacement of workers is also only one side of the ledger. US business formation stands at the highest level in the nation's history, new firms are where new jobs come from and the net effect on employment is likely to be positive by a wide margin.
The conclusion is that robots are not coming for your job, because very few jobs are a single automatable task. In other words, your job is a mess.
See important disclaimers at the bottom of the page.
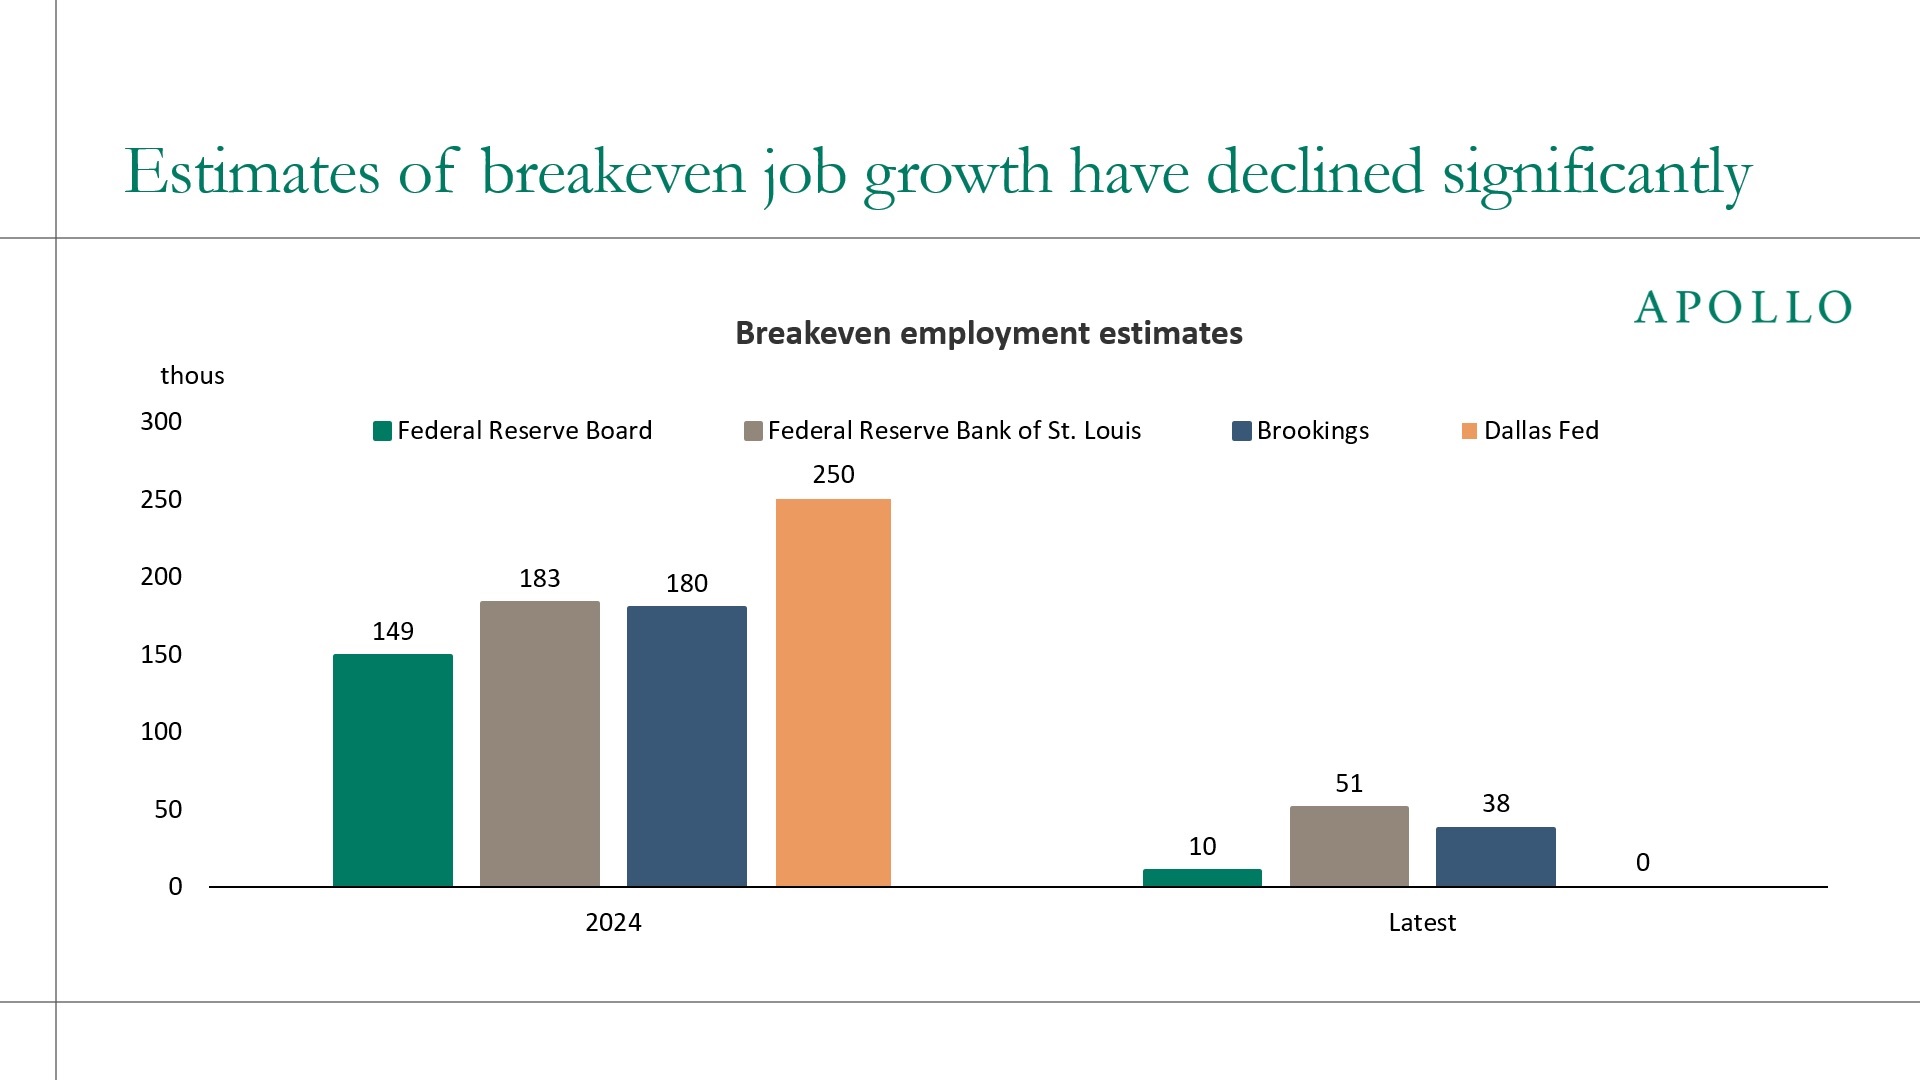
Breakeven job growth has collapsed from 200,000 per month to close to zero today, driven by a sharp drop in immigration shrinking labor force growth and continued baby boomer retirements pulling down participation. That means the consensus expectation of 90,000 jobs created in September is not a soft print but a solid one, comfortably above breakeven and consistent with a strong economy and a falling unemployment rate.
The bottom line is that with a strong labor market and inflation still significantly above the Fed's 2% target, rates will continue to stay higher for longer.
Note: Range estimates use the midpoint; Dallas Fed shows its 2023 peak of ~250k jobs/month. “Latest” reflects the most recent published estimates. Sources: Federal Reserve Board, St. Louis Fed, Brookings, Dallas Fed, Apollo Chief Economist
See important disclaimers at the bottom of the page.
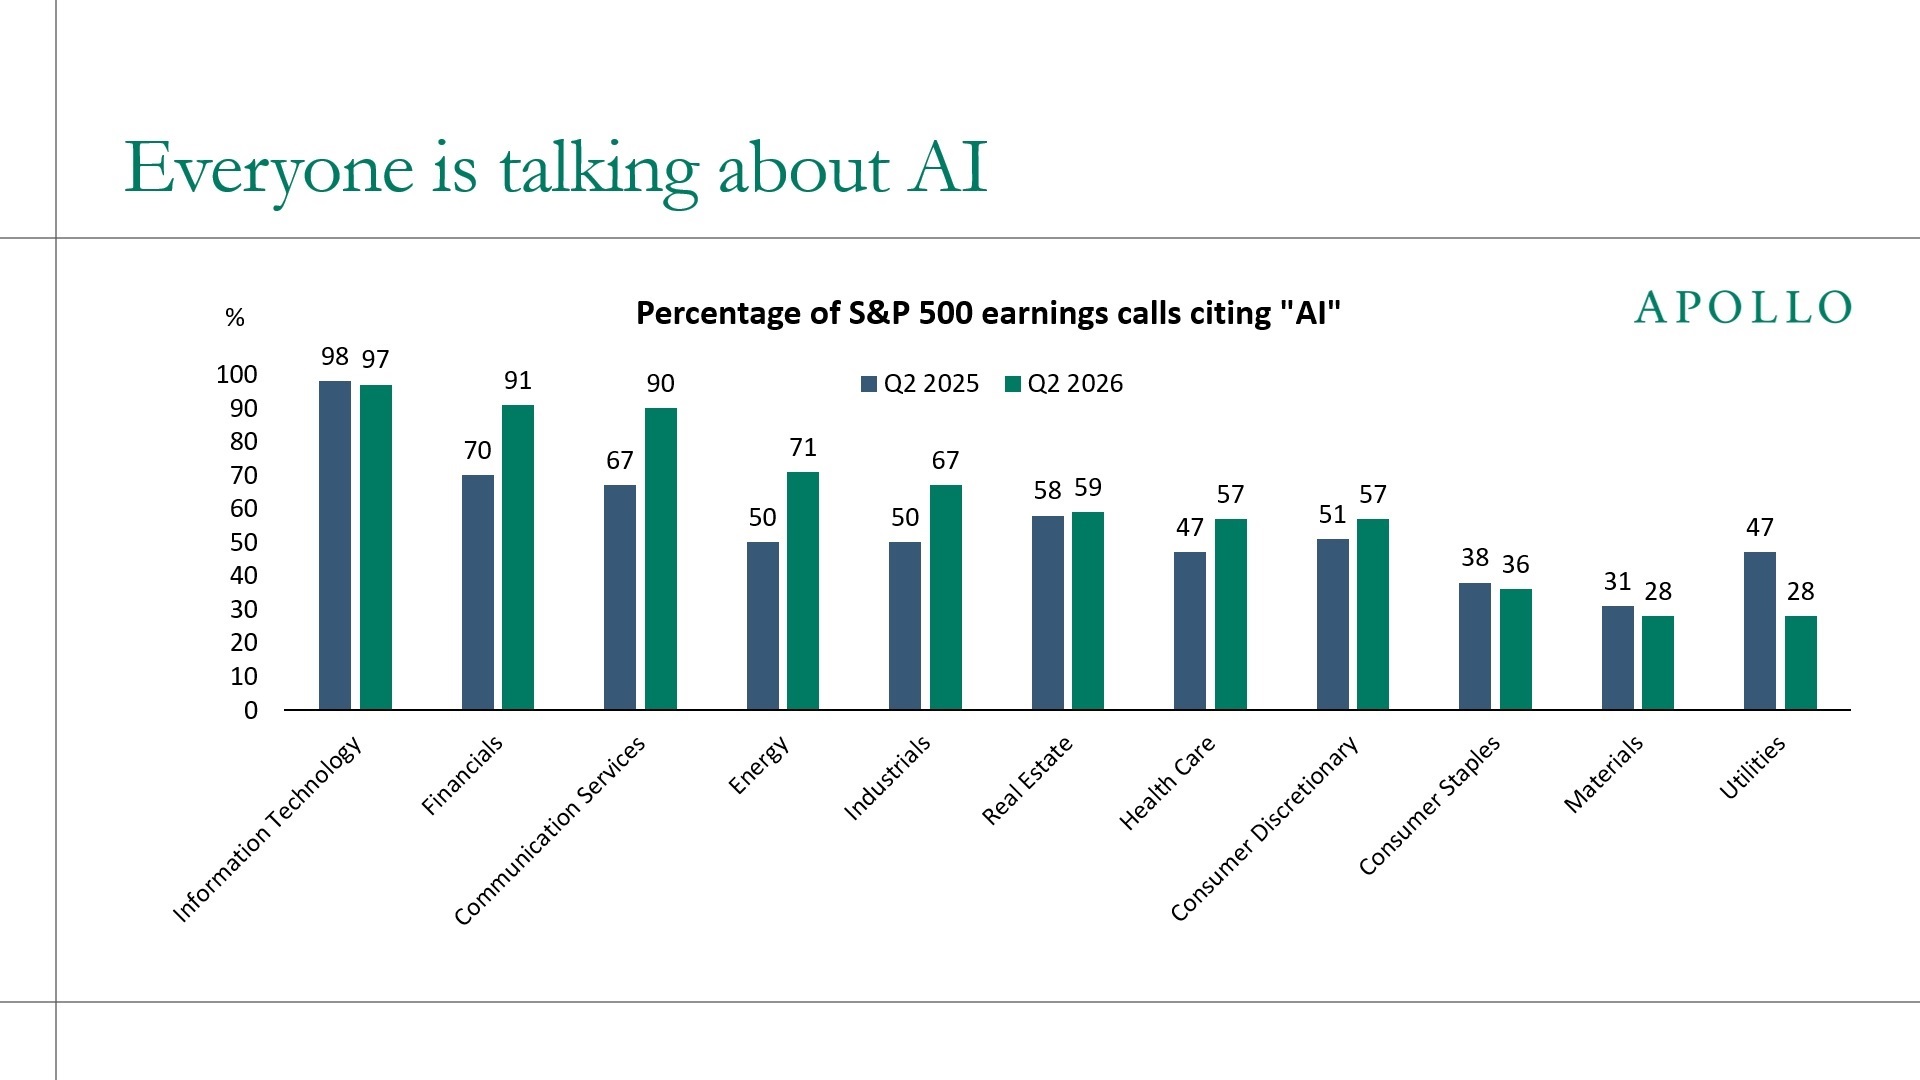
Everyone is talking about AI on earnings calls, see chart below.
That could mean companies are truly adopting it, are hyping it for investors or are planning to use it to cut costs and jobs.
The key question is whether all this talk about AI turns into real spending and measurable productivity gains.
The bottom line is that universal buzz around AI may be a sign that the hype has moved faster than the payoff.
Sources: FactSet, Apollo Chief Economist
See important disclaimers at the bottom of the page.
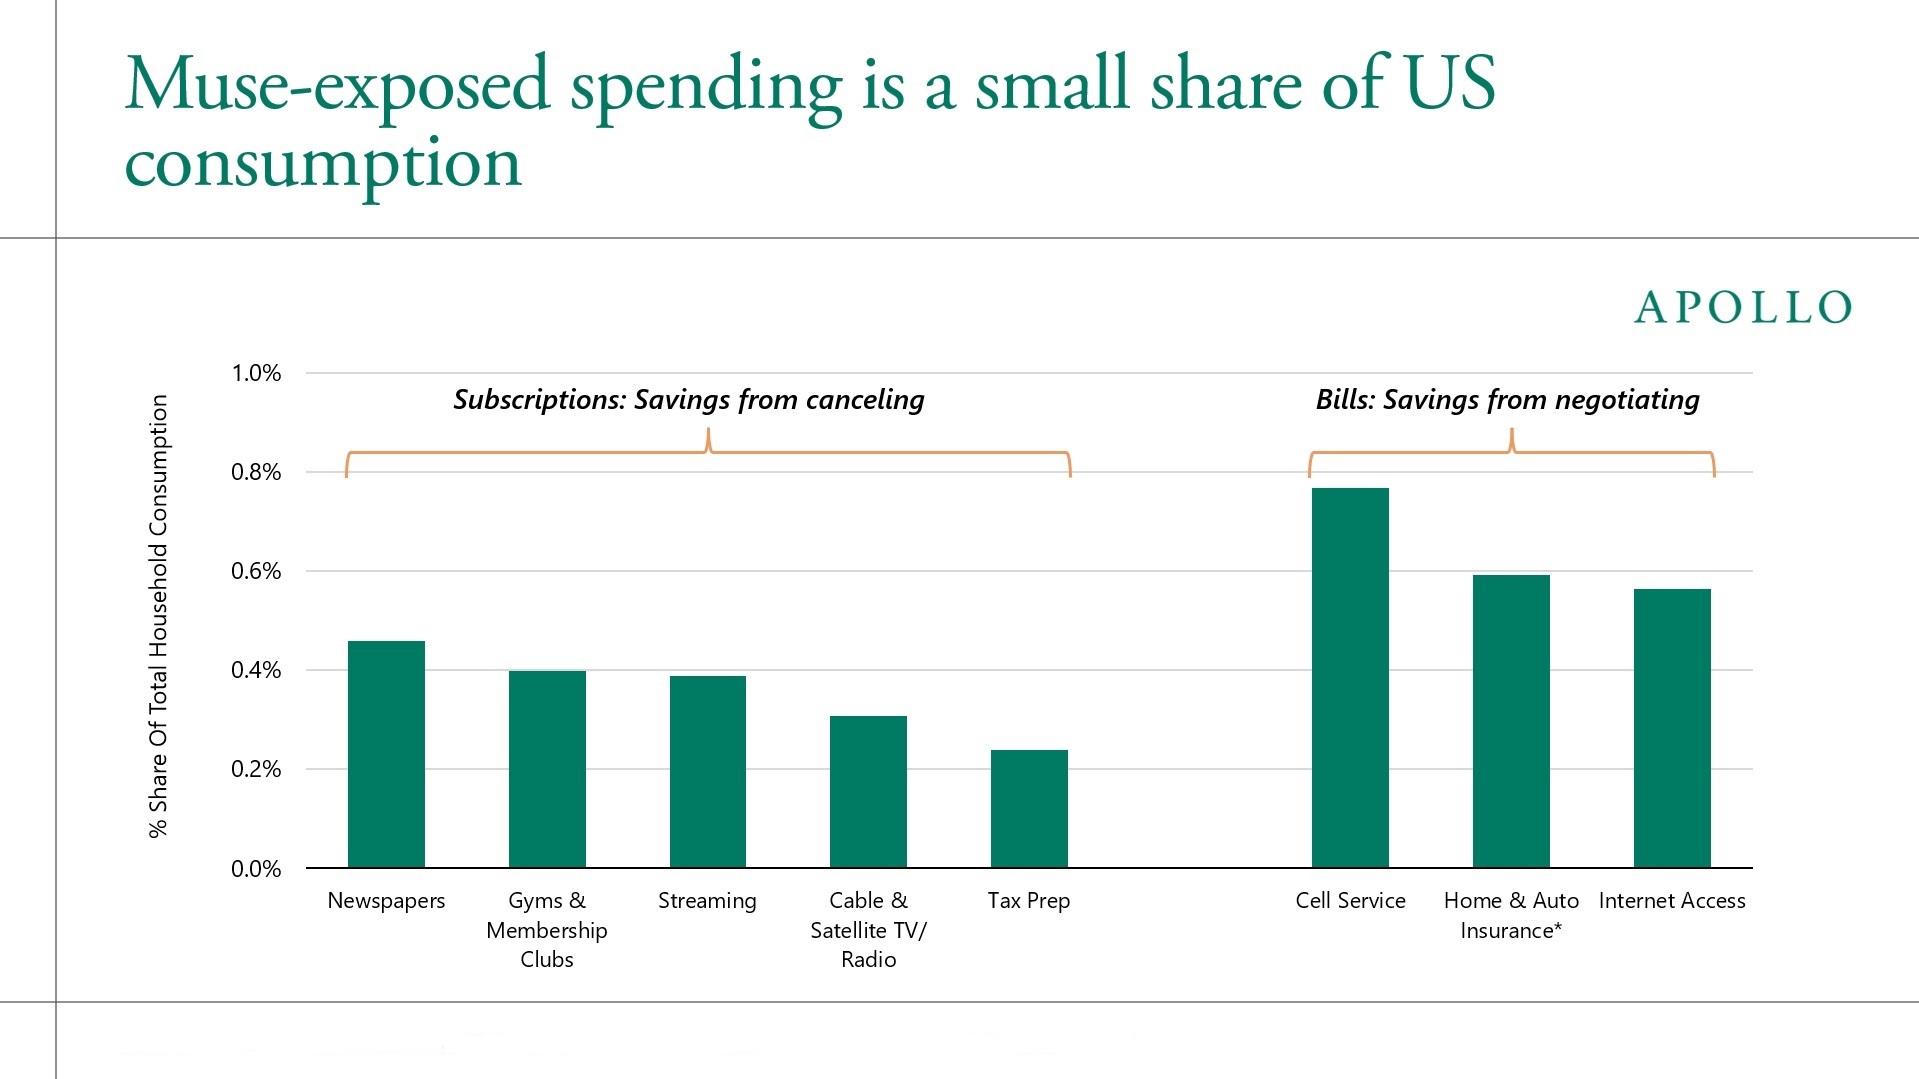
Subscription businesses rely in part on consumer inertia. In Selling Subscriptions, Einav, Klopack and Mahoney (2025) find that cancellation frictions roughly double sellers' revenues on average. Muse, an AI agent that can identify and cancel unwanted subscriptions on a consumer's behalf, could weaken those economics by making it easier to break the cycle of unwanted renewals — a concern reflected in last week's selloff in subscription-related stocks. But lost subscription revenue is not necessarily lost consumption: these categories represent a small share of spending (see chart below), and consumers are more likely to redirect any savings than put them aside. The bottom line is that Muse is more likely to change where consumers spend than derail overall consumption.
Written by Allison Boxer
As of July 2026. *Home and auto insurance is net of normal claims. Sources: BEA, Apollo Thematic Investing
See important disclaimers at the bottom of the page.
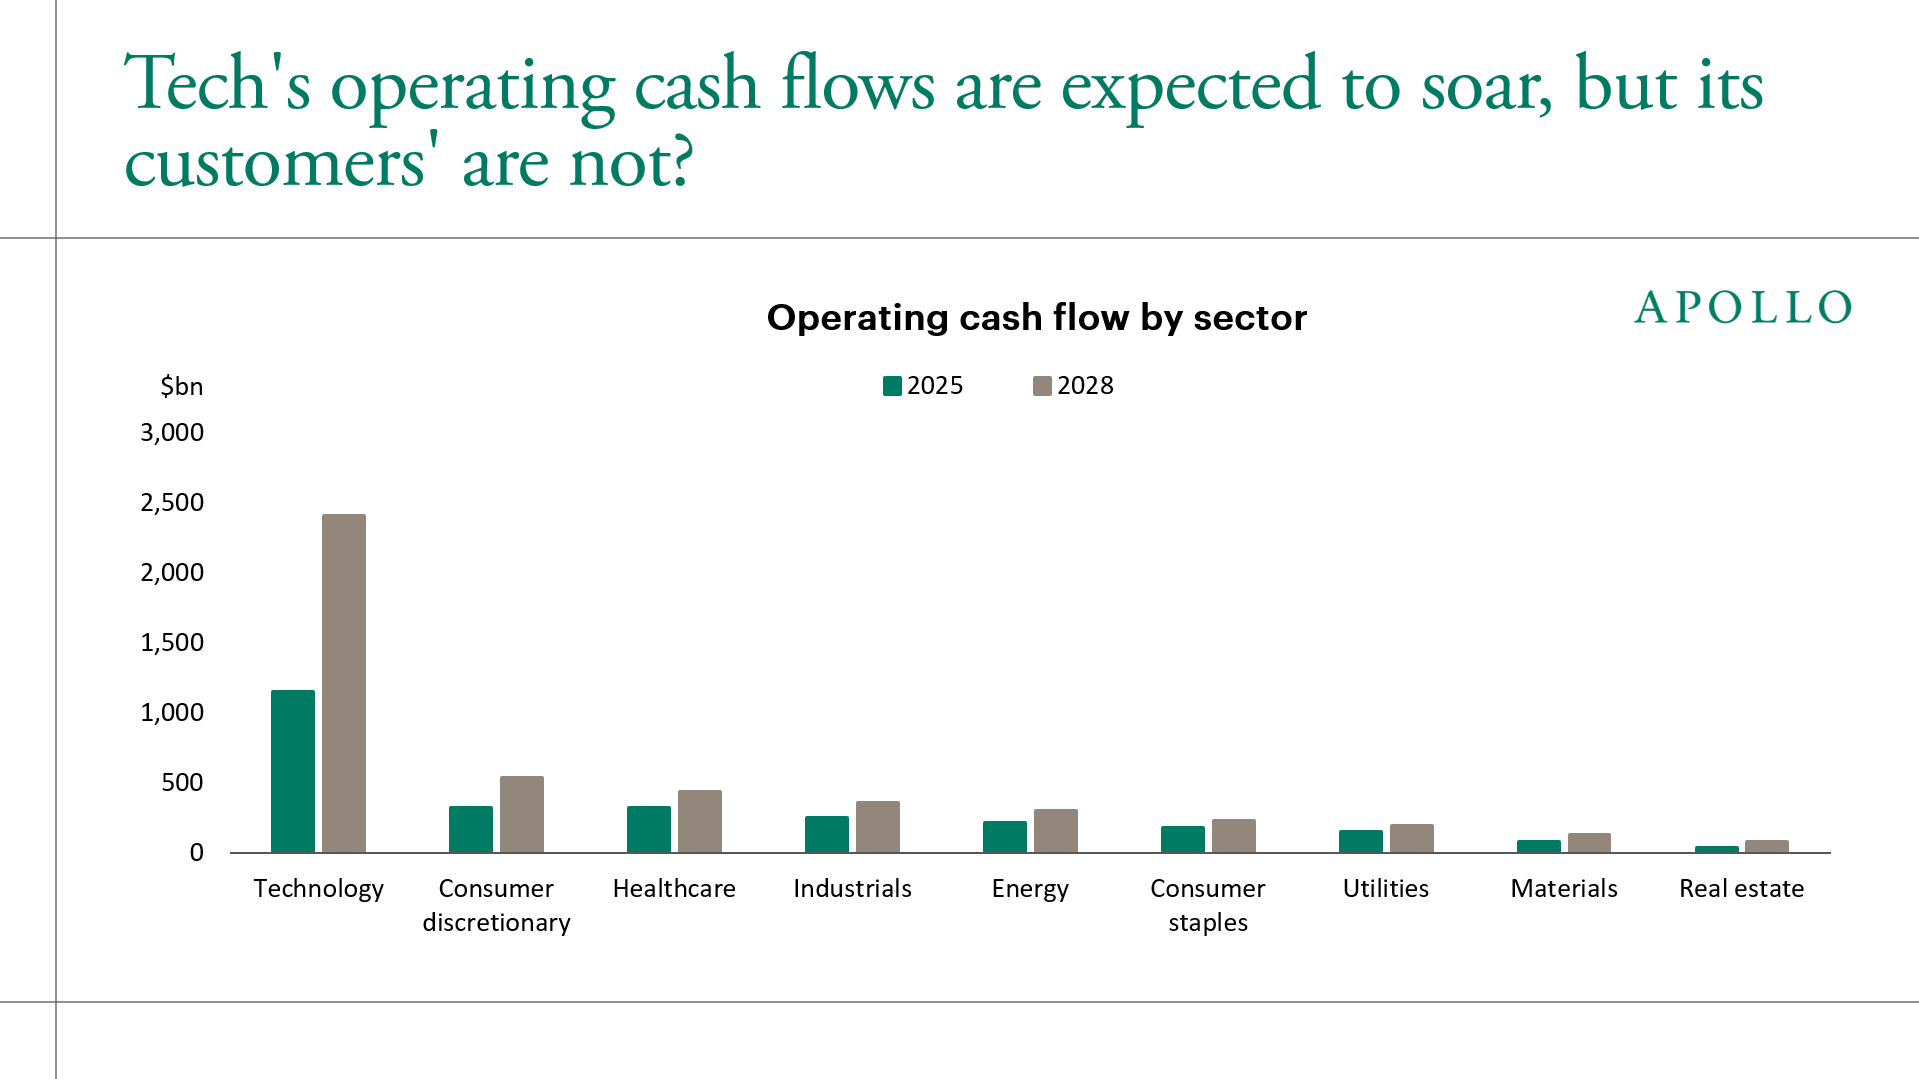
Wall Street equity analysts work in sector silos, and when you add up their forecasts, the numbers are internally inconsistent.
The analysts covering tech expect the sector's operating cash flow to more than double to roughly $2.4 trillion by 2028, an increase of over $1.2 trillion, see chart below. Meanwhile, the analysts covering the other sectors in the S&P 500, which are tech's customers, expect those companies to add much less operating cash flow.
In other words, the tech silo is betting on a future in which demand for AI and tech services explodes, while the silos covering the companies that would pay for those services see a much more modest outlook. Both cannot be right at the same time.
The bottom line is that either tech's customers will generate a lot more cash than their analysts expect, or tech's cash flow forecasts are too optimistic, which raises the question of who exactly will be writing all those checks to buy AI services.
Note: Technology includes Information Technology and Telecommunications. Sources: FactSet, Apollo Chief Economist
See important disclaimers at the bottom of the page.
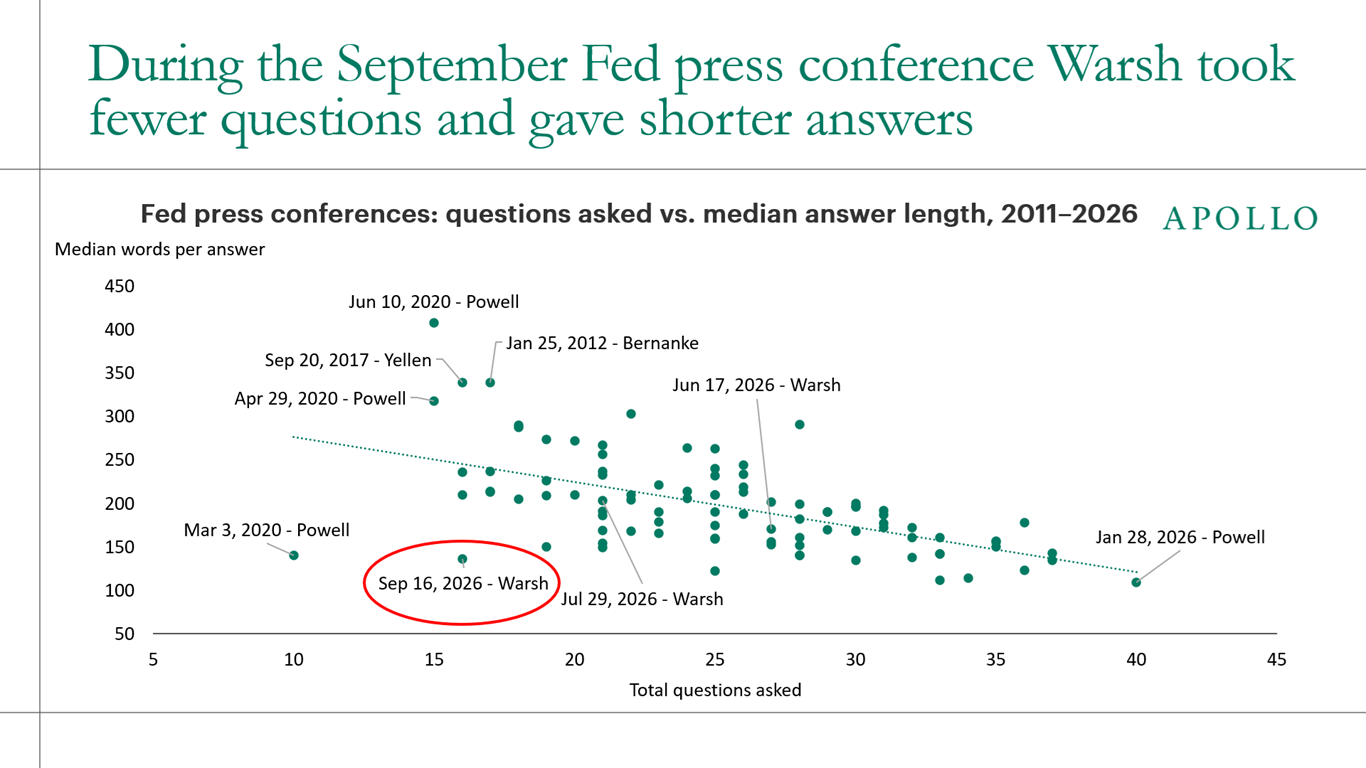
Fed press conferences began in 2011, and the chart below plots the total number of questions asked against the median words per answer for every one of them.
At his June and July press conferences, Fed Chair Kevin Warsh followed the same pattern as previous Fed chairs, but in September, he took fewer questions and gave shorter, more focused answers, letting the rate hike speak more for itself.
The bottom line is that Warsh is showing markets that the Fed can communicate clearly and concisely, with less noise and more signal.
Note: 95 briefings, April 27, 2011 (the first regular post-FOMC press conference) through September 16, 2026, roughly quarterly, at September meetings only, through 2018, then after every meeting from January 2019. A question is a journalist's utterance of five or more words or one containing a question mark; call-ons by Fed press-office moderators are not counted. Median words per answer covers the chair's replies, excluding the opening statement. Sources: Federal Reserve post-FOMC press conference transcripts, Apollo Chief Economist
See important disclaimers at the bottom of the page.
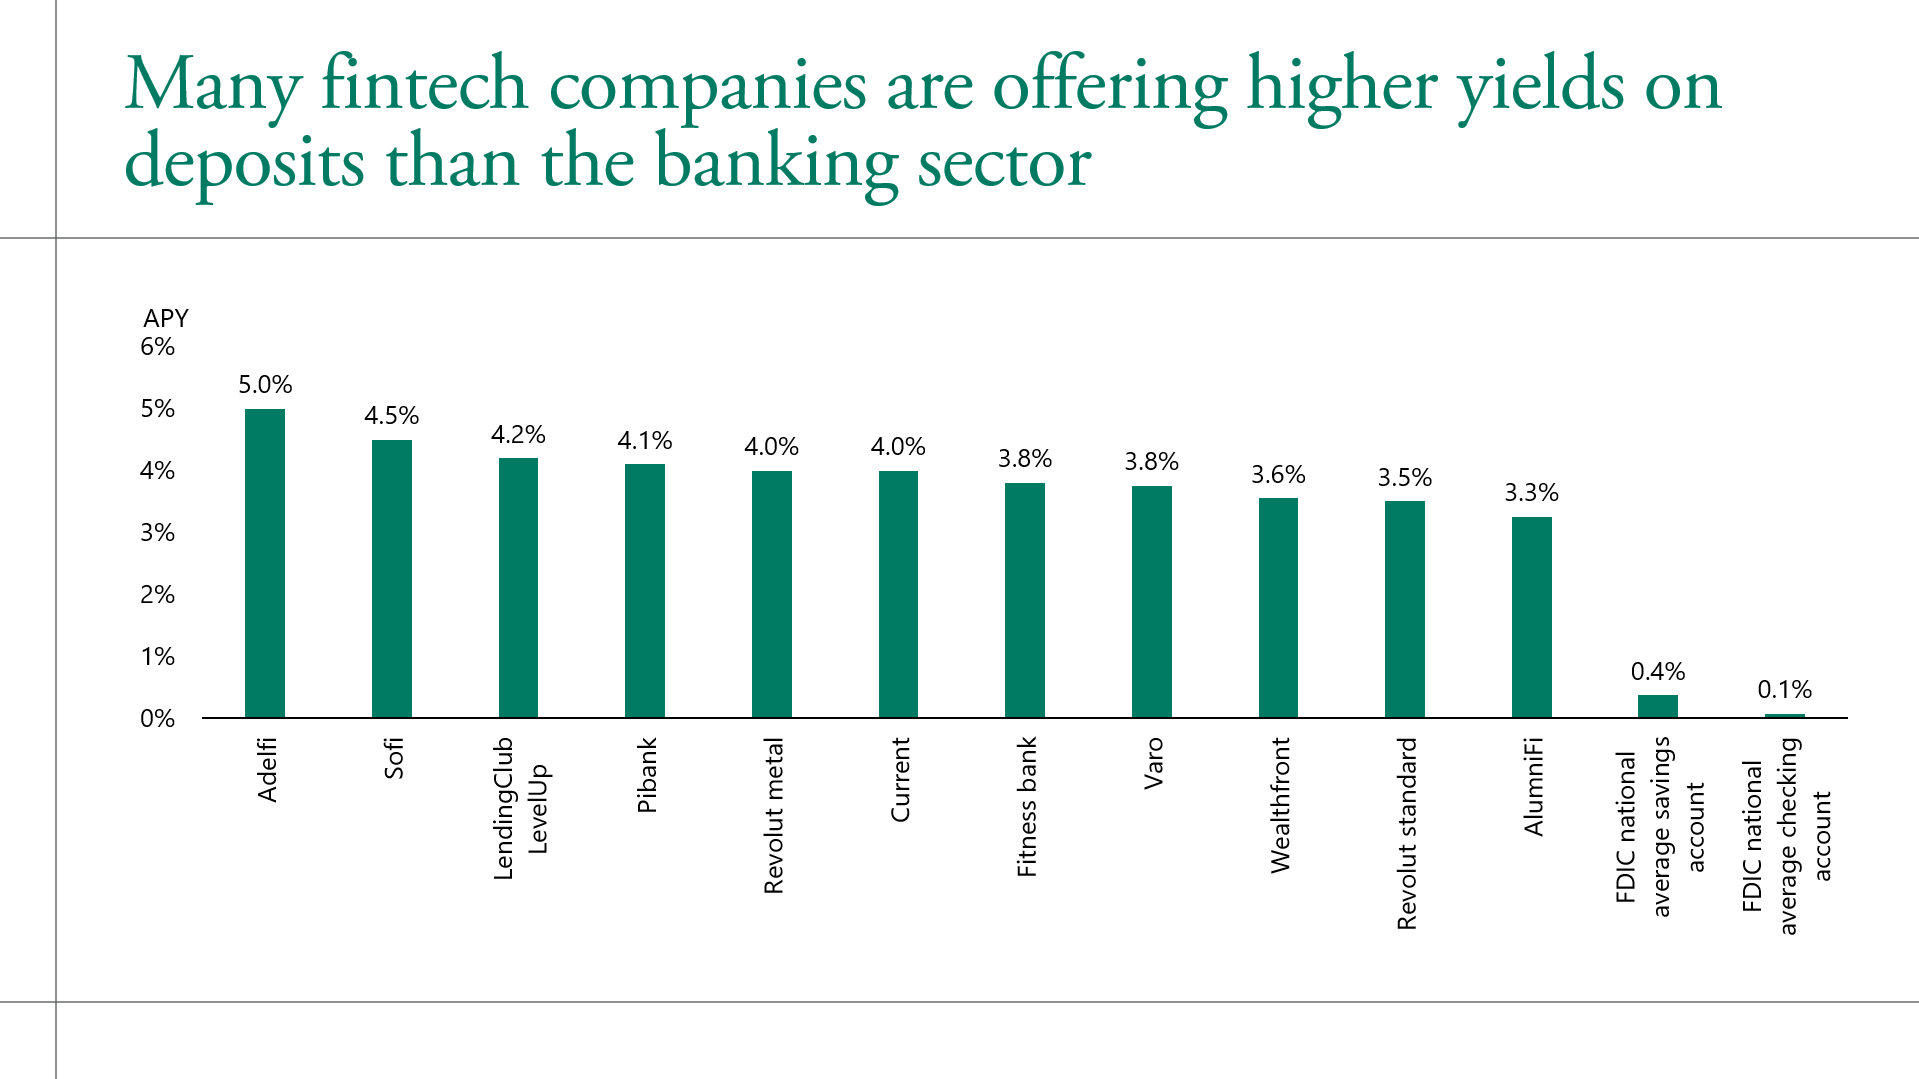
Muse and similar agentic AI assistants could soon sweep household cash automatically into accounts paying 3.3% to 5.0%, instead of the 0.1% national average on checking accounts.
If every household used AI agents to optimize the return on their cash balances, banks could lose a large share of the cheap deposits they rely on to make loans, which would be a problem for the entire financial system.
Sources: Revolut, Varo Bank, Adelfi, Pibank, Sofi, FitnessBank, AlumniFi, LendingClub, Current, Wealthfront, FDIC, Haver Analytics, Apollo Chief Economist
See important disclaimers at the bottom of the page.
September 26, 2026
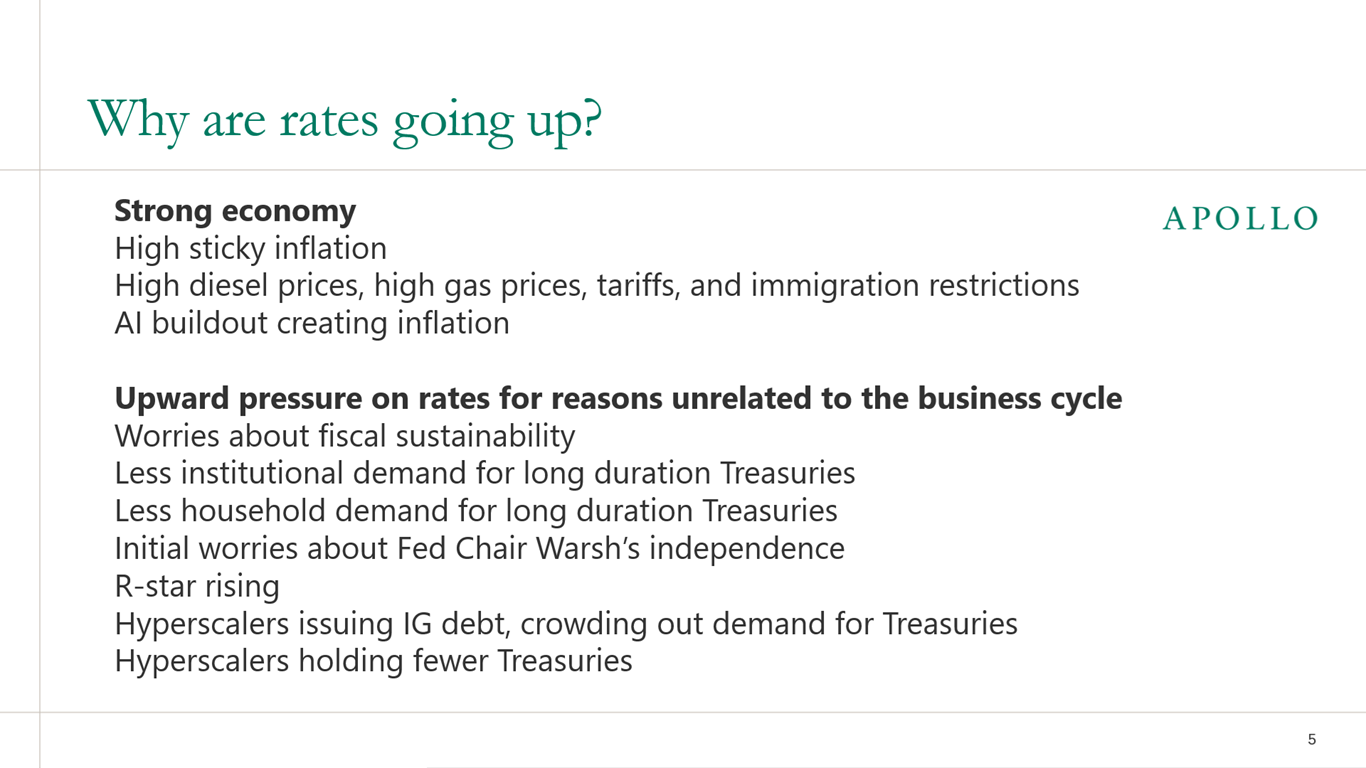
Rates are rising for reasons beyond a strong economy, with sticky inflation lifting yields in the front end, record hyperscaler debt issuance pressuring the belly and fiscal worries pushing up the long end.
For credit, yields are well above their 10-year averages, with IG paying almost 6% and leveraged loans nearly 10%, but with spreads near all-time tights and stocks and bonds moving together, investors can no longer count on bonds to hedge their equity risk.
For more, see this new chart book by my colleague Shobhit Gupta and me.
Source: Apollo Chief Economist
See important disclaimers at the bottom of the page.
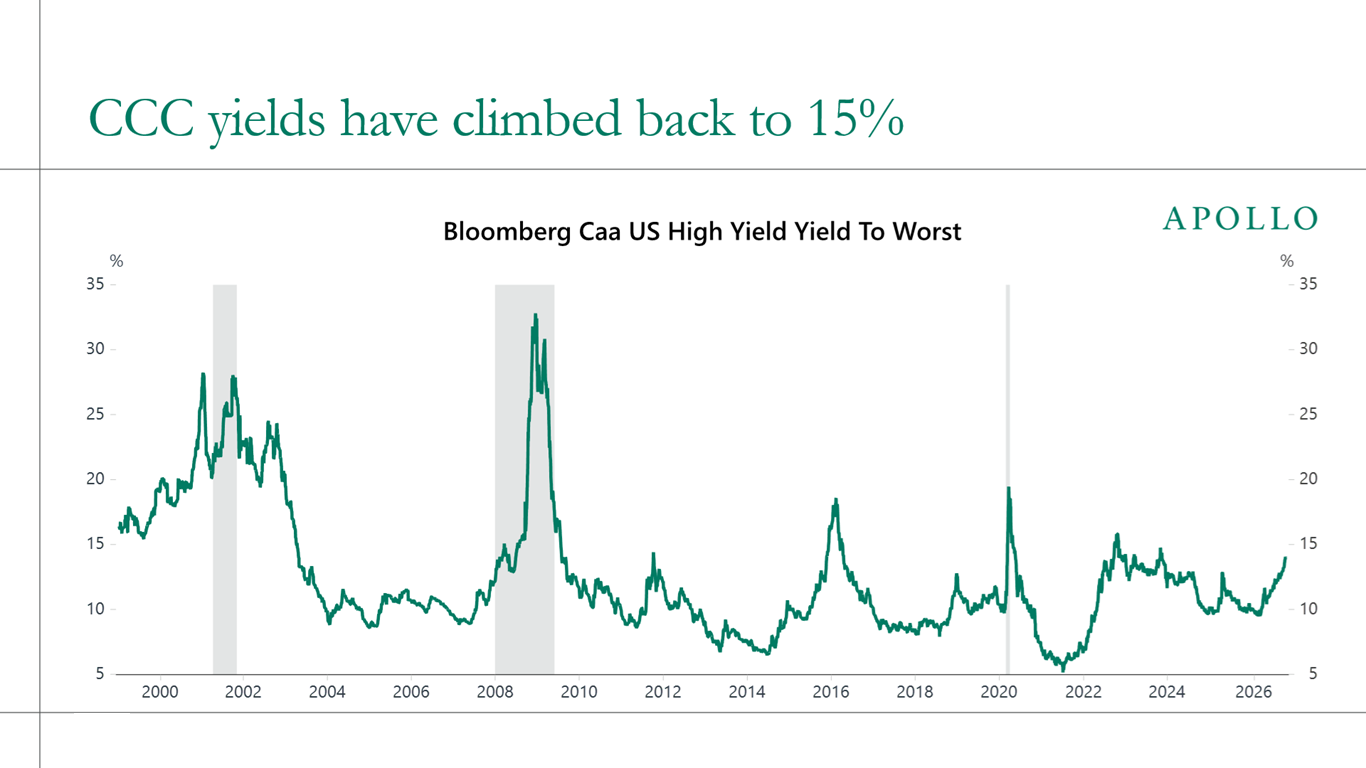
Higher for longer is a slow squeeze for low-quality credit. Every month rates stay elevated, more CCC borrowers from the 2021–22 vintages hit the refinancing wall with less cash to service their debt, and with CCC yields around 15% while the broader credit market stays calm, the bill from the cheap-money era is landing on the weakest balance sheets first.
The pain is sharpest in heavily levered, PE-backed technology, healthcare and consumer discretionary names, where floating-rate debt, thin margins and AI disruption risk leave little room to absorb years of elevated borrowing costs.
The bottom line is that monetary policy is working with a lag and working unevenly. Strong balance sheets locked in cheap fixed-rate debt and have barely felt the Fed's tightening, while the most leveraged borrowers feel it in full as floating-rate costs and maturities reset, so the transmission mechanism is running mainly through the bottom of the credit stack.
For investors, the message is to move up in quality, because high-quality credit still offers attractive all-in yields without the default, restructuring and liability-management risk that is now concentrated in lower-rated credits.
In short, it is a good idea to invest in companies with earnings because they can pay their higher debt-servicing costs.
Sources: Bloomberg, Macrobond, Apollo Chief Economist
See important disclaimers at the bottom of the page.